Real Estate Insurance: The Transfer of Risk
A breakdown of the different ways you can (and should) insure against risk
Today we are going to dive into the world of real estate insurance.
I have spent a LOT of time on this subject in the 20+ years I worked full time for real estate companies.
Insurance is a fascinating financial product that shares similarities to:
Private equity, venture capital, and stock investing.
Investment banking.
Sports betting and assembling a professional sports team.
In each case someone is making a calculated and well researched investment (or bet) in hopes that they will make money.
Insurance is a financial instrument where insurance companies earn smaller guaranteed payments (premiums) while putting big dollars at risk (claims). Their goal is to make more money on the premiums than they pay out in claims over years and decades.
I will break down the basics of real estate insurance in a way you can understand and use. As a real estate investor, you will need (and likely be required to carry) insurance to protect you, your investors, your lender, and your property.
Today we will cover:
What insurance actually is
Types of real estate insurance
Premiums, limits, deductibles, policy term, & exclusions
Insurance policies
Insurance certificates
Lender insurance requirements
Working with an insurance broker
How to handle an insurance claims
Why you should strive to be a good customer to the insurance carriers
Let’s dig in.
What Insurance Actually Is
At its most basic level, insurance is a financial transaction: small amounts of guaranteed money for major risk protection.
For example, you own a property that would cost $200,000 to re-build if it were destroyed. You don’t have $200,000 sitting around, so you would be in a bind if the property were destroyed.
Enter the insurance company aka carrier (ex. State Farm, Liberty, Allstate, etc).
They offer to insure the property for $1,000 per year.
You pay the $1,000 at the beginning of the one year policy.
The insurance carrier will pay the cost to rebuild the property IF it is destroyed. Either way, they keep the money you paid them.
This same concept applies to many other types of insurance: auto, life, health.
The person buying insurance pays a small fixed amount. The insurance carrier keeps the money and only pays if there is a claim (damage, a medical procedure, etc.).
Now let’s get specific to real estate insurance.
Types of Real Estate Insurance
I am going to focus on insurance you would have as a personal real estate investor.
[Note: if you own a real estate company (or any other company) with employees, there are many other types of “corporate” insurance you would want such as worker’s compensation, crime, etc. Talk with your insurance broker to learn more.]
There are two types of insurance you will want as a real estate investor: property and liability.
Property Insurance - Insuring Physical Objects
Property insurance covers physical objects from damage, theft, and destruction. Effectively, anything that could harm the object. In the case of real estate, “objects” are:
The building and anything attached to it such as HVAC and lighting.
Any supplies stored in the building such as light bulbs and carpeting.
12-24 months of rental income you could lose while the building is being repaired if the tenants are unable to occupy the building and pay rent.
Think of property insurance as insuring against damage. How could the property be damaged? Fire, theft, hail, storm, wind, earthquake. It could be anything.
Liability insurance is totally different.
Liability Insurance - Insuring You From Being Sued
Liability insurance covers you if you are sued.
Let’s say your tenant or one of their customers/employees trips just in front of the entrance to the tenant’s suite. They break their arm and have medical bills. They could sue you.
If you are sued, the liability insurance coverage kicks in to defend the lawsuit and pay for damages (if any).
In summary, property insurance protects the building and rents. Liability insurance protects you if you are sued.
Pro tip: For additional liability protection beyond your standard policy, consider an umbrella policy that provides extra coverage (typically $1-5M) for a relatively low premium.
Additional Pro Tip: If you are developing a property from the ground up, property insurance will be known as “Builder’s Risk” and liability insurance will be known as “Owner’s Interest”.
So far, so good.
Now let’s dive a level deeper.
Premiums, Limits, Deductibles, Policy Term, & Exclusions
There are five key factors that come into play with insurance:
Premiums: how much you have to pay for insurance each year.
Limits: the maximum amount the insurance carrier will pay if there is a claim.
Deductibles: a small amount you pay if there is a claim (in addition to the premiums).
Policy Term: the length of the policy (ex. 12 months).
Exclusions: what is NOT covered.
Let’s briefly discuss each one.
Premiums
Premiums are the fees you as the person buying insurance pay. It is the insurance carrier’s revenue.
Limits
Limits are the maximum amount the insurance carrier will pay if there is a claim. Two examples:
$200,000 property claim and the policy limit is $150,000.
The carrier will pay $150,000 (policy limit < claim).
$100,000 property claim and the policy limit is $150,000.
The carrier will pay $100,000 (policy limit > claim).
Pay attention to your limits to make sure they give you adequate coverage.
Deductibles
If you have ever paid attention to a health insurance claim, you are probably familiar with a deductible. It is the additional amount you have to pay (in addition to your premium) in the event there is a claim. In the $200,000 example above, the deductible might be $1,000. You would pay this as part of the claim, but you only pay it in the event that there is a claim. The concept is that you will have to cover minor costs and the insurance carrier only steps in for more “major” claims.
Policy Term
This is the length of the policy. Most policies for real estate are 12 months.
Exclusions
Certain events will not be covered under your typical property or liability policy. If you want this coverage, you will need to buy a separate (and often more expensive) policy for this specific risk. Sometimes they are included in your property policy with higher deductibles. Examples of exclusions include: (i) earthquake risk in California, Oregon, and Washington, (ii) hurricane risk in the Gulf of Mexico region, (iii) hail risk in Colorado and Texas, and (iv) environmental pollution.
Note that “wear and tear” is almost never covered by insurance. The 20 year old HVAC unit that stops working will not be a covered claim.
Pro Tip: Look out for “vacancy exclusions”. Vacant buildings are at higher risk for theft and vandalism. Most policies exclude coverage for vandalism and theft for buildings (not suites) that have been vacant for 90+ days. Make sure you read your policy to understand this risk and consider better lighting and/or security for vacant buildings.
Let’s transition to the actual policy.
Insurance Policies
An insurance policy is the document provided by the insurance carrier. It is a legal document that outlines all the terms of the policy.
In an ideal world you would receive a draft of the document 30 days before the start of your policy period. In the real world, these normally come 10-60 days after the policy starts.
A good insurance broker will help you negotiate the best deal points of the policy and compare the options from multiple insurance carriers.
Think of the insurance policy as adding all the specific details of the items we have discussed so far (premiums, limits, deductibles, etc.).
The policies are long and written as legal documents. For the industrial property I own, the policy is 50+ pages. A practical approach for those of you who cringe at the idea of reading one is to focus on the following:
Is your name and/or legal entity correct?
Is the property address correct?
Are the dates in the policy term correct?
Review the premium, limits, deductibles, policy term, & exclusions.
Review the vacancy exclusion language.
Make sure you know who to contact if you have a claim.
Most of the time you won’t have a claim. But when you do, you don’t want to be caught discovering that you didn’t have the coverage you thought you did.
Is there an easier way to understand your policy?
Yes.
Enter insurance certificates.
Insurance Certificates
Whereas a policy includes all the legal language of your policy, an insurance certificate is a one page document that summarizes your policy.
It will list the type of coverage (property, liability), limits, deductibles, policy term, and sometimes exclusions.
It is also where the insurance carrier will add “additional insured” parties as required by other documents you sign such as a property management agreement or loan agreement.
An “additional insured” has limited coverage under your policy in the event of a claim without having to pay anything for this coverage.
This is especially true for lenders.
Lender Insurance Requirements
If you have a loan on your property, you will have a set of loan documents as discussed in Debt: An Amazing Tool with Strings Attached.
The loan documents will list various lender insurance requirements that must be met for the lender to give you the loan.
These could include:
The types of coverage: property, liability, earthquake, etc.
The amount of coverage: example - property insurance equal to the full replacement cost of the building.
The maximum deductible allowed: example - $1,000 or $5,000.
Make sure you price out insurance coverage that meets the lender requirements BEFORE you sign the loan agreement.
An insurance broker can be very helpful in this process
Working With an Insurance Broker
You want to work with an insurance broker that specializes in real estate insurance.
They will help you compare insurance options to find the best combination of price and coverage. They know what is “market” and they will help you find the right fit for you.
Ask people you know who have invested in similar properties for a referral. A good insurance broker will make a world of difference.
They will also help you work your way through a claim.
How to Handle Insurance Claims
Insurance claims are a whole separate animal. They can be simple or long and tedious.
I won’t go into much detail, but here are what I believe are the best practices having navigated claims ranging in size from $25,000 to $10,000,000+.
Communicate early. If you think there MAY be a claim, let your insurance broker and carrier know immediately. There is no penalty or risk of an increased premium next year if there doesn’t end of being a claim.
Ask questions. You will likely be assigned a “claims adjuster” by the insurance carrier. Ask for clarification of the process and timeline.
Be persistent. Claims adjusters often have an unmanageable workload. Don’t be a jerk, but be persistent.
It is a process. Not a fun one, but one that can be navigated. It will help if you are already a good customer.
A note on asset classes and claims. Different asset classes tend to have different types of claims and frequency of those claims.
Multifamily and 1-4 Unit Residential: highest claim volume from “slip and falls” and kitchen fires.
Retail and Office: “slip and falls” are most common claims.
Industrial: theft of copper and other “recyclable” materials are most common claims.
Go in eyes wide open as you consider your asset class and strive to be a good customer.
Why You Should Strive to Be a Good Customer to the Insurance Carriers
What does it mean to be a good customer to the insurance carrier? It means:
You pay your premiums on time. This is their revenue.
You maintain your property well and have good standard operating procedures. This leads to lower risks of claims.
You are loyal. You don’t switch carriers every year.
An insurance company will look at you (their customer) in terms of how you have performed over the life of the relationship. Remember that their goal is to make more money on the premiums than they pay out in claims over years and decades.
You are more likely to have lower premiums each year (and a better claim outcome) if you have been a customer for five years without a claim than if you are three months into your first policy year with the company.
Don’t necessarily change carriers every year to save a few bucks. Think of it as a long term partnership.
Pro tip: as you build up a portfolio of properties, look into putting them into a single “portfolio” insurance policy. This could save you money and make things simpler to operate.
Closing Thoughts
Don’t be intimidated by insurance. Understand that it plays an important role in the world of real estate investing.
View it with curiosity and always be learning.
The Property Manager: On the Front Line of Your Property
Why the relationship with your property manager is so important
As we did last week, let’s anchor in on where we are in the process of learning how to be a real estate investor.
You own your first property.
You have a business plan and are in the early stages of executing it.
You have hired a local property manager.
You are eyes wide open that unexpected issues will come up.
You understand how to review the monthly reports.
Today we are going to discuss how to work effectively with your property manager.
Your property manager is on the front line of your property. They are the main point of contact with tenants and vendors.
Your tenants’ experience of the property will be based on four things:
Where the property is physically located.
How much rent they have to pay.
The physical condition of the property.
How the property manager responds to their requests and challenges.
You can’t change the location and you want to maximize the rent. The physical condition is generally fixed other than the ability to maintain it and possibly improve it.
It is the performance of the property manager that is the most malleable. It is one of the few things that you as the property owner have the ability to influence.
Today we will discuss:
The role of the property manager.
Why being a property manager is so challenging.
When to hire a property manager and how to find a good one.
The importance of setting clear expectations relative to your operational philosophy and goals.
How much discretion to give the property manager.
What to do when things aren’t working out.
Let’s dig in.
The Role of a Property Manager
A property manager is the person or team that manages the property for you on a day to day basis. They will likely be an employee of the company you hire to manage your property.
In addition to the monthly reporting package generated by their team, they have two main focus areas:
Tenants
Vendors
Tenants
Property managers respond to tenant requests and give tenants direction. They use the lease (and instructions from the owner, if any) to determine how they respond to issues. Here are some examples of issues that will come up with tenants.
The tenant is paying rent late.
The HVAC unit in the tenant’s suite stopped working and needs maintenance.
The tenant is leaving trash in the common area.
The property manager has to interpret how to handle the issue, get approval from the owner, communicate the resolution to the tenant, and make sure the tenant cooperates.
This is very easy to say, but hard to do.
Vendors
Property managers also hire vendors to maintain, repair, and upgrade your property. Some of this is done proactively. Some of this is done reactively. You as the owner set the direction of the maintenance standards, but it is the property manager who has to execute this. Here are some examples of issues.
Exterior maintenance relative to cleanliness and the landscaping.
Preventative maintenance (if any) of the building systems.
Want to operate your property like a slum lord? It falls on the property manager to execute this and face the consequences of the unhappy tenants.
Why Being a Property Manager is So Challenging
Let me state this clearly:
The role of a property manager is one of the hardest in the real estate industry.
Why?
There are multiple reasons:
Lack of Time Control: a property manager is faced with a variety of issues each day, many of which are unplanned and time sensitive. Things break. Emergencies happen. Property managers have a very hard time keeping control over their schedule and time.
Workload: property management is a low margin business. Owners of property management firms tend to overload their property managers with a heavy workload.
Context Shifting: a property manager is a jack of all trades. From communicating with a tenant, to analyzing a lease, to reviewing and commenting on a financial report, to preparing a vendor contract, to interpreting a technical building issue - a property manager has to do it all, often in a single day.
80/20: 80% of what happens at a property goes well and unnoticed. It is the 20% of issues that go wrong (most of the time outside of the property manager’s control), that get noticed and complained about to the property manager. It can be a thankless job.
Let me say it again.
The role of a property manager is one of the hardest in the real estate industry.
The good ones do all of this with amazing customer service and keep everyone happy.
I have SO much respect for property managers.
When to Hire a Property Manager and How to Find a Good One
Some of you may be considering managing the property yourself. That is fine, but proceed with caution.
I did this for a year on my property. It is like taking on a part-time job. Once I received an emergency call while on vacation with my family, I realized I would much rather pay someone else to do the work.
Hiring a property manager is particularly important if any of the following criteria apply to you:
You don’t live near the property.
You have a full time job.
You have a low tolerance for customer service issues.
You put a high value your time and mental peace.
The good news is that there are great property managers out there. Here’s how to find one.
Ask for referrals. Search the internet. Ask AI. Note: referrals are the best.
Interview 2-3 firms. Yes this will take time, but it will give you a good comparison.
Check references. What are their existing clients saying.
Request an example monthly report.
Discuss your operating philosophy and goals.
You don’t always want to go with the cheapest option. Find the one that has the right balance of costs and service - and who is on board with your philosophy and goals.
A note of fees: property managers typically charge a fee based on percentage of rent collected from the tenants each month. This varies by market and property type. Here’s a rough range to give you an idea:
1-4 Unit Residential: 8-10%
Large Multifamily, Retail, Office, and Industrial: 3-5%
They may also charge fees for construction management, leasing, and other “one time” services.
Once you select the right property manager for you, make sure you set clear expectations.
The Importance of Setting Clear Expectations Relative to YOUR Operational Philosophy and Goals
In a previous newsletter - Daily Issues You Will Face While Owning Real Estate - I discussed the importance of being clear on your own operating philosophy using three types of cars as an analogy:
Do you want to operate the property like a top of the line Mercedes, a reliable but basic Honda, or a car that constantly breaks down?
If you don’t understand your own philosophy and goals, your unfortunate property manager will either (a) constantly be guessing at how to handle issues and coming to you regularly for direction or (b) taking action on issues that may or may not be what you want.
Take the time to be clear on your philosophy and goals.
Once you do this, you can set the framework of a good working relationship with your property manager that will benefit your property. Here are the specific steps I recommend:
Send an email to the property manager explaining your philosophy and goals.
Meet with the property manager onsite to walk the property and discuss your philosophy and goals. Make sure you take the time to get to know your property manager and understand their daily workload outside of your property.
Agree upon expectations for how the property will be operated day to day.
Agree upon how often you will have a call or meeting and what will be covered. This will be much more efficient than ad hoc communication.
Agree upon what communication should fall outside of the call/meeting schedule. What should qualify as an emergency? Do you prefer texts, calls, or emails?
Agree to check in after 90 days to discuss what is working and not working.
Setting the foundation up front will help establish a clear working relationship that will benefit each of you and the property.
Here are some examples of how you can operate a property to give you an idea of how to develop your own operating philosophy.
Tenant Compliance
“Letter of the Lease”: strictly interpret the lease. Don’t give the property manager any wiggle room. If the tenant is unhappy, too bad. They signed the lease. If they paid a day after the grace period, immediately move to eviction.
“Best of Alternatives”: use the lease as a foundation, but be practical. You may be strict on the rent, but be more flexible on maintenance issues. Maybe the lease says that the tenant has to maintain the HVAC, but you tell the property manager that you are willing to pay for maintenance issues for tenants who are consistently paying rent on time.
I like option 2, but it does run the risk of getting out of hand if not closely monitored.
Property Maintenance
“Reliable but Basic Honda”: keep the property functioning well, but don’t try to fix and improve every possible issue.
“Top of the Line Mercedes”: keep everything looking and functioning perfectly. Cost is irrelevant.
“Car That Constantly Breaks Down”: do the bare minimum.
I operate my property as a “reliable but basic Honda” and use the “best of alternatives” approach to tenant issues.
Once you have set clear expectations with the property manager, you will want to decide how much discretion they should have.
How Much Discretion to Give Your Property Manager
When I talk about discretion, I am mainly referring to financial discretion. Spending money.
Your property manager will be making decisions daily that don’t cost any money. This is what you want. There is no point in paying someone to manage your property if they have to come to you for approval on every issue.
When it comes to financial issues, I recommend setting a dollar threshold under which the property manager has the discretion to resolve issues without coming to you for approval.
For example, you could set a threshold of $250. This could be per issue with a monthly cap or per month. This allows the property manager to resolve small issues without having to come to you each time for approval. It will save each of you time and will benefit tenant relations as issues can be solved real time.
Try a dollar threshold for a few months. If it works well and you develop an increasing level of trust with your property manager, consider increasing the threshold. If it is not working, consider reducing or eliminating the threshold.
Remember that you can change things over time.
Start with an approach, set a time period under which to try and evaluate it, and then make modifications if needed.
What To Do When Things Aren’t Working Out
All that being said, you can do everything to set yourself, the property manager, and the property up for success, but still have problems.
There will be times when things aren’t working out.
Welcome to being a real estate owner.
Here are some red flags to watch for relative to the performance of your property manager.
Poor Property Condition: the property is not being maintained to your agreed upon standards. You see this repeatedly in your property visits.
Non-Responsiveness: your property manager does not respond to your emails or calls. You may also hear from your tenants saying they are contacting you because the property manager is not responding to them.
Poor Treatment of Tenants or Vendors: in short, your property manager acts like a jerk.
Deadlines Consistently Missed: your property manager is responsive, but never hits agreed upon deadlines.
Sometimes these issues can be resolved with a conversation with your property manager (or your property manager’s boss). Sometimes they can’t.
When they can’t, it is time to make a change. Don’t settle for poor performance. You will lose tenants and spend more money maintaining your property in the long run.
Interview 2-3 new property management companies to find a better fit for you.
Closing Thoughts
Finding the right property manager is critical to your success as a real estate investor.
In the property I own directly with a partner, I experienced three of the four red flag issues above with the first property manager. I ended up firing them and finding a new one.
Everything has been SO much better since then. It was worth the time and the additional monthly expense.
Take the time to find the right team for you and your property.
Your time. Your money. Your choice.
Getting Meaning from Monthly Reports
Understanding income statements, rent rolls, A/R, and balance sheets
Let’s anchor in on where we are in the process of learning how to be a real estate investor.
You own your first property.
You have a business plan and are in the early stages of executing it.
You have hired a local property management and accounting firm.
You are eyes wide open that unexpected issues will come up.
Having a clear business plan relative to leasing and construction is probably the most important step you must take. We will get into the details of this in a future newsletter.
Today we are going to discuss how to interpret and get meaning from the monthly reporting package you will receive from your property management and accounting team.
I will define and discuss the individual reports that go into the reporting package:
Summary page
Rent Roll
Accounts Receivable (aka A/R)
Cash Flow and Income Statement with a Comparison to Budget
Balance Sheet
Construction Activity & Leasing Report
You do NOT need to have any accounting knowledge to understand these. All you need is patience, common sense, and a little guidance from Professor Bateman.
Let’s dig in.
Reporting Package Overview
Let’s start with the very basics.
What is a “reporting package” and where does it come from?
What: a reporting package is a collection of reports that help you understand how your property is performing.
When: it will likely be delivered to you within the first 10 days for the month and include activity for the previous month. Example: by May 10th you receive the report for April.
Format: it will be a pdf sent to you by the property manager.
The property manager’s accounting team will have prepared it according to the company’s accounting practices combined with the structure you (the client) have agreed upon. [Note: if you don’t have a property manager, you might have prepared it yourself or hired an accountant to do it.]
You don’t need to be an accountant to understand the reports, but it does help to have some foundational knowledge. Here are some basics.
Whenever there is financial activity at a property, the accountant records it in the general ledger. This could include:
Rent charged to or paid by the tenant.
A maintenance invoice received by or paid to a vendor.
Distributions made to investors.
And any other financial activity.
Think of the general ledger as a big excel file with (i) a date, (ii) a category ID, (iii) the amount, and (iv) comments.
Most reports are just a roll up of this activity, summarized in a specific way using the dates, category IDs, and amounts.
That’s about it. Yes, it is an oversimplification of the reporting process but it gives you an overview of how it works.
To be clear, it is way more complicated if you are doing the work, but as a reader of reports this should anchor you on the basics.
Now let’s discuss the individual reports within the reporting package. Your specific report may be different in order and content. Use the list below as an example only.
#1 - Summary Page
The summary page is just as it sounds: a summary. It will include highlights such as:
Property square feet and percent leased.
List of new or vacating tenants.
Amount of rent not paid (aka delinquent).
List of construction or maintenance projects.
Current cash, recent distributions, NOI and any other “snapshot” financial data.
There may be comments on some or all of these or it could just be a statement of the facts.
All of it will likely be in one page. It will help you understand the overall property performance before you read the individual reports.
#2 - Rent Roll
The rent roll is a summary of the leases and suites for your property.
Each accounting firm will create a slightly different version of a rent roll. Rent roll templates can also differ by asset class.
See below for an example of a rent roll for a three unit residential property.
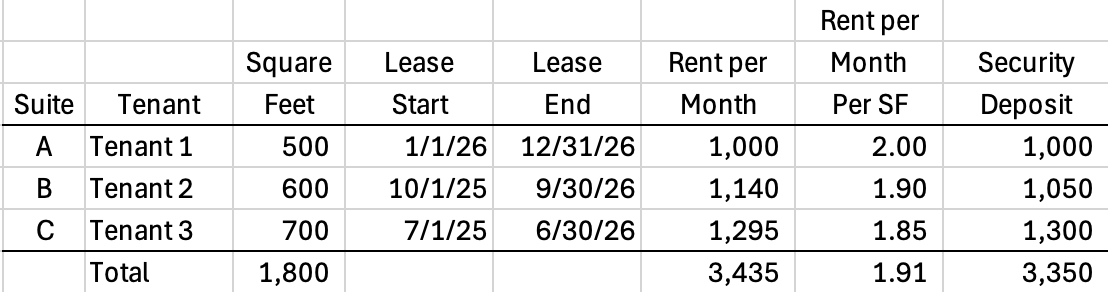
Example: Rent Roll of 1-4 Unit Residential Property
It gives you a way to see your tenants in a summarized report. If there was a vacant suite, it would be listed as vacant as shown in the example below.
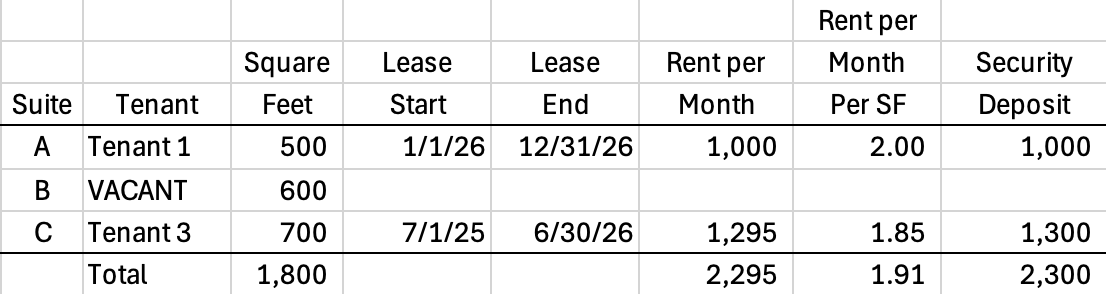
Example: Rent Roll of 1-4 Unit Residential Property - Including Vacant Suite
Important Note: never rely exclusively on your rent roll when making a decision about a specific tenant. In this case, you want to refer to the signed lease as there could have been a mistake made when the rent roll was prepared.
That being said, rent rolls are very useful to reference day to day.
Let’s move on to the A/R report.
#3 - Accounts Receivable (A/R)
Whereas a rent roll lists what each tenant is contractually required to pay each month, the A/R report will be your guide to what the tenant actually paid.
In the example above, Tenant 1 in suite A is supposed to pay $1,000 per month. If they did not pay that month, the A/R report would show this outstanding balance (aka delinquency).
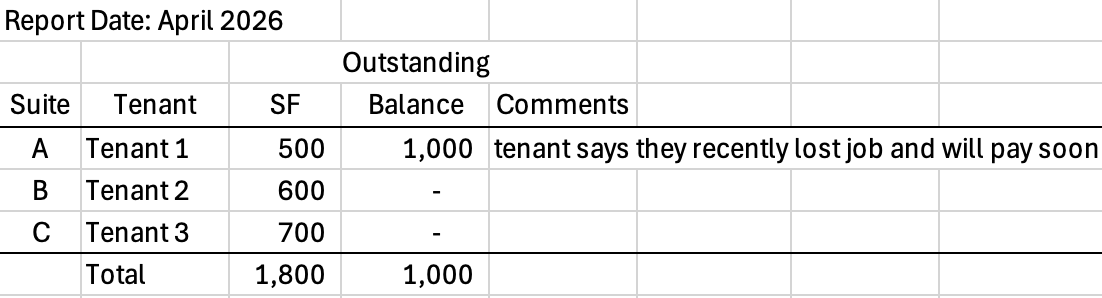
Example: A/R Report
The comments would have been added by the property manager who would have (hopefully) contacted the tenant to find out what was going on.
It is then your decision as the property owner to decide whether to allow the tenant some time to catch up on the rent or move to eviction.
Let’s move on to the overall property performance reports.
#4 - Cash Flow & Income Statement
Rent rolls and A/R reports are specific to revenue. The cash flow and income statement capture the revenue and expense activity that combine into the net operating income (NOI) and net income.
As an individual investor, I like to think of the cash flow and income statement as a single report.
But those of you who are accountants or in the real estate industry probably recognize that this is not always the case. Here’s how they differ:
An income statement is a summary of activity through NOI and inclusive of debt service, capital improvements (capex), leasing costs (tenant improvements and commissions) that totals in net income. It does not necessarily correlate to (a) the cash activity that occurred at the property that month nor (b) include a starting and ending cash balance.
This is because there are many, many accounting rules that indicate how reports should be prepared. They are anchored on logic that makes sense, but do not always result in helpful information for an individual investor.
Here’s what a cash flow and income statement might look like.
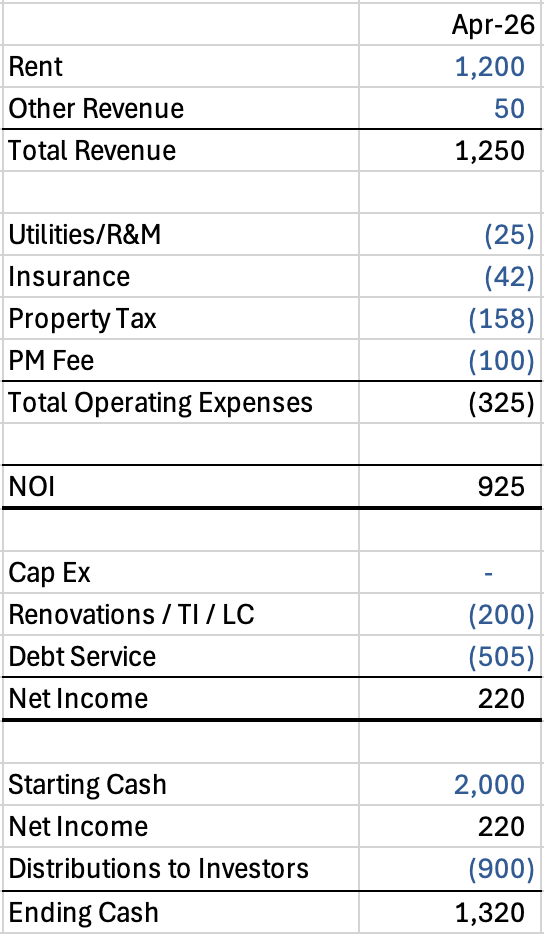
Example: Cash Flow & Income Statement
It looks like an income statement through “Net Income” but then adds comments on the starting and ending cash to give you an ending cash balance.
Cash is king. You always want to know how much cash you have.
A further variation on the income statement would be to include a “comparison to budget”. This would look like the example above with three extra columns:
The budgeted amounts for that month. The monthly budget would have been finalized at the end of the previous year - in this example, the end of 2025.
A comparison of the actual amounts to the budgeted amounts.
Comments on any significant variances to budget.
Now that you have a sense of a cash flow and income statement, let’s move on to the balance sheet.
#5 - Balance Sheet
A balance sheet is a snapshot of assets, liabilities, and equity.
Assets are things at the property that have value.
Liabilities are things the property owes to others.
Equity is the difference between the two.
It looks like this.
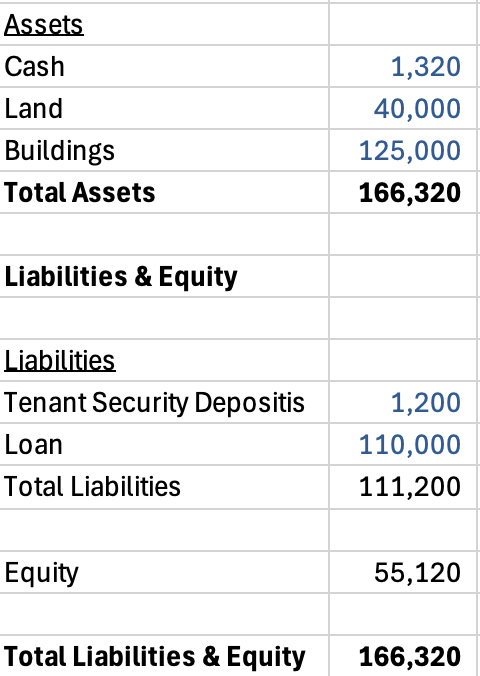
Example: Balance Sheet
The balance sheet is literal. It must “balance”.
Assets = Liabilities + Equity
Equity = Assets - Liabilities
Balance sheets are helpful to track your liabilities, but I don’t find them particularly useful in my day to day operations of a property.
#6 - Construction Activity & Leasing Report
These last two reports will vary in both who they come from and what they look like.
A construction activity report will likely come from the property manager. It will provide some level of detail on planned, in process, and completed construction activity. It will show things like (i) costs - both budgeted and actual, (ii) timeline - both budgeted and actual, (iii) a narrative on how the work is going.
This will likely be your most important report if you are in the middle of a renovation.
A leasing report will either come from your property manager (all residential properties) or your broker (all commercial properties). It will show leasing activity and lease comparables (aka lease comps).
Lease comps are completed leases at similar properties. They help give you a benchmark of what similar properties are leasing for in the same market. They help you determine what you should charge for rent for your property. We will get into this in a future newsletter.
So what is the takeaway on all these reports?
My Recommendations
Here’s how I use the reports.
For the deals in which I am a limited partner (LP) investor, I read the summary of the report with a focus on what is most important to me. If cash flow (aka investor distributions) is most important, I focus on that.
I recognize that as an LP (a) I have no control over day to day activity nor decision making and (b) I have invested as an LP so I don’t have to do any work. With this in mind, I don’t bother reading much beyond the summary page(s).
If you are an individual LP investor, you will “get what you get” relative to reports from the general partner (GP). Here are three examples of reports I get as an LP investor with three different GPs.
Monthly report an income statement and balance sheet, but with minimal narrative.
Quarterly report with detailed narrative and an income statement.
Annual letter with a narrative only. One page. No numbers.
This does not correlate to the property performance. It is just a choice that each GP has made as to how they want to communicate with their investors. As an LP, I have no ability to change this.
When I am investing by myself or with a partner, I take the opposite approach to reviewing the reporting package.
Not only do I read everything in the report, but I also have my own excel file of (i) monthly cash flow and income statement, (ii) rent roll, and (iii) capex report.
My excel based cash flow and income statement includes both historical and projected amounts per month with a running cash balance so I can project capital spending and investor distributions.
It is more work for me to enter the information from the reporting package pdf into excel each month, but it is well worth the effort as this makes sure I really understand the property financial performance.
A side benefit is that as long as the property manager gives me the information I need to enter into my excel file, I don’t care what format they deliver the reports to me in. They can use their standard templates.
Recognize that if you ask a property manager for customized reports that differ from their standard templates, it may be more work for them. This could mean more costs to you.
Make sure you agree on the content, timing, and frequency of the reporting package before you hire your property manager or accountant. I suggest starting by requesting an example reporting package and seeing if it has the content you need.
Red Flags to Watch For
As you review the reports, here are a list of things to be on the lookout for.
Increasing A/R: this indicates tenants are consistently paying late or not at all. Work with your property manager to come up with an action plan.
Actual Expenses Are Significantly (>10%) Over Budget: either your budget was too low or there are issues going on at the property. Discuss with your property manager.
Minimal Cash Balances: always leave a cash cushion for the unexpected.
Vacant Suites Staying Vacant for 3+ Months: work with your property manager or leasing broker. You may need to lower the asking rate or change brokerage teams.
Construction Delays and/or Cost Overruns: watch this closely and actively manage the team managing the jobs.
Pay attention and don’t be shy about calling your property manager to discuss in detail. Use your common sense and ask questions. Don’t be a jerk, but don’t be too passive.
Your Property, Your Choice
You can decide how you approach each investment.
It is your investment, your money, your time.
And you can always change your approach to report review over time. That is what I did.
How I approach it today is different than I did five years ago and will likely change five years from now.
That is learning and evolution. As my needs change, I adapt my approach to better meet my needs.
Don’t be intimidated by the jargon of real estate reports: income statements, rent rolls, and balance sheets.
Ask your property manager or accountant to explain them to you in simple terms. Take notes. Be a student.
After reading a month or two of reports, you will find they are key to extracting meaningful insight into how your investment is performing.
Daily Issues You Will Face While Owning Real Estate
From A/R to maintenance issues to finding tenants
Over the past three weeks we have covered real estate terms, getting organized, and developing your leadership skills.
Now we are going to get into the day to day issues you will face as a real estate investor.
Just as we did in the discussion on due diligence, we are going to use an income statement as our guide.
Revenue
Operating Expenses
Capital Improvements
Leasing Costs
Interest Costs (i.e. debt)
Other Issues Affecting Value
Almost everything you will be faced with could have an impact on the income statement. All other issues will have an impact on sale value and debt options.
I won’t overwhelm you with trying to give every detail of each issue. Think of this as a high level overview. We will dive into the specifics in the rest of the newsletters in this series on operating real estate.
Let’s dig in.
What is an “Issue”?
For this discussion, let’s define an issue as something that comes up that you have the power to take action on. That is not to say that there is a solution for everything, but most of the time there is something you can do.
But let’s make something very clear:
There are many things that will be outside of your control that will affect the performance of your property. Examples of these over the past 10 years include:
A global pandemic
Inflation that impacts both costs and interest rates
War
Political policies and changes in laws
That being said, there are many things within your control. You want to know what those are and what your options are. That is where this newsletter comes in.
Let’s start with revenue.
Revenue
As a reminder, revenue is made up of rent from tenants (and other income like parking) but is offset by vacancy and credit loss (i.e. tenants not paying rent).
Issue #1 - Tenants Not Paying Rent
You have leases in place but the tenants are not paying rent or are paying late.
Your Options: (i) do nothing; maybe you can live with the tenant paying late as long as they pay by the end of the month, (ii) same as previous but also charge a late fee, (iii) talk with the tenant to understand if this is a temporary issue; if so, work out a payment plan, or (iv) evict the tenant.
Future Discussion Newsletter: property management.
Issue #2 - Existing Tenants Causing Problems
Maybe they are loud or leaving trash in the common areas. They are doing something that disrupts others and/or damages the property.
Your Options: (i) do nothing; be a passive landlord, (ii) all bark, no bite - threaten to do something but never do it, or (iii) give the tenant a deadline to resolve the issue and then move to eviction if they don’t.
Future Discussion Newsletter: property management.
Issue #3 - No Tenant
To state the obvious, if you don’t have a tenant in one of your units you will not get rent. Said another way, this is vacancy at your property. It is like an airplane that takes off without a passenger in a seat. You will never get that rent back.
Your Options: (i) find a tenant by working with a motivated broker that knows the local market and/or (ii) expand an existing tenant.
Future Discussion Newsletter: leasing.
Issue #4 - Lease Rate
How aggressive do you want to be in setting your lease rates? Are you willing to give an existing tenant a lower lease rate than you would a new tenant?
Your Options: understand the market conditions and decide on an operational philosophy. Maybe you care more about steady cash flow than driving the rent as high as possible with periods of vacancy.
Future Discussion Newsletter: leasing.
Issue #5 - How a New Tenant Will Use the Space (Commercial Properties Only)
You may have a tenant ready to lease your space at a great lease rate, but you are concerned about how they will use the space. You could be worried they will be disruptive to other tenants and/or be hard on your property.
Your Options: talk with your broker and people your trust. Check with your insurance broker to see if it will affect your insurance rates. Consider a shorter term lease and put strong usage language in the lease.
Future Discussion Newsletter: leasing.
That should be enough to chew on for revenue. Let’s move on to operating expenses.
Operating Expenses
Operating expenses are made up of utilities, repairs and maintenance (“R&M”), insurance, property taxes, and property management fees (“PM Fee”). Some assets will have a more detailed list, but these are the major items.
Issue #6 - R&M: Costs vs. Quality
You will have a number of vendors performing services such as landscaping, pest control, HVAC maintenance, etc. You will need to analyze the trade-offs between frequency, quality, and price.
Your Options: develop your own operating philosophy. What kind of landlord do you want to be? Do you want to operate the property like a top of the line Mercedes, a reliable but basic Honda, or a car that constantly breaks down?
Future Discussion Newsletter: property management.
Issue #7 - Property Manager
This is a similar concept. What are you looking for in your property manager? How proactive do you want them to be? Are you willing to pay more for a property manager with a manageable workload, or do you want the cheapest that has an unrealistic number of other properties?
Your Options: same concept as R&M costs.
Future Discussion Newsletter: property management.
Issue #8 - Insurance
Insurance can get expensive. You will be faced with the choice of having broad coverage or minimal coverage. If you have a loan on the property, the lender will play an active role in determining your coverage requirements. Broad coverage is more expensive than minimal coverage and unfortunately there is no “right” answer to the amount of coverage to have. Additionally, you may have to file an insurance claim at some point.
Your Options: (i) understand your tolerance for risk and (ii) dive in deep and early when you have an insurance claim by actively engaging with your insurance broker and/or claims adjuster.
Future Discussion Newsletter: insurance and property taxes.
Let’s move on to the “below the NOI” line items. Reminder: NOI = Revenue minus Operating Expenses.
Capital Improvements (aka Capex)
Issue #9 - Repair or Replace
Things are going to break and deteriorate. That is the reality of owning a property. It might be the HVAC unit, a dishwasher, or a section of the roof. As the landlord, you may need to address this under the terms of the lease.
Your Options: (i) read the lease to determine who is responsible for the issue - landlord or tenant, (ii) review the age of the system - example: if the HVAC unit is 20+ years old, a replacement may make more sense than a repair, (iii) price out both the repair and the replacement, and (iv) get opinions from multiple vendors.
Future Discussion Newsletter: construction.
Issue #10 - Replacement Quality
This is the same concept as R&M vendors and property managers. How high a quality system and work do you want for your property. Are you OK with the cheapest lighting, HVAC, and quality of work that won’t last as long but is less expensive? Or are you willing to pay more for high quality systems and work that will last longer term?
Your Options: (i) develop your own operating philosophy, (ii) be eyes wide open on the trade-offs and the reality of your cash position, and (iii) get multiple bids for the work and talk with the contractors about their work before you sign a contract.
Future Discussion Newsletter: construction.
Leasing Costs: Tenant Improvements (“TI’s”) and Broker Commissions
Issue #11 - Your TI Budget
How much are you willing to spend for the right tenant? What is the reality of your cash situation? Although TI’s are mainly applicable to commercial properties, the same concept applies to residential relative to how much you want to improve the unit for a prospective tenant.
Your Options: (i) develop your own operating philosophy, (ii) be careful of tenants that want specialized TI’s that are unlikely to be re-used by a future tenant, or (iii) try to push the cost of the TI’s onto the tenant in exchange for free rent and/or a lower lease rate.
Future Discussion Newsletter: leasing.
Issue #12 - Leasing Commissions (Commercial Properties)
Brokers play a very active role in leasing commercial properties. Commissions can get expensive and need to be paid at the time the lease is signed (i.e. upfront). This can squeeze you on cash at a time your revenue is down because you have a vacant suite.
Your Options: (i) build up cash prior to a potential vacancy and (ii) understand the time commitment and risks of not using a broker.
Future Discussion Newsletter: leasing.
Let’s move on to debt.
Interest Costs, Debt, and Other Lender Issues
Issue #13 - Rising Interest Costs
You may be tempted by the low interest rate that come with a floating rate, adjustable loan. But if interests rates go up, your monthly interest costs could double. Yikes!
Your Options: there may not be any options if your interest costs go up. This could wipe out your cash flow and/or put you in a situation where you can’t make debt service. Be very careful of floating rate debt. This adds a significant amount of uncontrollable risk.
Future Discussion Newsletter: investor and lender issues.
Issue #14 - Lender Approvals
As discussed in Debt: An Amazing Tool with Strings Attached, your lender may have approval rights on a number of issues and not allow you to do what you believe is best for the property.
Your Options: (i) read and understand the loan documents so you know your rights, (ii) develop a positive working relationship with your lender from day one and be reasonable; this will pay dividends in the future, and (iii) make the case for why you want to do what you want to do.
Future Discussion Newsletter: investor and lender issues.
And finally, let’s quickly address “other issues”.
Other Issues Affecting Value
There are some issues that may not affect your cash flow during ownership, but will be problems when you go to sell or refinance the property. These could include:
Environmental issues
Zoning changes
Challenging neighbors
Challenging tenants
Your Options: (i) conduct annual property reviews to identify issues early, (ii) maintain good relationships with city officials and neighbors, (iii) address problems immediately rather than letting them compound, and (iv) document everything in case issues arise during sale.
The key is to be eyes wide open on the risk to your future sale and/or refinance and then try to resolve the issues as best as you can before you are in the time crunch of a sale or refinance.
That’s the list of 15 or so issues. Are these all the possible issues you will face?
No, but they give you a sense of the type of issues you will face.
What are our key takeaways?
Key Takeaways
Here’s what you need to keep in mind:
Develop your own operating philosophy. Combine this with your niche, and you will have a clear foundation on which you evaluate your decisions. Without a philosophy, you will find yourself over analyzing each decision and not having any consistent approach.
Issues that you need to figure out will come up. Methodically break them down into parts. Do the research. Talk to experts. And then make a decision.
Not all issues are equal. Cash flow problems (non-paying tenants, rising interest costs) demand immediate attention. Quality decisions (Mercedes vs Honda) can be determined over time.
There will be unexpected costs. Keep a cash cushion. Don’t distribute every last dollar.
Life is full of challenges. Think of all the ones you have overcome in your life just to be able to be sitting here reading this newsletter.
Operating real estate is a lot more complicated than owning stock.
It can be time consuming and stressful. There is no sugarcoating it.
If you don’t want this in your life but you still want to be a real estate investor, there is alway the option to invest as an LP and have the GP do all the work (for a fee).
But for those of you willing to do the work, it can be financially lucrative and intellectually rewarding.
You can do it.
Developing Your Leadership Skills
The power of reading non-fiction and creating a reading journal
Reading non-fiction has made me a better leader.
No question. No debate.
I have learned so much through the reading process, not just about other subjects, but also about myself.
Last week we talked about getting organized. Soon we will be moving on to all the things that will come with operating your property: (i) proactively executing your business plan, (ii) reacting to issues, and (iii) leading others to accomplish your goals.
You need to develop your own tools to do these well. Not just the specifics of real estate, but also the fundamental leadership skills needed for these functions in anydomain.
That is why this week we will talk about reading as a foundational practice to understand yourself and develop your leadership skills.
We will cover three topics:
The list of some of my favorite books that talk about key skills to develop.
How to remember what you read by creating your own reading journal.
The most important skills all leaders need.
Let’s dig in.
Why Non-Fiction
Fiction is tons of fun, but non-fiction helps me grow.
It makes me a better leader, investor, employee, and professor.
It makes me a better person.
It expands my perspective and helps me think.
Non-fiction books are also an insane bargain. For less than $20 (or free at the library) you get a comprehensive presentation of someone's deep research into a subject.
That person put 100's of hours into creating it.
An editor read many drafts to perfect the organization and main points.
All of this is then there for anyone to buy for less than $20. What a deal!
So here’s a list of books I recommend to make you a better leader, not only of your properties, but also of your life and everything else you do.
Recommended Reading List
Understanding Yourself: if you don’t understand yourself, you will limit your growth.
Emotional Intelligence 2.0 by Travis Bradberry and Jean Greaves: probably one of the most foundational discussions of not only how to understand emotional intelligence (aka EQ), but also how to develop it. Emotional intelligence is critical to working with others.
Mindset by Carol Dweck: one of the most influential psychology books of the last decade. Do you have a fixed or growth mindset? Read this book to understand the importance of a growth mindset and how to develop one. It may change your entire perspective on life.
Grit by Angela Duckworth: understand the need for consistency of effort over the long run to achieve your goals.
Quit by Annie Duke: Duke is both a university professor and former world poker champion. She discusses our bias against quitting and shows you the formula for when you should quit.
Clear Thinking by Shane Parrish: a guidebook on how to make better decisions.
Your Career & Leadership: read to help guide your career and become a leader.
Legacy by James Kerr: short lessons on leadership based on the legendary New Zealand national rugby team. I think I have read this four times.
The Wisdom of Andrew Carnegie as told by Napoleon Hill: this was the precursor to Think and Grow Rich. It is an interview with Andrew Carnegie full of his principles for a successful life. These lessons from 1908 still hold true today.
The Infinite Game by Simon Sinek: a discussion on a more grounded form of leadership that yields better results.
Atomic Habits by James Clear: the incredibly popular book on the importance of habits and how to develop them. Over 25 million copies sold. Read it. Live it.
Money and Investing: these will help you think about investing at a more foundational level than just real estate.
What to Make of a Life by Jim Collins: helps you understand the power of what happens when you find the things you are naturally good at.
The Psychology of Money and The Art of Spending Money both by Morgan Housel: these books help you understand the major role that psychology plays in influencing all of our decisions about money.
The Simple Path to Wealth by J.L. Collins: this guy is the master of helping you understand the stock market and its importance as a passive vehicle for wealth creation. He also explains what IRAs, 401Ks, and 529 plans are.
The Algebra of Wealth by Scott Galloway: wealth = focus + (stoicism x time x diversification).
The Five Types of Wealth by Sahid Bloom: helps you think beyond wealth as being limited only to money.
Living a Good Life: making money is a way earn your freedom, but it is a pointless exercise if you don’t live a good life.
Transitions by William Bridges: explains the three steps we go through when making transitions in life.
30 Lessons for Living by Karl Pillner: based on interviews with people in their 70s, 80s, and 90s. A great way to learn from those that have “been there, done that” in the journey of life.
The Daily Stoic by Ryan Holiday: I read this every morning. One page per day. I can’t speak highly enough about stoicism. It is the 2000+ year old philosophy that is anchored on the concept of distinguishing between what you can and cannot control. Don’t waste your time getting emotional on what you cannot control. All of Holiday’s seven+ books on stoicism are outstanding.
That’s my curated list of 15+ favorites from the 50+ non-fiction books I have read in the last five years.
Now what?
Let’s say you choose to read some or all of these books. Pick one that looks interesting. Create a dedicated 20-60 minute uninterrupted block to start reading. Keep going if it interests you. Move on to another book if it doesn’t.
Remember, I didn’t magically read all of these at once. I found one that was interesting (Atomic Habits) and kept following my curiosity.
The list I am sharing here is a manifestation of the power of compounding in action.
I have found that 10-12 books per year is my pace. I tend to go through spurts, reading three books in six weeks and then not reading anything for a month or two. Find your own rhythm but make reading a priority.
Ideally, you want to retain the key learnings from each of these books to be able to refer back to them when you feel the need. This is what we will talk about next.
Remember What You Read: Create Your Own Reading Journal
I used to mainly listen to non-fiction books via audio. I enjoyed listening while on a hike or during a car ride. It was super convenient.
The downside to this convenience was that I often forgot the lessons of the book months later.
Then I heard about the concept of a commonplace library: the idea of writing down the key points or quotes of a book in a centralized place (ex. notecards by subject or a reading journal).
This required me to restructure the way I read.
I moved to a kindle so I could highlight as I go. Highlighting is key to be able to go back and reference the important parts of the book.
I bought a Moleskin journal that is dedicated to summaries of the books I read. One to two pages of notes per book. Here are the specific steps:
Read the book in any format that allows you to highlight specific passages.
Once you finish the book, set it aside for a week or so.
Come back to the book with fresh eyes to go through the highlighted sections. Summarize the key concepts in your dedicated journal. I don’t bother with quotes or putting in everything I highlighted. I just want to capture the key concepts. I like being limited to 1-2 pages of notes.
I now have a journal full of knowledge that I can refer back to. It is one of my favorite possessions. These pictures will give you a better sense of it.
Note: if you absolutely have to listen on audio, consider carrying around a notebook to take notes as you go.
Image 1: My Moleskin Journal Dedicated to Reading Summaries
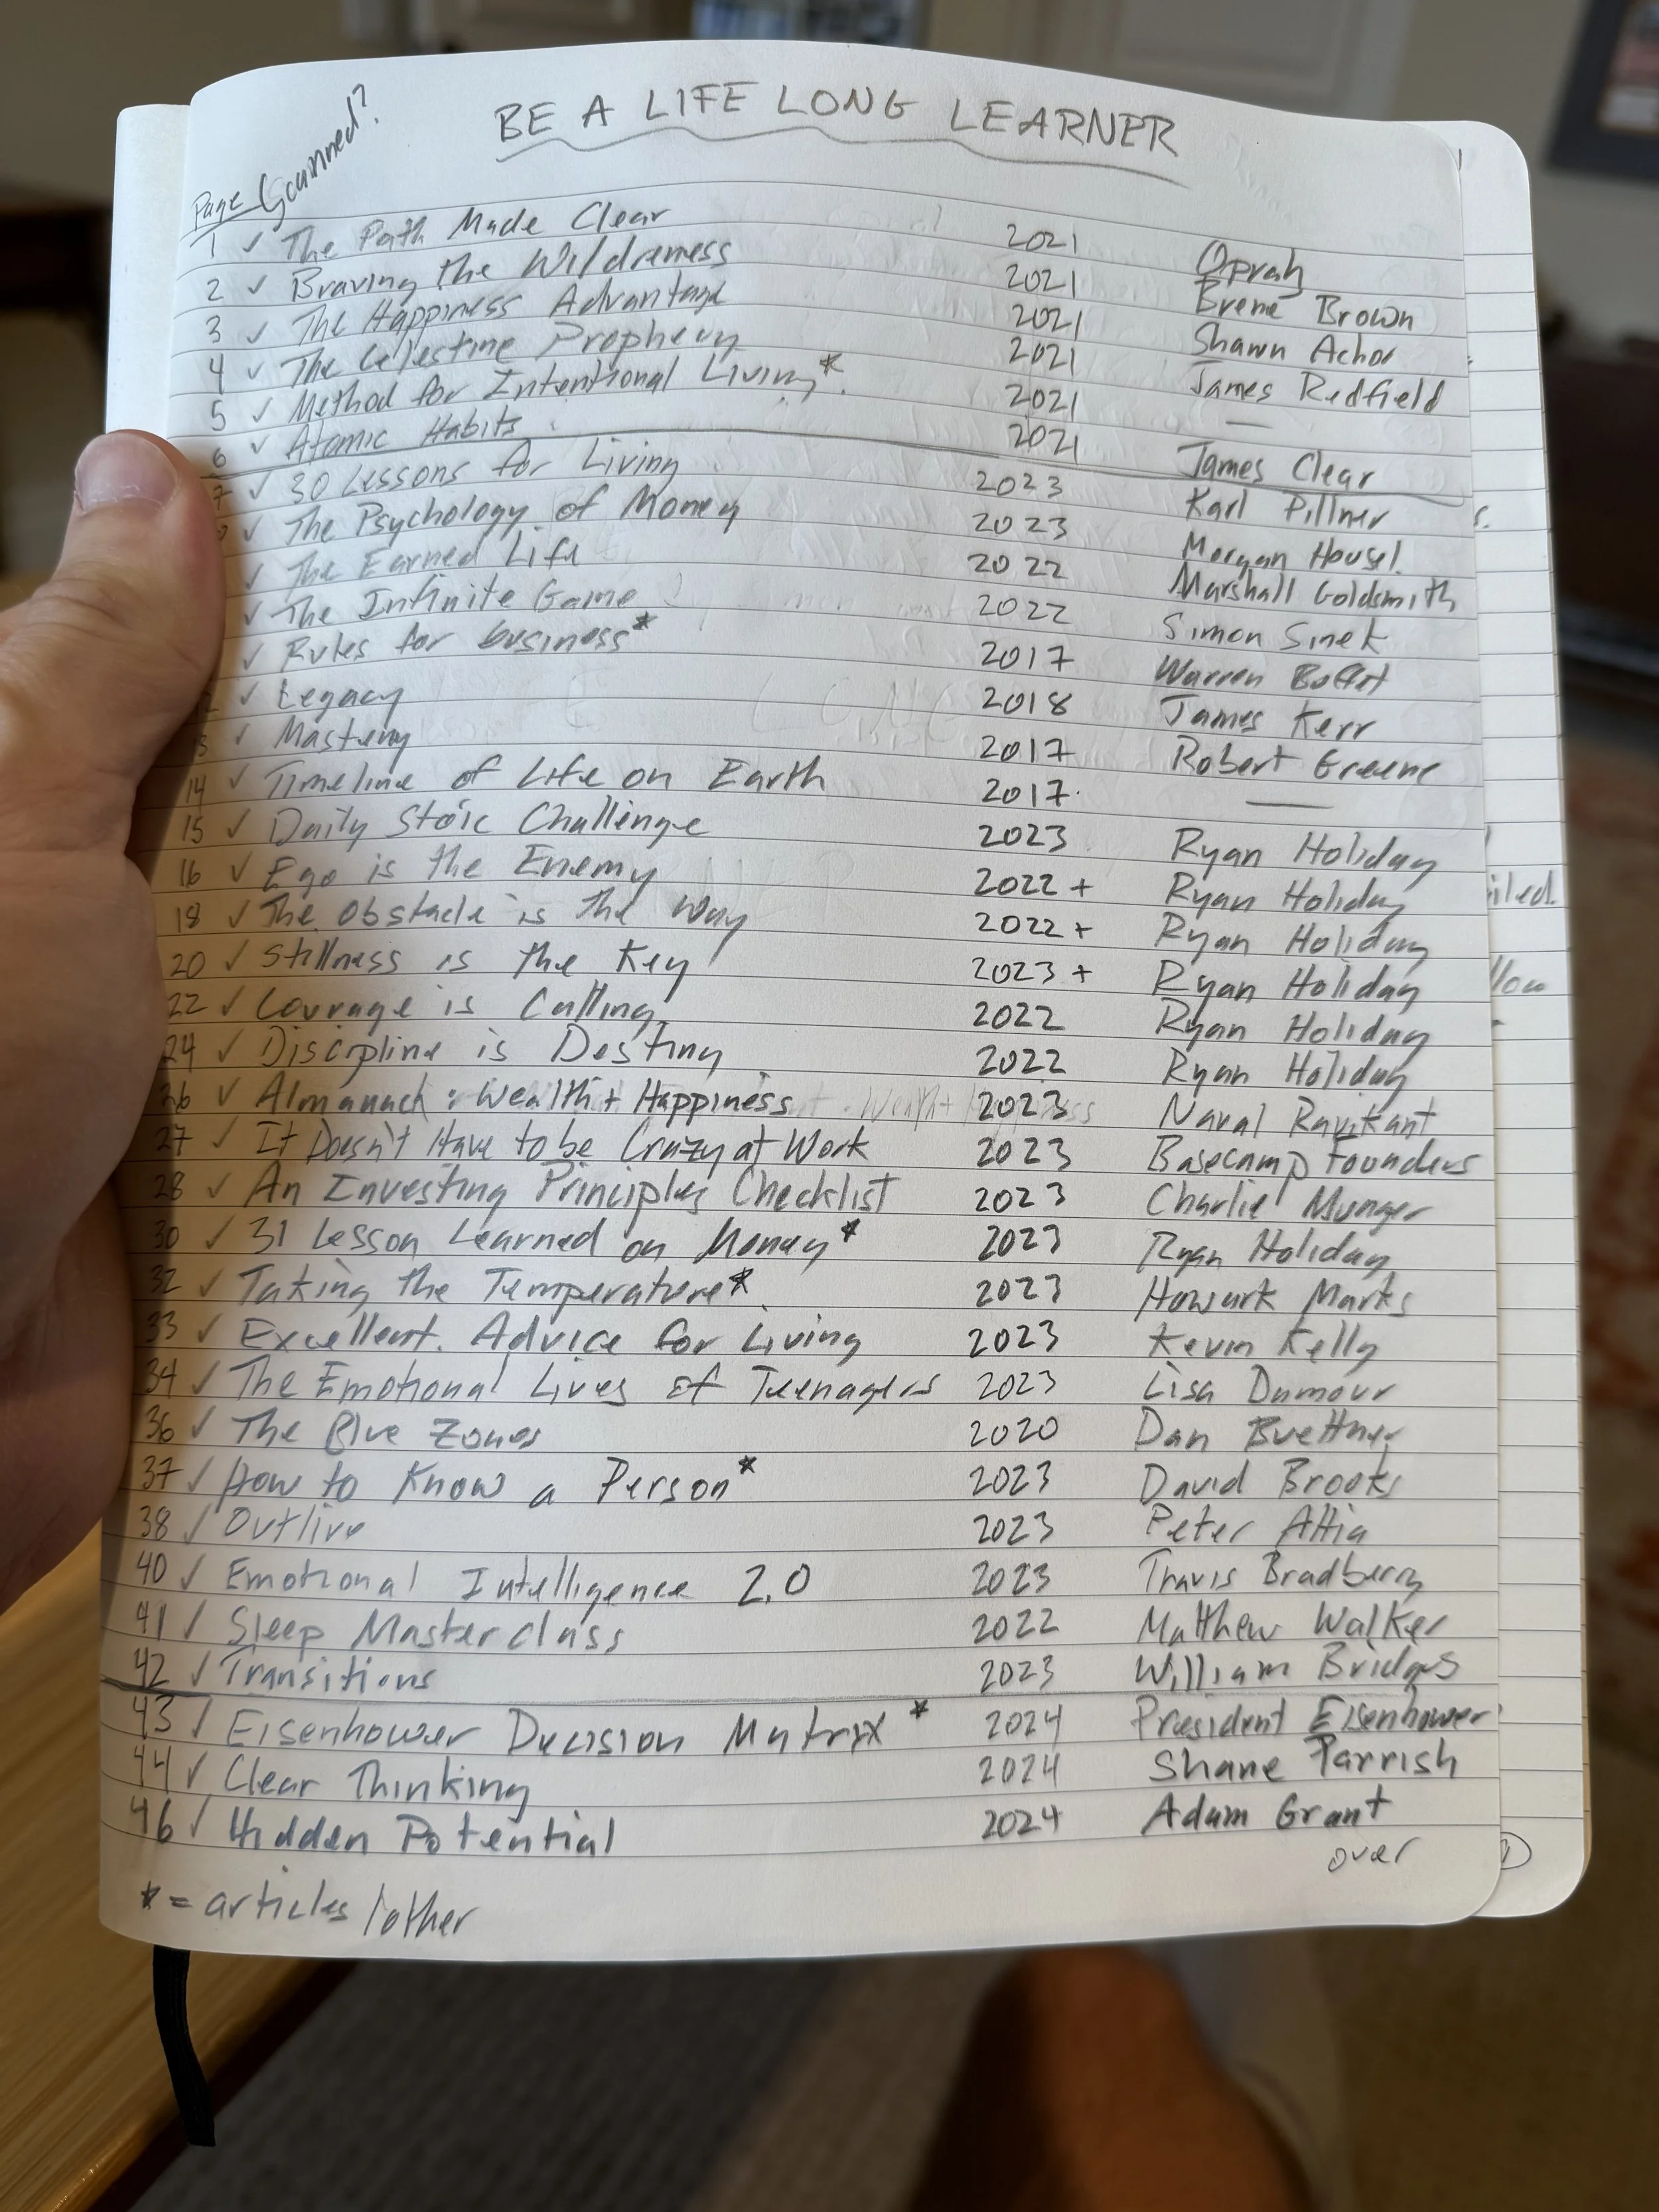
Image 2: The Table of Contents
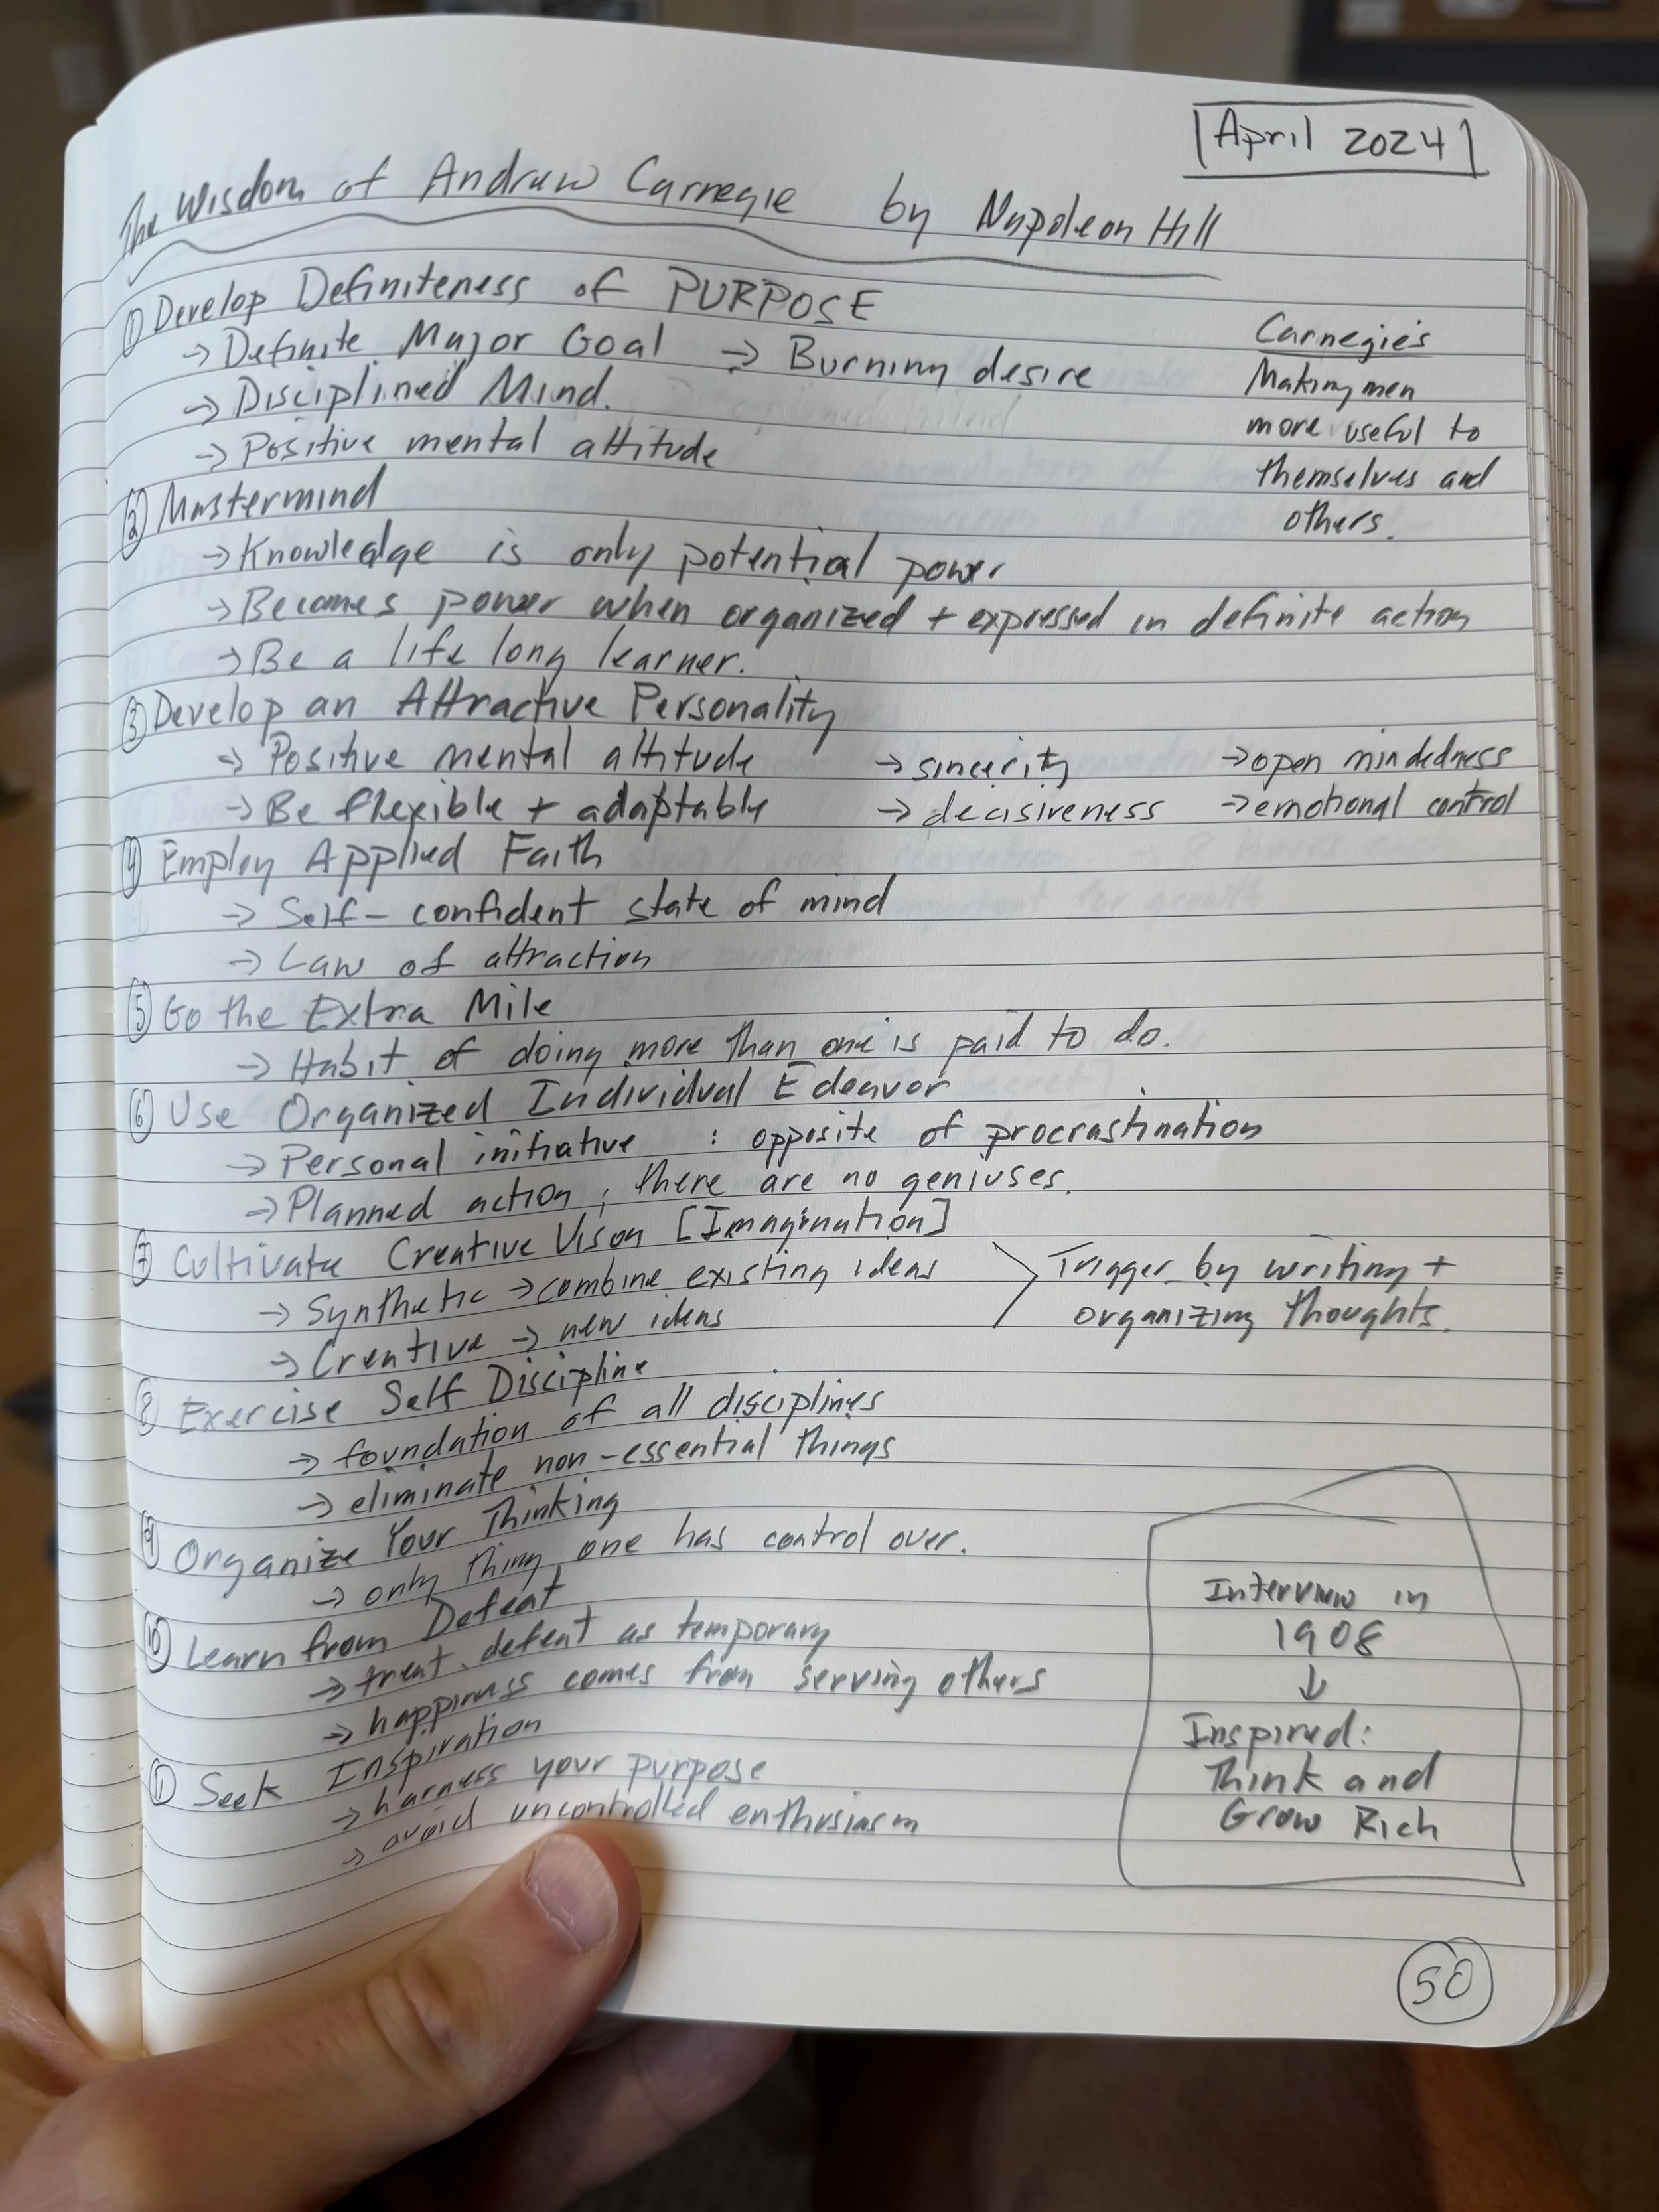
Image 3: An Example of a Book Summary
Anytime I am making a big decision or think of something that I have read and want to re-visit, I turn to my reading journal.
So what have I learned about leadership through reading and becoming a leader at work?
Important Leadership Skills
Be Clear on What You Want: get priorities correct so as to spend time on the correct things.
Measure Success: figure out how to measure whether you are achieving your goals. Measure what matters. Results will follow
Be Driven & Humble: this is the magic combination. Recognize you can always learn from others. You don’t want to be the smartest person in the room.
Give credit to others. Take the blame for mistakes.
Embody the leadership skills you admire. People will watch what you do more than what you say.
Build and Rely on Your Team: don’t do everything yourself. Assemble a team of people that are good at specific areas. Trust them and give them room to do things their own way. Don’t micromanage them.
Respect Differences: other people’s ways may be different from your own. It is results that count, not the methods.
Be Prepared: for meetings and discussions. This means doing the reading and research in advance and expecting the same from others.
Create Focus Time: progress happens in dedicated blocks of time, not in endless meeting and emails. Set aside regular blocks of 90-120 minutes to actually think and do work.
Take a Walk: my best ideas come from my hikes and bikes in nature. Get out of the office to think. Walking 1:1 meetings can be great too.
Be Curious: ask lots of questions. Always be learning.
Create Relationships: the team you work with are not robots. They are people with feelings. Build up your “relationship bank” with others so that you can “draw” from it when you need to have challenging conversations. You need to establish trust before you can work through conflict.
Don’t Be a Jerk: this should be obvious, but some people still behave poorly. Everyone is dealing with something challenging outside (or sometimes inside) the office. Be kind. Be helpful. Give people the benefit of the doubt.
Leaders make decisions with or without perfect information.
Reading and Leadership
Readers are leaders.
For me, much of growth and leadership is integrating information from different areas and applying them to the situation at hand.
Reading is foundational to this.
Read. Read. And then read some more.
It will make you a better investor, leader, and person.
Getting Organized for Success
Building a foundation of property information so you can focus on adding value
You are on the path to becoming a real estate investor.
You will identity your niche, study a market, find a property, and go through the acquisition process to closing. At that point you will be a real estate investor.
Then what?
How do you set yourself up for success?
The key is to build a foundation of information based on everything your learned during the acquisition and due diligence process. Half a day of organizing information could save you 100’s of hours of searching for what you need during your ownership of the property.
More importantly, it will help you stay on track with your business plan and make better decisions.
I have found there are four ways to organize and access your property information. I like to use all four, but everyone’s brain works differently. Develop the method that works best for you.
Digital folder of documents.
Photo library.
Master excel and site plan files.
Physical notebook of most important / current information.
I will walk you through all four so that you can (a) see an example of each approach and (b) adapt them to what works for you.
Let’s dig in.
Why Take the Time to Organize the Property Information?
As discussed in Due Diligence: Your Property Investigation Checklist, you will spend significant time creating a detailed understanding of the property. You will review the Offering Memorandum (OM), develop your own financial analysis and business plan, review various reports, and get to know the market.
In short, you became an expert on the property at that moment of time.
Don’t let this knowledge waste away!!
Take the time to organize and summarize it in a way you can easily reference when you need it.
I highly recommend you do this within the first week of owning the property. The acquisition information will be fresh in your mind. Block out 4-6 hours on your calendar. Go somewhere without distractions. Organize everything at once.
If you already own a property without a system, it is not too late. Start now.
Let’s get into the details of the system by starting with the documents.
Creating Your Digital Folder of Documents
Almost everything you review and receive will be digital. You may print some of the information, but it will have likely been created in digital format.
Your task is to organize it into a logical folder system that you can reference (and add to) in the multiple years you will own the property.
Here’s a property folder structure that works for me:
01-Business Plan:
Documents: business plan, underwriting model (financial analysis/projection).
02-Acquisition
Documents: OM, due diligence reports, closing documents, title policy.
03-Legal Ownership
Documents: LLC or other legal ownership entity, grant deed.
04-Loan
Documents: loan documents as discussed in Debt: An Amazing Tool with Strings Attached.
05-Equity (if you have outside investors or a partner)
Documents: partnership/JV agreement, investor communication.
06-Plans & Pics
Documents: site plans, floor plans, ALTA survey, pictures.
07-Leases
Documents: leases, form lease agreement (i.e. your standard lease template), lease proposals.
08-Marketing
Documents: broker listing agreement, marketing materials, marketing reports.
09-CapEx & R&M
Documents: folder for each job with proposal, contract, invoices, costs, etc.
10-Income Statements
Documents: Financial reports organized by date for ease of reference.
11-Property Management
Documents: Property management agreement, tenant correspondence.
12-Insurance
Documents: insurance policy and certificates, folder for each claim (if any), insurance broker related documents.
13-Property Tax
Documents: property tax bills organized by date, property tax appeal info (if any).
14-Appraisals & Sale Comps
Documents: all appraisals organized by date, any relevant sale comparables.
15-Zoning City
Documents: zoning report / information, parking counts, city correspondence.
You can do this in dropbox, iCloud, your c-drive…it really doesn’t matter what format you use. However, I strongly encourage you to use something that (a) is backed up to the cloud and (b) can be accessed from multiple devices including your phone. Example tools:
Cloud storage: Dropbox, Google Drive, iCloud, OneDrive.
Note-taking: Evernote, Notion, OneNote (for digital notebook alternative).
Spreadsheet: Excel, Google Sheets.
Photo organization: Google Photos, iCloud Photos.
Important note: Your property documents likely contain sensitive information (financial details, tenant data, legal agreements). Ensure your cloud storage has strong password protection and two-factor authentication.
You will be referencing and adding to documents all the time. This structure gives you a place for everything. As you buy more properties, mirror the folder structure so it is easy to navigate from property to property.
Let’s move on to pictures.
Photo Library
Photos are critical to help you make decisions from afar. Even if you live in the same city as the property, it is helpful to be able to get a visual of what you are focusing on - anywhere, anytime.
Enter your phone.
Here are the steps I recommend.
Take pictures from every corner of the property, both exterior and interior.
Put the pictures in a dedicated photo folder on your phone.
If you want to go to the next level, organize and label these photos in a powerpoint or other digital file. Example: you might label one as “view from northwest corner”.
These photos will be so helpful to you as you operate the property day to day. Not only will it reinforce your property knowledge as you build the photo library, but it will also save you many avoidable trips to the property. You can use your time to focus on making good decisions.
Let’s move on to the two critical documents you should create.
Document #1: Master Excel File
Even if you are not a “numbers” person, I encourage you to create a master excel file. I like to name mine “[Property Name]-Key Info-[year].xlsx”. At the end of each year I create a new one and archive the old one.
Here’s what is in the excel file. Each bullet represents a separate sheet.
Notebook Cover: we will get into this later.
Cash Flow: a monthly cash flow that includes the property performance and a running cash balance so I know what distributions I can make. Here’s my update protocol:
Monthly: update current month information based on report prepared by the property manager.
Quarterly: when making investor distributions.
As Needed: when forecasting future capex and leasing assumptions.
Rent Roll: list of units / suites at a property with information on square footage, tenants, rent, lease start, lease end, and many other pieces of information. I update the rent roll when a lease is signed or modified.
Vendors: list of contact information for vendors I use for the property. Put the ones you use most regularly in your contacts on your phone.
Property Tax: list of property tax billing details by year.
This is the file I go into the most for my property.
Let’s move on to the second critical document.
Document #2: Site Plan
Having an aerial view of the property will be very helpful. This can be as simple as a snapshot from Google Maps (aerial view) with labels of key information. Here’s a screenshot of one I made in powerpoint.
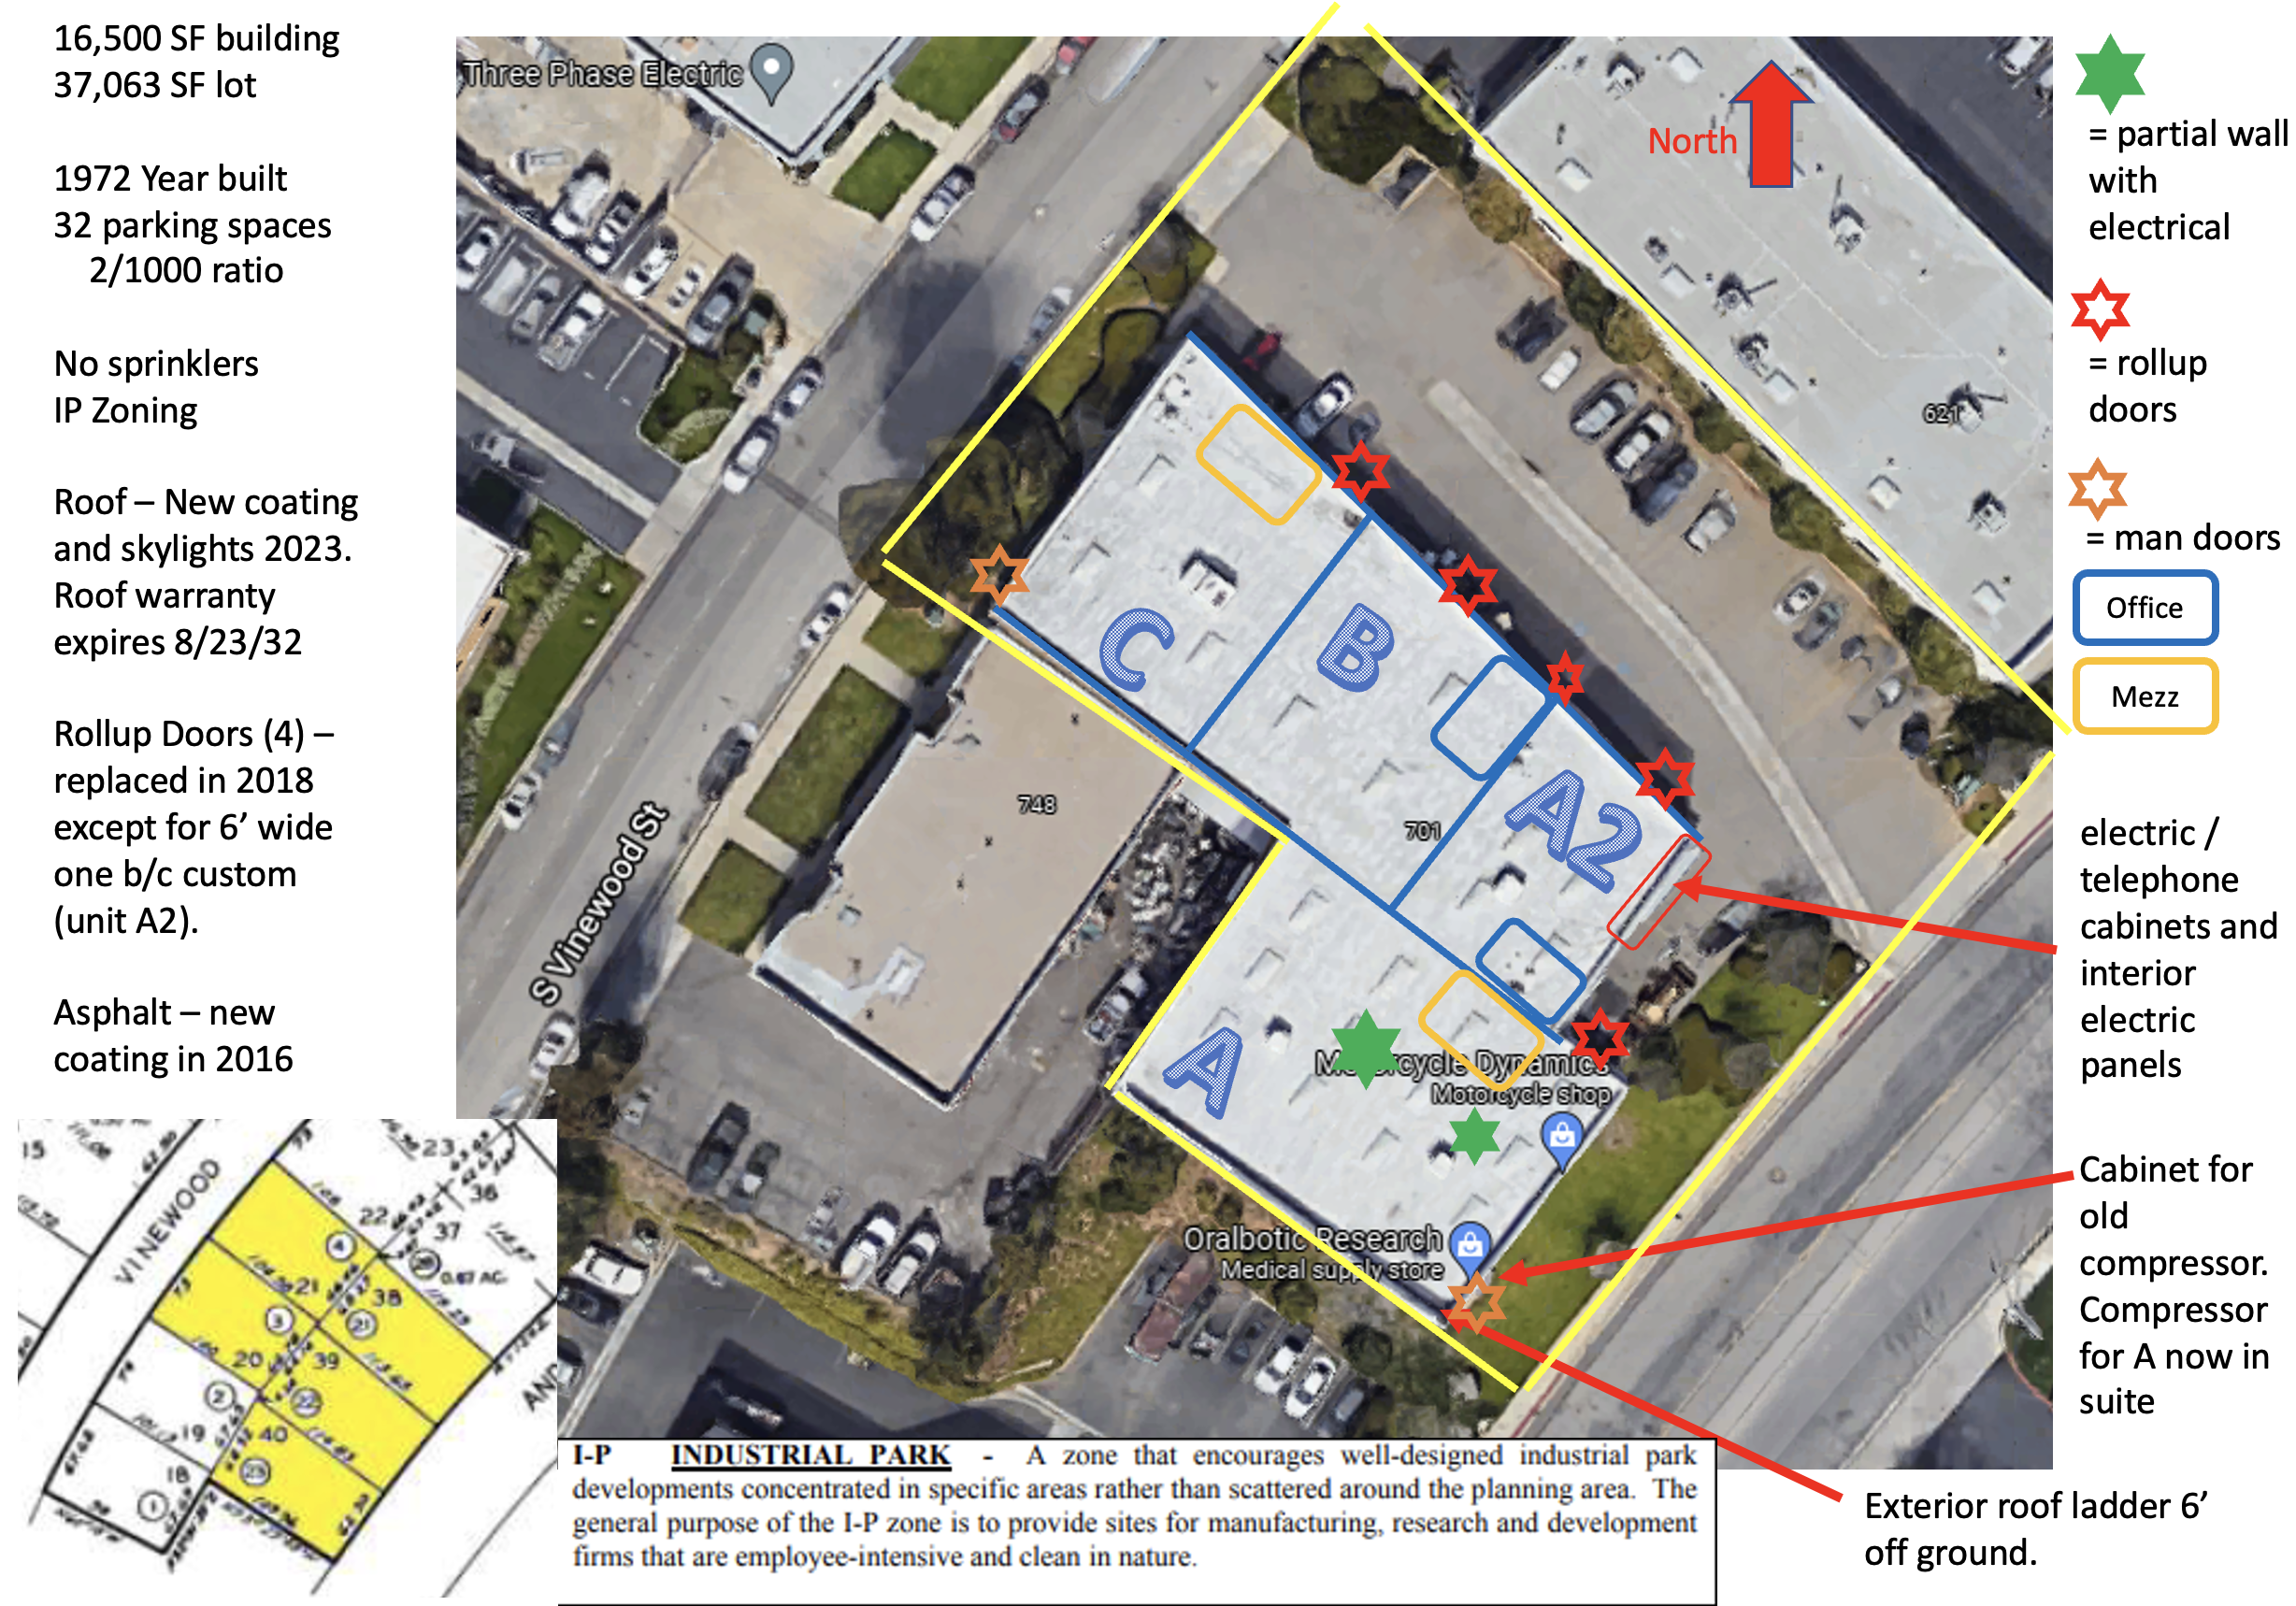
Image: Example Site Plan with Notes
I am not looking for perfection on this. I am looking for something that I can reference easily.
Now let’s move on to what I believe is the most critical piece: your property notebook.
Your Property Notebook
A notebook you say? Why can’t it all be digital?
You can go digital only, but I don’t recommend it.
Having spent 25+ years organizing property and other information, I believe having a single purpose notebook sets you up for success.
A “single purpose notebook” is just as it sounds. One notebook. One purpose.
In this case the “purpose” is your property. Once you own a portfolio of properties, you will probably want to expand and restructure it to include the whole portfolio but for now let’s stick with one property.
You can do this with a three-ring binder, but I really like the Circa system by Levenger. It is like a spiral bound notebook that you can have blank sheets of paper for note taking but also add print outs of digital files. The key is to have multiple divider tabs for the areas of the business you focus on regularly.
Here’s the structure I use for a property:
Cover Page: this is the “Notebook Cover” sheet from the master excel file. It is my working page of the most important information about the property. It includes:
Financial Snapshot: an abbreviated cash flow that includes eight lines - revenue, operating expenses, NOI, capex, leasing costs, debt service, net income, investor distributions. I have one column for previous year and one for current year.
Capex: list of the major building systems with anticipated (or most recent) replacement year and comments. These could include roof, exterior painting, asphalt, and any other part of the building I am focused on.
Loan Info: loan amount, interest rate, loan expiration date, and any operational items the lender needs to approve (see Debt: An Amazing Tool with Strings Attached for a refresher).
Key Initiatives: this is the most important. What am I planning to do to add value the property? It should include what, when, and the anticipated cost.
Action Items: this is a blank area I handwrite in as needed. I like a pencil so I can add and erase as I get things done. Example: call broker about leasing status or get bids to replace the roof.
Waiting: same concept as “action items” but to keep track of what someone else said they would do for my property. Example: broker - update on tenant prospect or PM - update on electrical repair.
Tab #1: Notes: blank pages I can take note on while talking to someone or working through an issue.
Tab #2: Projects: key documents related to value add or other projects I am working on. For example, it might include a rendering and cost estimate of an exterior renovation.
Tab #3: Leasing: any leasing and marketing activity. It might include the leasing brochure, market reports, and notes on potential tenants.
Tab #4: PM: this is a separate section for the key vendor list and any ongoing issues I am working with the property management team on.
Tab #5: Building: this is where I put the site plan and other important building information in.
Tabs 2-5 change over time depending on what I am working on. When I was replacing the roof and skylights, I had a dedicated tab for this. Once complete, I repurpose the tab.
The most important aspects of the notebook system are:
I have a portable system I can take with me to the property, office, home, anywhere.
I have one place that I take notes and reference key property information.
It is dynamic. The structure changes with my changing focus areas.
It is a visual reminder that I need to stay focused on the property.
So what do you do with these techniques?
Making Them Your Own
The key to any organizational system is to make it your own.
Do you like to have a folder for every item? Then make a detailed folder system.
Are you a minimalist? Then have a minimal number of folders.
Are you an iPad only person? Then create a system that leverages your iPad.
It doesn’t matter how you do it. What matters is that you use a system.
Don’t wing it by trying to remember everything.
This system works for me. In a year I will have probably modified it a bit.
Find a system that works for you and make it happen. You will be making property decisions all the time. You want the information at your fingertips.
This is why having a system is so important.
New Series Kickoff: Owning & Managing Real Estate
Starting with your complete glossary of real estate terms, from AM to WALT
We have covered a lot so far. I like to think of it as three main subject areas:
Introduction to Real Estate Investing
Investment Fundamentals
The Acquisition Process
Today kicks off the next series of topics:
Owning and Managing Real Estate
We will be covering the following over the coming weeks:
Understanding the terms (aka the jargon and acronyms)
Getting organized for success
Developing your leadership skills
Day to day activities
Reading reports
Property management and accounting
Contracts 101: what’s in a vendor service agreement
Insurance and property taxes
Leasing
Contracts 101: what’s in a broker listing agreement
Contracts 101: what’s in a lease agreement
Construction
Contracts 101: what’s in a construction agreement
Investor and lender issues
Ways to add value to your property
Executing your business plan
What to do next
My core background is in real estate operations. It is a dynamic and exciting aspect of the business, filled with both opportunities and challenges.
I will be your step-by-step guide.
This week we will focus on understanding the terms specific to real estate.
Think of this as your real estate glossary.
So grab your favorite beverage.
Sit back and relax.
Let’s dig in.
Why Are There Commercial Real Estate Specific Terms?
Those of you that have worked in various industries, or even followed a particular sport, know that each domain develops their own acronyms and jargon. This is because:
It is often more efficient to use an acronym.
Each domain has its own unique specifics.
Commercial real estate is no exception.
If you work for a company, you will even find that each company has their own additional layer of terms.
Don't worry. You will figure it out.
The key is to pay attention, be patient, and ask questions. Asking questions is not a sign of ignorance. It is a sign of being a learner. This is a good thing.
The list that follows is broken into sections. You can also find it on my downloads page. Keep it handy for future reference.
Teams & Departments
This is a list of the team that is most involved in property operations.
AM (Asset Manager or Asset Management): the team or team member that oversees and drives theproperty business plan. Think of them as the chief operating officer for a property or collection of properties. Example usage: 'I need to run this by the AM before we commit to the capital expense.'"
PM (Property Manager or Property Management): the team or team member that oversees the day to day operations including tenant and vendor interaction. They are in the “front line”, whereas the AM team is a step removed. Example usage: 'The PM will take lead on communicating that to the tenants.'"
CM (Construction Manager or Construction Management): the team or team member that oversees the construction. The PM team often does some construction, but the CM team handles the bigger and/or more complicated jobs. Example usage: 'The CM should handle the roof replacement as it is a more complicated job.'"
PA (Property Accountant or Property Accounting): the team or team member that oversees the accounting and reporting.
Leasing: the team or team member that oversees the leasing of the property, often working with leasing brokers.
Broker: the team or team member that provides 3rd party services for a commission. There are brokers that specialize in leasing, property sales, and even insurance.
Landlord aka Lessor: the property owner (i.e. you).
Tenant or Lessee: the tenant.
Acquisitions
These are the terms that will come up during an acquisition of a property.
OM (Offering Memorandum): a detailed summary of the property and forecasted financial performance prepared by the broker selling the property. Potential buyers use this to create an initial understanding of the property and its value.
Investment Memorandum: a detailed summary of the property and forecasted financial performance prepared by the buyer of the property (i.e. you). Think of this as the OM with your updated financial projections and business plan.
Base Case Underwriting Model: the multi-year financial projection prepared by the buyer of the property (i.e. you).
PSA (Purchase & Sale Agreement): we covered this in Demystifying Real Estate Purchase Agreements. It is the legal document between a property buyer and seller.
DD (Due Diligence): we covered this in Due Diligence: Your Property Investigation Checklist. This is the investigation done by the buyer of a property before they go non-refundable with their deposit.
Go Hard or Non-Refundable: we covered this in Due Diligence: Your Property Investigation Checklist. This is when buyer completes the due diligence, waives contingencies, and “goes hard” with their deposit.
PCA (Property Condition Assessment): we covered this in Due Diligence: Your Property Investigation Checklist. A 3rd party summary of the physical conditionof the property. It is sometimes referred to as the “engineering report”.
Phase I or ESA (Environmental Site Assessment): we covered this in Due Diligence: Your Property Investigation Checklist. A 3rd party summary of the environmentalcondition of the property.
Survey or ALTA Survey: we covered this in Due Diligence: Your Property Investigation Checklist. A 3rd party summary of the title conditions of the property.
Reporting
The reports will be your guide to how the property is performing.
Rent Roll: the list of units / suites at a property with information on square footage, tenants, rent, lease start, lease end, and many other pieces of information. Each company has their own version of the rent roll.
% Leased:leased square feet divided by total square feet. Example: “the property is 95% leased”.
% Occupied:occupied square feet divided by total square feet. Example: “the property is 95% leased, but only 90% occupied because one of the tenants moved out before their lease expired”.
WALT (weighted average lease term): Average lease term based on lease length weighted by tenant square feet. Bigger tenants have more impact on the WALT than smaller tenants.
Rollover Retention Ratio: percentage of tenants (by square feet leased) whose lease expired and renewed. This is expressed for a specific time (ex. one year) and calculated based on square footage. Example: “the rollover retention ratio is 65% for the last year”.
% Above (or Below) Market: comparison of rent for in place leases vs. market rent. Example: “market rents have gone up so much that in place rents are now 30% below market”.
A/R (Accounts Receivable): we introduced this in Due Diligence: Your Property Investigation Checklist. This shows which tenants have underpaid (or overpaid) their rent and other charges.
Tenant Ledger: we introduced this in Due Diligence: Your Property Investigation Checklist. This shows all the charges and payments associated with each tenant. The A/R report is a moment in time. The tenant ledger is the full history.
General Ledger: this shows the charges and payments (debits and credits) associated with ALL property activity, not just the tenants. Example: it includes expenses charged and paid.
NOI (Net Operating Income): we went through most of this in Due Diligence: Your Property Investigation Checklist. NOI = revenue minus operating expenses. NOI is used to value properties under the cap rate methodology as discussed in Cap Rates: The Simple Math of Real Estate Investing. A couple more specifics:
Gross Potential Rent: if all units were leased at market.
EGI (Effective Gross Income): all the revenue for a property beyond just rent but subtracting vacancy and collection losses.
Operating Expenses: day to day expenses to operate the property such as utilities, maintenance, repairs, insurance, property taxes, and property management fees. It does not include capital expenses, tenant improvements, commissions, or debt service. These are “below” the NOI and factored into the calculation of net income.
Net Income: NOI minus capital expenses, tenant improvements, commissions, and debt service.
Gross Receipts: the rents actually collected for a given period (ex. one month). This is typically used for the calculation of the property management fee. Example: $10,000 gross receipts x 5% fee = $500 property management fee that month.
Income Statement: this shows the revenue, expenses, net operating income (NOI), and other activity, usually according to some chosen accounting rules like GAAP (generally accepted accounting principles). These are usually presented in a monthly format with an annual total.
Cash Flow Statement: similar to an income statement, but this will show the actual cash activity. You may care more about the cash flow statement if you are an investor who wants regular cash distributions from your property.
Budget: whereas income statements and cash flow statements show the actualactivity, a budget shows the projected activity. It is usually done 12-24 months at a time.
Cap Rate and Return on Costs: I did a whole newsletter on this Cap Rates: The Simple Math of Real Estate Investing. If you are at all in doubt, I suggest revisiting it.
Cash on Cash Return: annual distribution to investors divided by original equity. Example: $10,000 distribution divided by $100,000 original equity investment = 10% cash on cash return.
Equity Multiple: total cash returns from an investment divided by original equity. Example: $200,000 total distributions (annual plus proceeds from sale) divided by $100,000 original equity investment = 2.0 equity multiple.
IRR (Internal Rate of Return): time weighted calculation of all distributions to an investor, including from the sale, relative to the original equity investment. Ex. 18% IRR over the 5 year hold period.
Hold Period: how long the investor owns the property, from acquisition date to sale date. Ex. 5 years.
FMV (Fair Market Value): what the property could sell for today. Ex. $200,000.
Cost Basis: total equity invested plus the loan balance. Ex. $100,000.
Tax Basis: for income taxes based on tax rules. Remember: depreciation reduces your tax basis. Ex. $85,000.
PSF (Per Square Foot): usually a dollar amount divided by the square footage. Ex. “I bought the property for $100 psf” or “the lease rate is $1.25 psf per month”.
Capex: Capital improvement costs. Examples: roof replacement, tenant improvements, asphalt replacements, building painting.
Leasing
Leasing is a critical function of real estate operations. Here are the key terms to know.
Exclusive Listing Agreement: agreement between a landlord and listing broker agreeing that (a) broker is the exclusive agent for the leasing (not necessarily the sale) of the property, (b) the fee that the listing and procuring broker will be paid when they lease the space and (c) the duration of the agreement.
Listing Broker: broker representing the building owner aka landlord in a transaction. The listing broker markets the property on behalf of the owner.
Procuring Broker (aka Tenant Rep Broker): broker representing the tenant or buyer in a transaction.
MLR (Make Lease Ready) aka White Boxing: proactively performing tenant improvements to a space before there is a tenant. This helps with marketing.
LOI (Letter of Intent): a typically non-binding agreement between owner and prospective tenant that outlines the key terms of the transaction such as lease rate, annual increases, duration of the lease, tenant improvements, options, etc.
Lease: a binding agreement, typically 15 pages with 20+ pages of exhibits documenting in detail the terms of the lease. For industrial, office, and retail leases, this is typically prepared and negotiated with the assistance of legal counsel.
LC (lease commissions): commission on the total base rent the tenant pays during the term of the lease (before any renewal term). Typically paid 50% upon lease execution and 50% upon tenant occupancy.
TI (tenant improvements): one time cost at start of lease, often expressed as a certain amount psf.
Starting Rate: initial lease rate over the term of the lease.
Effective Rate: average lease rate over the term of the lease.
Lease types relative to expense pass through under a lease:
NNN (Triple Net): typically for industrial and retail; 100% pass through of property operating expenses such as common area maintenance, property tax and insurance.
Base Year/Stop (typically for office): 100% pass through of expense increases over the year in which the tenant first occupied the space (e.g., at the end of the first year of the lease/base year, the actual operating expenses are calculated and become the tenant’s base year; at the end of consecutive years, the tenant will pay all amounts above the established base year amount) .
Gross: no pass through of expenses to the tenant. Typical for residential rentals.
Modified Gross: pass through of some but not all expenses directly related to the leased premises.
MLA (Market Leasing Assumptions): key lease terms from the underwriting or budget; include starting lease rate, growth in lease rate per year, free rent, tenant improvements, make lease ready costs, commissions and lease term.
Loss to Lease: gap between today’s market asking rents and the average in-place rent.
Lease Trade Out: difference, usually in a %, between the previous lease rate and the new lease rate at time of renewal or replacement tenant.
Stacking Plan: visual summary of where tenants are located in a property, usually color coded by lease expiration date.
Rentable Square Feet: the square footage of the leased premises for which rent is charged; Includes a portion of the building’s shared/common area space. Different from…
Usable Square Feet: the square feet of the leased premises exclusively controlled by the tenant as opposed to part of the common area. Both used to calculate…
Load factor: percent increase of rentable square footage over usable square footage minus 100%. Example: “the building has a 15% load factor”.
Debt
We covered a lot of these in Debt: An Amazing Tool with Strings Attached.
Term: the length of the loan, typically expressed in years. (e.g. “3+1+1” is a three year loan with two one year extensions.)
Fixed Rate Loan: interest rate is fixed for the entire loan. Fixed rate loans tend to be longer than floating rate loans.
Floating Rate Loan: interest rate changes at a fixed frequency (ex. monthly) in accordance with an index.
Index: a specific measure that changes over time.
10-Year Treasury Rate: example of an index. Comes in other durations like 1 and 5 years. Reflects the “risk free” rate because tied to the US government. 4.34% as of this writing. 3.38% as of March 2023.
SOFR (Secured Overnight Financing Rate): example of an index often used for floating rate loans. Replaced the index LIBOR. 3.64% as of this writing. 0.30% as of March 2022.
Fed Funds Rate: reflects the costs banks charge each other to borrow funds overnight. When people say “the fed increased interest rates”, this is what they are referring to. The federal government uses this to control inflation (increase) and stimulate the economy (decrease). 3.64% as of this writing. 0.25% as of March 2022.
Basis Points or “bps”: a portion of a percentage point where 100 bps is equal to 1.00%; often used in relation to the interest rate on a loan (e.g., “250 bps over SOFR” means 2.50% over SOFR).
Point: 100 bps or 1%. (e.g., “The lender is going to charge a point origination fee”.)
Spread: the interest rate above an index. Examples:
SOFR + 2.50% = 2.50% above the SOFR rate of 4.80% = 7.30% interest rate (floating rate).
5-Year Treasury + 1.90% = 1.90% above the treasury rate of 3.30% = 5.20% interest rate (fixed rate).
Origination Fee: fee charged by a lender to give the loan.
Interest Only Loan: a loan without amortization (repayment of principal each month).
Amortizing Loan: a loan with amortization (repayment of principal each month).
Hedge: typically a cap or a swap.
Cap: an agreement between a borrower and a 3rd party to establish the maximum amount a floating rate index (SOFR) can increase. (e.g. a 6.00% cap on SOFR for 2 years). The borrower pays a one-time fee to the 3rd party providing the cap.
Swap: an agreement between a borrower and a 3rd party to convert a floating rate index (SOFR) to a fixed rate for a specific period of time. Money is exchanged between parties whenever the index adjusts. Both parties are making a bet on whether interest rates will increase or decrease. A borrower may want a swap to reduce uncertainty.
Equity and Joint Ventures
We haven’t gotten to equity and joint ventures yet, but here is a preview for some of the terms we will cover.
GP (General Partner) or Operator: company or individual that operates the property day to day.
LP (Limited Partner) or Equity / Money Partner: company or individual that provides money to buy the property. They could have many or no approval rights.
Major Decisions Rights: rights the LP has to approve certain decisions.
JV (Joint Venture) or LLC (Limited Liability Company) Agreement: agreement between GP and LP that details all the terms under which the partners will operate.
SPE (Special Purpose Entity): legal entity, typically a limited liability company (aka LLC) that the partners are members of through which they own the property. They use this to shield their liability exposure to just this investment.
Entity Organizational Chart: boxes and arrows showing the legal ownership structure.
Signature Block: legal structure of entities authorized to sign on behalf of the legal entity.
Fees: fees paid by the property to the operator for certain functions. These are negotiated between the GP and LP. These fees and functions are in addition to those performed by a broker. All investors (both GP and LP) pay the fees. Examples are shown in the table below.
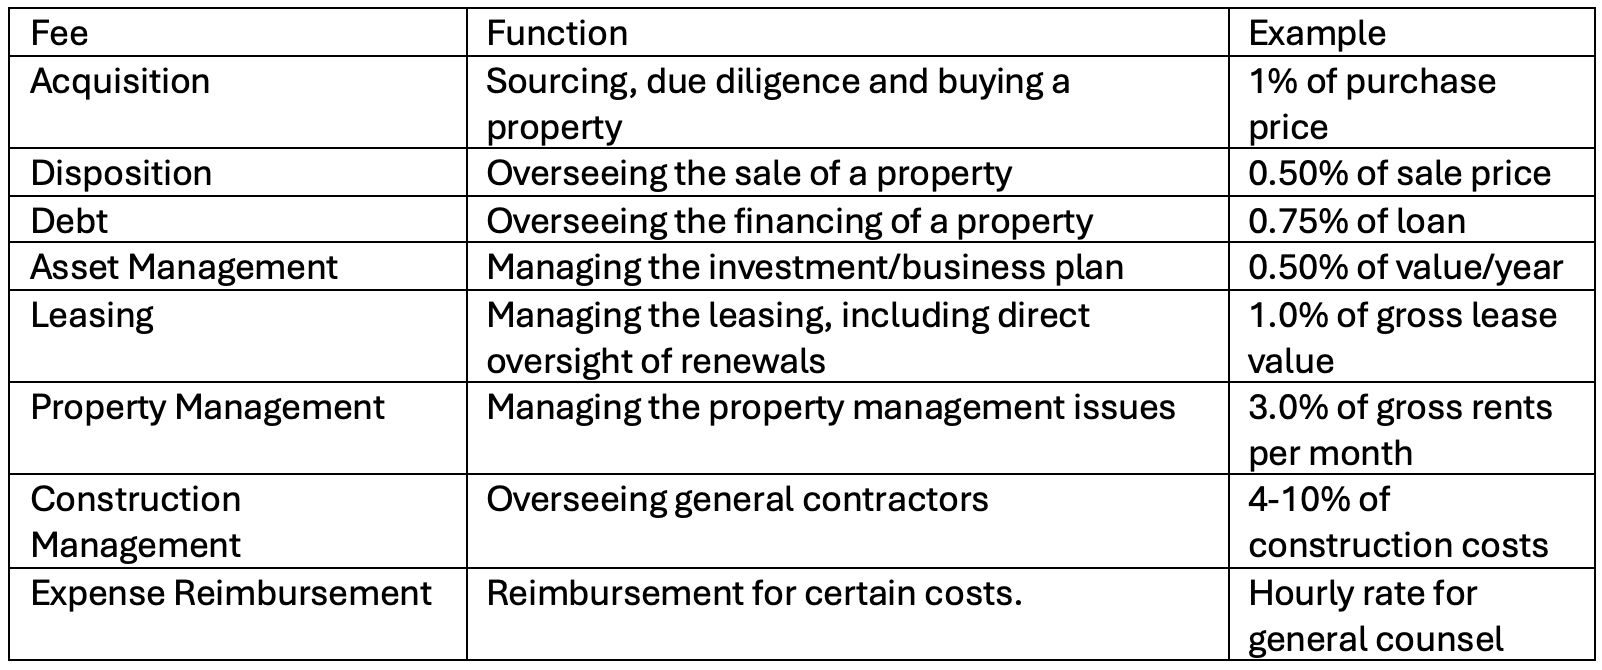
Table: Example Fees Charged by a GP
Promote: money that the GP earns if the investment does very well. Example: GP invests 5% ($50K) of the $1M equity required. LP invests $950K. GP gets 20% of all proceeds above an 8% IRR.
What to Make of All These Terms
Is your head spinning yet?!
You just read a glossary of real estate terms. Well done!
Will there be a test?
No.
But…
You will come across many of these as you invest and work in the commercial real estate industry. You will remember some and forget others.
Just know that this set of information is here for you when you need it. Download an editable file of the glossary on the downloads page.
Add to it as you discover new terms.
Remember that the key is to pay attention, be patient, and ask questions. Asking questions is not a sign of ignorance. It is a sign of being a learner. This is a good thing.
Always be learning!
Closing Day: What to Expect
Documents, money flow, and key takeaways for your first closing
Over the last four weeks we have covered four topics on acquiring (aka buying) an investment property.
Now we are going to get into what happens during the actual closing, when ownership transfers from the seller to the buyer.
This will be the 5th and final newsletter on the acquisition process. Next week we will transition to how to own and manage your property.
Last week’s discussion on debt was long. This one is going to be shorter as it is a fairly straightforward process with far fewer moving parts.
Essentially, the closing process involves two things:
The exchange of money.
The signing of documents to legally transfer ownership.
Let’s dig in.
What is Closing?
When I talk about “closing”, I am referring to the day in which money and ownership transfer between the seller and the buyer.
Due diligence has been completed.
The buyer has gone non-refundable with their deposit and the closing date is here.
What happens next?
Here’s a typical closing timeline:
3-7 days before: finish up loan documents.
1-3 days before: sign documents.
0-3 days before: buyer and lender wire money into escrow. Bind insurance.
1 day before: final review of closing statement.
Closing day: last minute document signing and any other issues.
0-2 days after: notify tenants and vendors; record deed with the county.
The actual “closing day” can be anticlimactic as it may feel like you are just waiting for the escrow officer to say “we are closed”.
The Role of Escrow
As discussed in Demystifying Real Estate Purchase Agreements, the escrow officer at the escrow company plays the “referee” and lead coordinator of the sale process.
They make sure all the documents get signed and sent to them.
They arrange the legal recording (aka evidence) of the sale.
They also hold and distribute the money.
In short, they make it all happen.
Documents Get Signed
As also discussed in Demystifying Real Estate Purchase Agreements, there are a number of “form” documents that were agreed to in the purchase and sale agreement (“PSA”) and added as exhibits.
These “form” documents are then used as templates to create the actual documents that formalize the sale.
They include:
Grant Deed: this is the legally recorded document that confirms the property has been sold. Recording the document with the local municipality allows everyone to see that the property has been sold.
Bill of Sale: this documents the sale of any personal property related to the physical property. Examples: parts and materials for repairing the property such as flooring or light bulbs.
General Assignment: this documents the transfer of the various contracts such as leases, warranties, and service contracts.
There may also be other documents signed such as the one that notifies the county property tax assessor of the sale.
If the buyer is getting a loan to buy the property there will also be:
Deed of Trust: the legally recorded document that shows there is a loan on the property.
Loan Agreement and related documents: each lender has their own set of documents that they like to use.
In addition to documents getting signed, money will need to change hands.
Money Exchange
If both the buyer and the seller each have a loan on the property, then there will be five parties giving and/or receiving money.
These are the parties and this is the typical order in which money flows. Everything goes through escrow.
$ Into Escrow: Buyer sends in their equity.
$ Into Escrow: Buyer’s lender sends in their loan funds. They want to see the buyer’s money in first.
$ Out of Escrow: Seller’s lender receives money to pay off the seller’s existing loan on the property.
$ Out of Escrow: Payments to inspection vendors, escrow, title, and lawyers.
$ Out of Escrow: Seller receives the balance of the sale proceeds.
Here’s a diagram to help you understand.
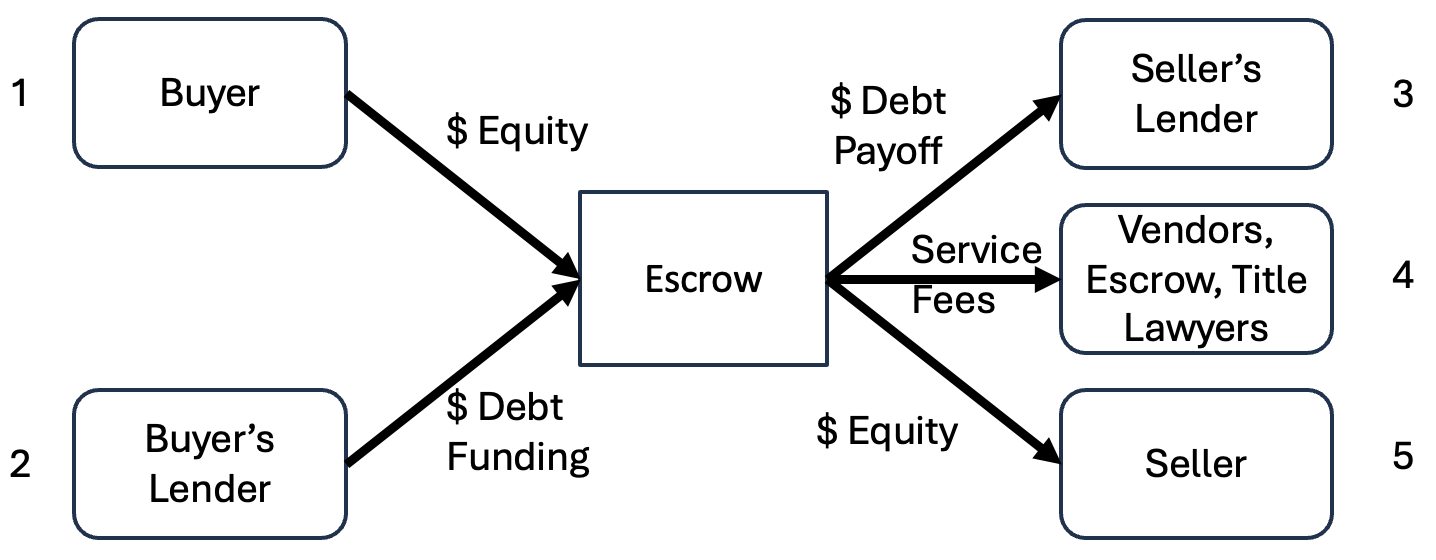
Diagram: Flow of Money at Closing
Escrow officers make it all happen.
Closing day is stressful for all parties. Escrow officers live this every day! Be kind and patient with them.
Let’s move on to another critical component relative to money moving around: closing statements.
Closing Statements
Closing statements show who is getting paid what. There will be at least two closing statements:
Buyer’s Closing Statement
Seller’s Closing Statement
Think of them as an excel sheet showing “charges” and “credits” and ending in a total of how much the buyer and seller will owe and receive, respectively.
Ex. Buyer’s Closing Statement
Charges (amounts buyer has to pay)
Purchase price
Legal fees
3rd party fees for inspections
Escrow and title fees
Loan fees
Prorations*
Credits (amounts that reduce the buyer’s cash needs to close)
Deposits already made during due diligence
The loan
Prorations*
Total: at the bottom it will show how much cash the buyer will need to send into escrow to be able to close the deal.
*See discussion below for the meaning of “prorations”.
Here’s what the math would look like based on our ongoing example discussed in previous newsletters.
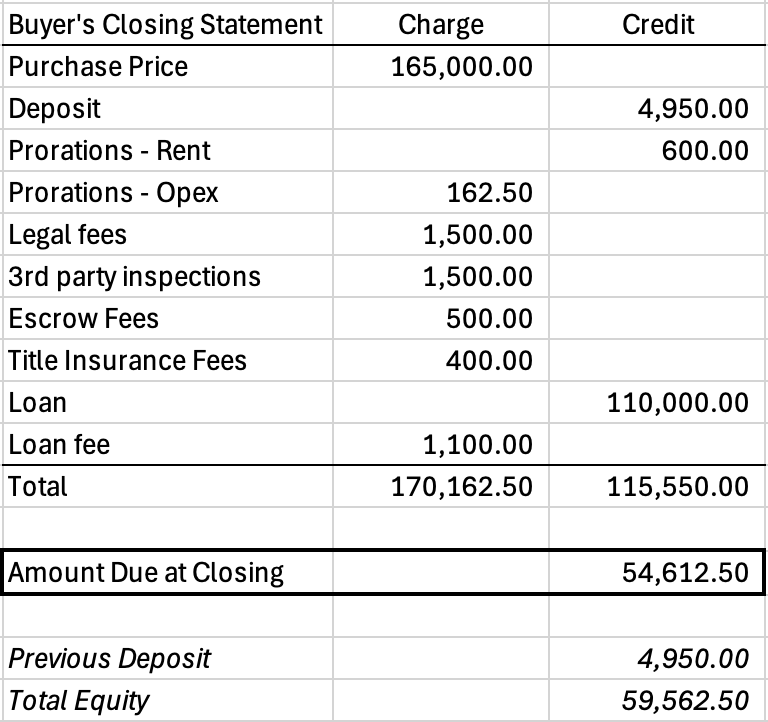
Diagram: Example Buyer’s Closing Statement
The amounts in italics would not be part of the closing statement. I added it to show the total equity the buyer actually funds which is:
$54,612.50 - amount due at closing to escrow
$ 4,950.00 - previously paid deposit
$59,562.50 - total equity paid to escrow
So why doesn’t it equal exactly $60,000 from our previous newsletter discussions?
Because of “prorations”.
Prorations
Prorations are the split of rent and operating expense between the buyer and the seller based on (a) the days of that month the buyer and seller will each own the property and (b) the timing of the rent or expense.
Simple example used in the closing statement above: you close on June 16th, halfway through the 30 day month.
Rent Proration
Tenant paid $1,200 rent to the seller on June 1st.
But the buyer (you) owns the property June 16th to 30th (16 days).
Seller owes you the rent for your 16 days: $1,200 x 16/30 = $600.
This $600 is credited to you on the closing statement.
Operating Expenses
Buyer paid $625 in operating expenses on June 1st.
But the buyer (you) owns the property June 16th to 30th (16 days).
You owe the seller for your 16 days: $625 x 16/30 = $162.50.
This $162.50 is charged to you on the closing statement.
Here are some things to note on these calculations:
Buyer’s ownership of the property starts on the day of closing, in this example the 16th of a 30 day month.
Prorations are based on amounts actually collected (rent) and paid (operating expenses) by the seller. If the tenant hasn’t paid the rent yet that month, the rent is not prorated. This often happens when the closing occurs in the first five days of the month. Same concept for operating expenses.
Insurance is not included in the proration as the buyer will need to get their own insurance. This is often paid through closing. Ask your insurance broker as the amount paid through closing will often be 6-12 months of premiums.
Not all operating expenses are paid monthly. This is especially true for property taxes. The proration will be adjusted for the timing of the payments.
Don’t worry if this is confusing. The escrow officer will do all the math.
What Happens Immediately After Closing
Once closing is complete, a number of things will happen right away.
Receive keys or access codes
Change locks (important for security)
Transfer utilities to your name
Contact tenants to introduce yourself and send them notices with contact information and rent payment instructions
Set up property management/accounting and maintenance vendors
This is because YOU are now the property owner!
Congratulations!
So what do you takeaway from all of this?
Key Takeaways
The closing process is when multiple parties come together to formalize the closing. Here’s what you should remember.
The escrow officer makes it all happen. They are the referee and the coordinator.
You will need to sign many documents: make sure your government-issued photo ID is current. Documents include:
One set to buy the property.
One set if you are getting a loan on the property.
Be 100% available the day before and of closing. There are often last minute documents that need to be signed. Sometimes they cannot be signed electronically, so it is ideal to have a local escrow company.
Many closings now happen remotely using electronic signatures and wire transfers. You may never meet your escrow officer in person. This is normal and perfectly safe - just verify wiring instructions carefully.
Scammers impersonate escrow officers and send fake wiring instructions. ALWAYS call your escrow officer at a verified number to confirm wiring details before sending money. Never rely on emailed wiring instructions alone.
The amount of cash you send to escrow will likely be different than the amount you have in your internal analysis. The difference will be prorations. Most of the time this is a minor issue, but property tax prorations can be big. So can the initial insurance payment. Talk to your escrow officer well in advance to understand this. You can also do the math yourself.
As discussed last week in the newsletter on debt, lender reserves can significantly reduce the amount of initial funding from the lender. A $110,000 loan with $10,000 of reserve holdbacks will only result in $100,000 of funds at closing. Read the loan documents. Understand this in advance. It is no fun to be jammed on the day of closing by not having enough cash to close because of reserve holdbacks by the lender that you should have known about.
Closing can get delayed for multiple reasons: title issues, lender funding delays, missing signatures, wire transfer problems, and other last minute issues. As long as all parties are reasonable and want to make the deal happen, you will be able to overcome these issues.
Stay calm and carry on. It will be stressful, but you will get through it. Don’t get frustrated and send a nasty email you will regret.
You’ve got this.
Follow the lead of your escrow officer (and lawyer if you are using one).
You will complete the closing and own your first property.
Owning the property is where the fun and work really begin.
That is the series we will begin next week.
Debt: An Amazing Tool with Strings Attached
How loans work, what lenders charge, and how to use leverage wisely
Debt. Loan. LTV. Lender.
These are all terms relating to borrowing money to own a property.
If you own a home as your primary residence, chances are that you have a loan on the property.
Why?
Because debt allows you to buy something that costs more than you can afford at that moment in time. It relies on at least two things:
People want more stuff. A bigger house. A bigger investment. Better returns.
There are groups willing to lend people money to get that stuff in exchange for a promise of future payments.
Here are two examples:
First Time Home Buyer
You want to buy a $170,000 home, but you don’t have $170,000. You have built up $60,000 in cash, but you need another $110,000 to buy the home.
Enter the lender.
The lender, often a bank, will loan you the $110,000 in exchange for an agreed upon set of future payments over 5-30 years, inclusive of a certain interest rate and fees. The interest rate and fees are how the lender makes money.
They will do this based on your personal income profile (salary, bonus) and personalcredit score. This is how they determine how risky you are as a borrower.
Investor Buying an Industrial Building
There is a similar structure when you are buying a commercial building with two main differences: (1) how the lender determines risk and (2) how long a loan they will give you.
With a commercial building, the lender looks at the property (in this example the industrial building). They value (aka appraise) the property and look at the income the property generates to make the monthly debt payments. Additionally, they will only give you a 2-15 year loan.
Stay tuned. I will explain this in more detail.
We will cover the basics of debt including:
How a lender makes money.
The niches lender have - just like investors do.
The types of lenders that focus on real estate investment properties.
How a lender determines how much to lend and what interest rate to charge.
The typical timeline to close a loan.
The benefits and risks of borrowing money to own real estate.
Professor Bateman’s key takeaways.
Let’s dig in.
How a Lender Makes Money
Lenders make money in three ways: (i) fees, (ii) interest, and (iii) by getting paid back at the end of the loan term.
#1 Fees: Fees are one-time charges lenders make to the borrower. Examples include:
Origination Fee: To give you the loan.
When: At the time the loan is funded to the borrower.
Amount: A percentage of the loan amount. Ex. 1% of $110K = $1.1K.
Extension or Payoff Fee: A time of extension or payoff.
When: At the time the loan is extended or paid back.
Amount: A percentage of the loan amount. Ex. 1% of $110K = $1.1K.
“Processing Fee”: this is a catch all for the many fees lenders may charge such as underwriting fee, processing fee, application fee, credit fee, appraisal fee, legal fee.
When: At the time (or before) the loan is funded to the borrower.
Amount: These are normally specific dollar amounts. Sometimes they are to reimburse the lender for fees they are paying a 3rd party such as an appraiser or lawyer. Make sure to ask what fees the lender will be charging.
Broker Fee: this is when a broker helped find you the lender and the loan. The fee goes to the broker, not the lender.
When: At the time the loan is funded to the borrower.
Amount: Typically a percentage of the loan amount. Ex. 1% of $110K = $1.1K.
#2 Interest: Interest is the ongoing amount that the lender charges the borrower for the loan. Ex. 7% per year.
7% x $110K = $7,700 per year. Divide by 12 to get the monthly amount of $641.67.
There are two important factors to consider with interest rates, as there are different structures with different types of loans.
Fixed vs. Floating Interest Rate
Fixed: The interest rate remains the same for the entire loan.
Floating: The interest rate changes during the loan, normally based on a fixed amount (ex. 3.50% - known as the “spread”) over a publicly available benchmark such as SOFR or Prime. Ex. If SOFR is at 4.00% and the spread is 3.50%, then the interest the borrower pays is 7.50%. If SOFR increases to 5.00%, then the borrower’s interest rate goes to 8.50% (5.00% SOFR + 3.50% spread).
Why this Matters: You get interest cost stability with a fixed rate loan. With a floating rate loan, you are adding an element of risk (both upside and downside) to your investment based on what interest rates do.
Interest Only vs. Amortizing
Interest Only: Each month the borrower only pays the interest costs.
Amortizing: In addition to the interest costs, the borrower also pays down the principal balance (i.e. a portion of the $110K loan) each month. This makes the borrower’s monthly payment more than an interest only loan payment.
Why this Matters: If you are tight on cash each month, an interest only loan can help a lot, but you will have to pay the full loan amount back at the end of the loan. In an amortizing loan structure, you will “chip away” at the principal balance each month.
#3 Getting Paid Back at the End of the Loan: this one is fairly obvious. If the borrower doesn’t pay the lender back at the end of the loan, then the lender is not going to make money.
To summarize the three ways lenders make money:
Fees
Interest Rate
Getting Paid Back at the End of the Loan
Keep in mind that a lender is not an equity investor. They are not going to benefit from the property being a home run.
In exchange for a lower return, they have lower risk. If the property goes bad and the borrower can’t make interest payments, the lender can take over ownership of the property. This is called foreclosing and the investors lose all their money.
Low risk, low return, better protection. It is a fair trade-off.
Lenders Have Niches Just Like Investors Do
Just as investors pick a niche, lenders pick one or more niches to focus on. Let’s oversimplify a bit and say there are four niche criteria for lenders:
Asset Class: 1-4 unit residential, multifamily, industrial, retail, office.
Geography
Strategy: core/turnkey, light rehab, value add, development.
Recourse vs. Non-Recourse
We should be familiar with the first three as discussed in Stop Chasing Every Deal: Why Successful Investors Pick a Niche.
The fourth one is unique to lending: recourse vs. non-recourse.
A recourse loan means that you are personally responsible to pay back the loan. If you get a home loan, it is almost certain that it is a recourse loan.
A non-recourse loan means that you are not personally responsible to pay back the loan (unless you commit fraud or there is an environmental issue). If there is an issue with the non-recourse loan in the industrial building example, the lender can’t come after your personal assets (cash, home, stock, other real estate, etc.)
In an ideal world, as a borrower you would only get a non-recourse loan.
Why? Here’s an example of a recourse loan gone bad.
You buy a $500K property with $400K loan. The market crashes and the property is now worth $300K. You can't make payments. The lender forecloses AND can come after your personal savings, home, other assets for the $100K shortfall ($400K loan amount less $300K current value).
With a non-recourse loan the lender can only look to the $300K property value, not your personal assets.
So why do some borrowers get recourse loan? For several reasons:
Scarcity: It may be the only type of loan available. There is not a non-recourse option. This is almost always true if you are doing a new development.
Economics: The loan has better economics than the non-recourse option (fees, interest rate, loan amount/proceeds).
1-4 Unit Residential: Lenders view 1-4 unit residential investment properties as personal properties by relying on a borrower’s personal income and credit score. This can be helpful if you are a first time buyer.
Let’s do a quick sidebar to point out three characteristics of loans for value add and development deals, as they are the highest risk and lenders treat them differently.
Loan Term (aka Length): Loans for these type of investments tend to be shorter - say 3-5 years. They are often called “bridge” loans. The idea is that they are more temporary in nature as the property is in transition.
Floating Interest Rate: For the same reasons as the loan term, these are more likely to have a floating interest rate.
Reserve Holdbacks: These are funds the lender “holds back” from the initial loan funding to pay for future costs such as construction, leasing, and even interest rate reserves. This reduces the amount of the loan at closing and allows the lender to make sure you spend their money on what you said you were going to spend it on.
So who are these mysterious “lenders”?
Types Of Lenders
There are four main types of lenders:
Banks & Insurance Companies
Debt Funds
Securitized
Fannie Mae and Freddie Mac (Government Sponsored Enterprises)
Banks & Insurance Companies: These groups lend their own money. Both have excess cash they want to earn a return on: banks from deposits and insurance companies from insurance premiums.
Debt Funds: Debt funds raise money from various investors such as pension funds, insurance companies, and university endowments. Debt funds tend to do riskier loans than banks in exchange for higher interest rates and fees.
Securitized: Securitized lenders function differently in that they plan to sell the loan to one or more investors after the loan closes. They effectively act as a middleman earning a fee. Sometimes they are mainly concerned with how the loan will be viewed by the ultimate buyer of the loan. Watch or read The Big Short to see this go to the extreme.
Fannie Mae and Freddie Mac: Fannie and Freddie are government sponsored enterprises created by congress to support the U.S. housing market (residential properties only). Similar to a securitized loan, a lender originates the loan and then the lender sells the loan to Fannie or Freddie. This allows the original lender to have more money to make new loans. Don’t worry about the details. Just know that they exist.
Key Takeaway: If you are a first time investors, you will likely work with a bank.
With that covered, let’s get to the next big question of how lenders evaluate a loan.
How a Lender Determines How Much to Lend and What Interest Rate to Charge
So how do they do it? With a magic lender calculator?
Quite simply: by assessing risk and pricing accordingly.
More risk, more costs to the borrower.
Assuming the property fits in the lender’s niche, the lender will generally (a) charge more fees and a higher interest rate and (b) provide a lower loan amount for properties the lender views as riskier.
Here’s an overview of the financial tools a lender uses to assess risk:
Appraisal: An appraisal is an assessment of the fair market value of a property as determined by some combination of (i) replacement / construction cost, (ii) similar properties that have sold recently aka “sales comps”, and (iii) the capitalized value. It is completed by a licensed third party appraiser.
The lender will normally have some max amount of appraised value they will lend up to. Ex. 65%. This is referred to as the “loan-to-value” or “LTV”. Here are some LTV rough guidelines. More risk to lender = lower LTV = more equity/cash you need.
Primary residence: 80-97% (3-20% equity)
Investment property (1-4 unit): 75-85% (15-25% equity)
Commercial (turnkey): 65-75% (25-35% equity)
Commercial (value-add): 55-70% (30-45% equity)
Development: 50-65% (35-50% equity)
DSCR: This stands for debt service coverage ratio. Think of this as the lender’s “cushion” in the property’s ability to generate enough income to pay interest. Mathematically it is NOI divided by Interest Costs. Ex. A property generates $10,000 NOI. Loan is $110,000 at 5.5% interest = $6,050 annual interest. DSCR = $10,000 / $6,050 = 1.65x.
The lender normally wants this to be at least 1.20. Remember, they are in the low risk, low return business.
Debt Yield: Think of this a the lender’s cap rate. Mathematically it is NOI divided by Loan Amount. Ex. $10,000 / $110,000 = 9.1%.
The lender will have a minimum target.
Personal Credit & Income: If a recourse loan.
Each lender has their own special formula or hot buttons they use based on some combination of these criteria.
Side note: did anything stand out to you relative to the LTVs above? Even on the riskiest deals, they are all 50% or higher. This means the lender is funding 50%+ of the cost of each real estate investment. The real estate industry would be very different without their support. Thank you to all the lenders out there!
So how long does it take to get a loan? That is our next topic.
Typical Timeline
Finding the right lender (1-4 weeks).
Negotiating a term sheet (1-2 weeks).
Negotiating the loan agreement (1-4 weeks).
Closing the loan (1 week).
Total 4-11 weeks (plan for 6-8 weeks typical).
This can be tight if you don’t start the process until you are already under contract to buy a property, especially if it is your first deal.
Remember that your due diligence period may only be 30 days. You don’t want to be in position where you put your deposit at risk by going non-refundable without certainty on your loan.
Start early. Establish relationships with potential lenders that fit your niche before you have your first property. This will make the whole process much easier.
Now that we have a basic foundation, let’s zoom out a bit to talk about debt on real estate in general.
The Benefits and Risks of Borrowing Money to Own Real Estate
So should you get a loan to buy real estate?
The reality for most new investors is that they will end up getting one to be able to afford their first property. And most seasoned investors will see too much benefit to their returns and scale to not want to borrow.
There are two main benefits to real estate loans:
Benefit #1 - Lower Equity Requirement
You don't need to have or raise as much equity when you have a loan for 50% to 75% of the amount needed to buy a property. An investor may simply not be able to come up with the cash needed to buy a property without a loan or they may want to buy more with the money they have.
Benefit #2 - The Power of Leverage
Leverage is the mathematical and financial benefit of borrowing money at a cheaper rate than the rate of return for the equity investors. If you borrow money at 5.50% and can earn 9.0%, then you have positive leverage.
9.0% earnings is greater than 5.50% cost of borrowing.
Positive leverage is a good thing because you are earning more than the cost of your interest rate.
If you borrow money at 5.50% and can earn 4.50%, then you have negative leverage.
4.50% earnings is less than 5.50% cost of borrowing.
Negative leverage is a bad thing because you are being charged more than you can earn.
If you are a professional real estate GP raising money from LPs you will find it hard not to use debt to be competitive in the marketplace to raise LP capital.
When you believe your investment can earn a 9% total return (IRR) over the full 5-10 year investment, it is too tempting not to turn that into a 12%+ total return by adding positive leverage.
So what are the negatives of borrowing money?
Negative #1 - Increased Risk
Borrowing money increases your risk by (i) increasing your monthly costs in the form of interest payments and (ii) requiring you to pay back the full loan amount on a specific date. Things don’t always go as planned.
Did you know the Empire State Building was under construction at the start of the Great Depression of the early 1930’s? The developer was able to finish the development and keep ownership of the property partly because he built it all cash without debt. If he had a loan, he would have almost certainly lost it to the lender at some point.
Negative #2 - Reduced Control
Not only will the lender charge fees and a monthly interest rate, but they may also have certain approval rights for things like larger leases, major capital improvements, and other operating choices. You limit what you can do when you have a loan on the property.
So what do you make of everything I have discussed here?
Professor Bateman’s Key Takeaways Regarding Debt
Understand that debt and leverage can be a wonderful tool to boost returns, but come with added risk and costs.
Accept that you will likely need a loan on your first deal.
Start early and identify lenders in advance. Not all lenders are created equal. Take the time to find the lender that fits your property profile. Using a debt broker can help.
Form relationships with good lenders to do repeat business.
Become familiar with the lender’s perspective on DSCR, debt yield, and appraisals. This will help you speak their language.
Look beyond just fees, interest costs, and proceeds. These are the financial cost of debt, but there may be operational implications and restrictions. Think about what is most important to you on a particular deal.
Be careful with floating interest rates and short-term loans. These can lead to challenges.
Watch out for pre-payment restrictions or penalties if you pay the loan off early. These limit your flexibility.
Understand reserve holdbacks may reduce your initial loan amount. Ex. A $110K loan with $15K of reserve holdbacks results in $95K of initial loan proceeds. This could mean more equity is required up front to close the loan.
Become familiar with loan documents. Learn more on my downloads page.
Acknowledge the benefit of working with lenders that hold the loans “on their books”. Be eyes wide open on whether the lender will sell / securitize the loan after they make it. Challenges will happen during the loan term. It is a lot better to be able to work problems through with original lender than one that bought it from that lender.
Avoid recourse loans when you can. You may need to take on recourse for your first duplex, but set a goal to avoid it as soon as you are financially able. One bad recourse loan could personally bankrupt you.
In my opinion, owning a property debt free without any LP investors is a fantastic place to be. It gives you the ultimate freedom.
You may not be able to start there, but I encourage each of you to think of it as a goal worth considering over the long term.
Professor Bateman
Due Diligence: Your Property Investigation Checklist
What to review before your deposit goes non-refundable - from leases to roofs
Due diligence.
Another piece of jargon from the real estate industry.
What does it mean?
In plain English:
Due diligence is the process of doing the investigative work to determine if what you think you are buying is what you are actually buying.
It is a way to minimize risk and avoid costly surprises.
If you are buying a 1-4 unit residential property, it is known as your inspection period.
If you are buying a commercial property, it is known as due diligence or “DD”.
You do this in the period of time before your deposit goes non-refundable, as detailed in last week’s discussion: Demystifying Real Estate Purchase Agreements
If you have bought a used car, you have experienced due diligence. You take the car for a test drive. Hopefully you followed up with an inspection or at least outsourced the inspection process by buying a “certified pre-owned” car from a dealer who completed the inspection. Maybe you even read the Carfax report.
All of this was done to determine if the car would drive OK once you owned it.
Same concept with buying real estate.
You want to make sure that you do what you can to confirm your investment property will perform as you expect it to perform.
How do you do this?
I like to use a simple cash flow statement to determine what to look for. Think of the cash flow statement as your guidebook.
By tying (almost) everything back to the cash flow statement, you minimize the risk of surprises.
Today we’ll cover:
How to use a cash flow statement as your due diligence guide
What to review for revenue (rent, vacancy)
What to check for operating expenses (utilities, insurance, property taxes, management fees)
How to evaluate capital improvements (capex, renovations, tenant improvements)
Non-cash flow items (zoning, title, environmental)
Simple vs. complicated properties
Let’s dig in.
Reminder: Refundable vs Non-Refundable
Last week we talked about the difference between the refundable (aka contingency) and non-refundable period. Let’s anchor on this concept again.
Refundable: From the date the Purchase & Sale Agreement (“PSA”) is signed through the expiration of the due diligence period, the buyer can typically back out of the deal for any or no reason and get their deposit back. No penalty. No foul. They still have to pay the consultants and advisors they may have hired and their reputation may suffer, but they don’t have to buy the property nor forfeit their deposit.
Non-Refundable: Once the due diligence period expires, everything changes. The buyer can still back out of the deal, but doing so will mean they lose their deposit.
Due diligence is one of the most important things the buyer does during the refundable stage of the acquisition process.
Cash Flow Statement as a Guide
Let’s continue our property example from one of my previous newsletters: Unlocking Value: What to Do After You’ve Improved Your Property. You are buying a property with $10,000 of net operating income (“NOI”). You believe you can perform a $30,000 light rehab to increase the NOI to $15,000.
In the table below, I have expanded our example to include some assumptions on the revenue and expenses to build up to the NOI.
Revenue less operating expenses = Net Operating Income.
Table: Light Rehab Property - Annual NOI Comparison
Let’s define each line item.
Revenue
Rent: what is paid by the tenants under the leases.
Vacancy / Credit Loss: an assumption that the property will not be leased the full year and/or the tenant will not pay rent and you will need to evict them at some point.
Operating Expenses
These are your recurring costs to operate the property, regardless of whether you have a loan on the property or not.
Utilities: any utilities the tenant doesn’t pay. Remember that you will have to pay utilities in the time between one tenant moving out and the next one moving in.
Repair & Maintenance (“R&M”): you may need to pay for some costs even if the tenant is leasing your property. Example: plumbing repairs.
Insurance: property and liability insurance.
Property Taxes: these are determined by the state and county in which the property is located.
Property Management Fee (“PM Fee”): if you are using a 3rd party to manage the property, you will need to negotiate what fee you pay them. Some GPs choose to act as the property manager and charge a PM fee.
Let’s run through how we can use this as a guide for our due diligence.
Revenue: Rent
There are two ways to look at rent: in place and market.
In place rent is determined by any leases for current tenants. The due diligence process involves reading the leases to confirm the rent and rent increases, any additional rent charges (ex. monthly utility reimbursements), the lease expiration, and any renewal options.
You will also want to note any landlord obligations (ex. replacing an HVAC unit by a certain date), any tenant obligations, and any other items that could affect the performance of the property.
Ideally you will want to interview the existing tenants to ask them how they like the property and if there are any problems with it and/or the landlord.
Market rent is totally different.
You will need to talk with brokers to get their opinion of market rent. In the example above, you are doing the light rehab so you want to talk with multiple brokers to get their opinion on what they think the property will lease for after you complete the light rehab.
Revenue: Vacancy / Credit Loss
Understanding the market and the likelihood (and duration) of vacancy will come from your conversations with the brokers. Simply ask: “How long do you expect the property to be vacant after I complete the light rehab?” By asking multiple brokers the same question, you will develop your own opinion.
Credit loss will be a combination of (a) reviewing the rent payment history of the existing tenants and (b) making an assumption. To review the existing tenants, the seller should provide you an “accounts receivable” report showing any rent that hasn’t been paid by the existing tenants. This is often referred to as the “A/R report”.
Ideally you also get a copy of the “tenant ledger” for the last 3-12 months which shows the payment history and timing of all tenant charges and payments, regardless of whether they currently owe delinquent rent or not. This is key to seeing when the tenants pay each month.
Your loan payment will likely be due in the first 5-10 days of the month. If your tenants don’t pay until the 20th, you will need to build up more cash to be able to pay the loan payment before you get the rent.
Operating Expenses: Utilities, R&M
These are determined by multiple methods:
Review of the seller’s historical income statements: ideally past two years. You want to see what has been paid in the past to determine the future.
Review of any service contracts in place. Examples: pest control, landscaping. The contracts will list the monthly payments amounts.
Review of historical utility statements. This will allow you to see the seasonality of the charges so you can do a monthly cash flow. It will also show you if there were any unusually high or low months. You will want to investigate these. Example: there may have been a water leak that caused the water bills to be high one month.
Operating Expenses: Insurance
You will need to get your own insurance for the property. You can’t use the seller’s insurance. Get quotes for property and liability insurance from an insurance broker. Property insurance if for physical damage to the buildings. Liability insurance is to protect you if get sued.
Operating Expenses: Property Taxes
Property taxes are determined by each state and administered at the county level.
Each state has a different method of calculating property taxes as well as a different frequency at which the amount of the property taxes are both paid and recalculated (aka re-assessed).
Review the seller’s property tax bills. Talk with the county assessor’s office and/or a property tax consultant to determine the specifics of that state and county.
Don’t assume your property taxes will be the same as the seller’s. Every state has different rules.
Operating Expenses: Property Management Fee (“PM Fee”)
The amount of the PM fee will be based on a new contract you negotiate with whomever you hire to manage the property and do the property accounting. It could be the same party as the seller used. It could be a new group.
Fees range from 1% - 8% of revenue depending on the size and complexity of the property.
NOI = Revenue minus Operating Expenses
That’s it.
You have done the due diligence to validate NOI. Well done!
But we are not finished yet.
Now let’s move on to the “below the NOI” items by discussing capital improvements.
Capital Improvements
Capital improvements are physical improvements to the buildings. They fall into three main categories:
Capex: repairing or replacing existing building systems such as the roof or HVAC in a “like for like” way.
Renovations: upgrading the existing building with light rehab or value add improvements.
Tenant Improvements & Leasing Commissions: costs to customize a space for a specific tenant and pay a broker commission for finding the tenant.
Capex
Due diligence is done on capex by:
Hiring consultants to review the existing building systems.
Getting bids from contractors for specific work.
Some consultants specialize in property condition assessment (aka property inspection or PCA) reports. They will give you an overview of the condition of the property with rough cost estimates by year.
But they won’t actually do the work to repair the property.
You need to get specific bids for the work from someone who will actually do the work.
This is key.
If the PCA says the roof needs to be replaced in the first three years, talk with a roof vendor to confirm this assumption and tell you how much it will actually cost if you engage that roof vendor to do the work.
This is where you get real pricing.
Renovations
You have a plan for what you want to do in your light rehab. Hopefully you validated and/or evolved it by talking with local brokers.
Now you need to price it out.
Just as you did with the roof vendor, meet with a contractor who will price out the light rehab and tell you a realistic time frame to complete the work.
Tenant Improvements & Leasing Commissions
This also comes from conversations with local brokers.
1-4 Unit Residential & Multifamily: there will be no or minimal tenant improvement.
Commercial (office, retail, and industrial): tenant improvements are very common. So are leasing commissions. Talk with local leasing brokers to develop realistic estimates. These are often significant ongoing costs for office and retail properties.
Non-Cash Flow Due Diligence
Although everything has the risk of ultimately impacting the property cash flow, there are some items that fall outside our “cash flow statement as a guide” concept.
These generally have the commonality of making sure you can operate the property as expected without interruption from the local municipality.
Zoning: check with the city to confirm the legal zoning for the property and that the property you are buying conforms with that zoning.
Title: most properties have some legal rights placed upon them by 3rd parties. Example: the local utility may have an easement to bring their electric lines to your property. The title report and the ALTA survey will tell you these.
Environmental: if you are buying an industrial or retail property, getting an environmental report is critical. You want to see if there are any issues (ex. old dry cleaner or manufacturer that contaminated the soil). There are consultants that specialize in this and create a “Phase I” report to summarize the environmental condition of a property.
Bringing it All Together
If this feels to you like a lot to review, then you are correct. It is a lot.
A typical due diligence timeline might be:
Week 1: review materials, order reports (PCA, title, environmental)
Week 2: property inspections, broker interviews
Week 3: review reports, contractor bids
Week 4: update your financial analysis and make final decisions
Things move fast. You owe it to yourself to be thorough so you need to be focused, prepared, and methodical. Don’t cut corners.
Here are some common issues that might come up in your due diligence:
Major capex discovered (immediate roof replacement)
Tenants not paying rent (A/R report shows major delinquencies)
Zoning violations (the property cannot be operated as is)
Environmental contamination (discovered in the Phase I report)
Title problems (liens, easements that restrict use)
Sometimes these can be negotiated with a price reduction or time to fix an issue. Sometimes they kill a deal.
If you find a problem, be transparent and solution oriented with the seller. You want to find solution that works for all parties.
Do I Really Have the Time for This?
If you are intimidated by the time involved, note that not all properties require the same level of time in your due diligence review.
Let’s give two examples.
Simple: 2-Unit Residential in Established Neighborhood
Revenue: there are just two leases to review. It is in a neighborhood with a lot of similar properties, some of which have been rehab’d and some of which have not. There are lots of similar properties to reference and talk with brokers about.
Capital Improvements: all you really need to do is confirm the condition of the property and price out your light rehab.
Non-Cash Flow Due Diligence: this will be straightforward as there shouldn’t be any issues.
Complicated: 50 Year Old Industrial Building with 50+ Tenants
Revenue: lots of leases to review. If the units are different sizes and configuration, determining market rent for each will also be complicated.
Capital Improvements: the building systems are old. There may be a variety of tenant improvements that are unique for each suite.
Non-Cash Flow Due Diligence: this could be complicated. Zoning may have changed over time. There is also risk of environmental issues.
In the simple example, you should have plenty of time to complete the due diligence before the period expires.
In the complicated example, you will be working non-stop to get it done.
Walk Before You Run
If you are new to real estate investing, start simple.
The complicated example may look attractive from a theoretical cash flow perspective, but the due diligence will be hard and full of risk for a new investor.
And remember, there are other things you will need to do before your due diligence period expires.
If you are getting a loan to buy the property, this will consume a lot of your time. You need time to figure this out and get the right loan.
Set yourself up for success by starting with a simple property.
Get in your reps.
Become an expert in due diligence.
What you learn in the due diligence process will form the foundation of your understanding of the property and pay dividends in the future.
Take the time to do it right.
For those of you that want to dig deeper, there are more resources on my downloads page.
Professor Bateman
Demystifying Real Estate Purchase Agreements
What's in a Letter of Intent and Purchase & Sale Agreement - and why you shouldn't be intimidated by them
Last week we discussed the process of finding your first real estate investment.
Building market knowledge.
Establishing broker relationships.
Finding and analyzing the right property for you.
The process is simple, but by no means easy. It requires focus and persistence.
Stick with the process. You will find a deal that works for you.
But what do you do once you have found a deal you want to buy?
Do you tell the broker or seller you are interested in buying the property?
Yes!
Do you have to send them something in writing?
Yes! A letter of intent.
Will you have to sign a legally binding document?
Yes! A purchase and sale agreement.
(It’s OK. We sign legally binding documents all the time. It you lease an apartment or a car, you have signed one.)
Will you have time to back out of the deal if you discover a problem?
Yes…up to a certain deadline. The due diligence period.
Never fear! I will walk you through the documents and the steps.
Let’s dig in.
The Letter of Intent: A Non-Binding Agreement
As with many real estate (and non-real estate) transactions, the process of buying a property from a seller usually includes two documents:
Letter of intent: a non-binding agreement.
Purchase & Sale Agreement: a binding agreement.
There are also a series of closing documents signed by each party just before closing, but these tend to be standard forms that are not as actively negotiated. Let’s not worry about the closing documents in this discussion.
So what is a letter of intent?
Think of the letter of intent (LOI) as a “handshake” agreement in 1-5+ pages. It will address the following:
Property Description
Names of Buyer and Seller
Purchase Price
Key Dates: due diligence start and end (aka the contingency period); closing date; extension options (if any)
Deposit - typically around 3% of the purchase price (ex. 3% x $500,000 = $15,000)
Name(s) of Broker(s) Involved
Escrow and Title Company
Confidentiality Requirement by Buyer and Seller
That the LOI is Non-Binding: make sure you check that it is!
Contingencies (if any): examples - loan assumption, tenant signing a lease, physical repairs
That’s about it.
It can be done in as little as one page.
Bigger firms may have more extensive LOI forms that include the list of due diligence items they require or other specifics, but the list above is the core of an LOI.
Most of the time lawyers are not involved as the buyer and seller, with the assistance of their brokers, prepare the LOIs.
The LOI goes back and forth between the buyer and the seller as the way to track the offer and counteroffers. This could happen one or many times.
Once the LOI is agreed to, the parties sign the LOI and move to the purchase and sale agreement.
Purchase and Sale Agreement: The Official Binding Agreement
The purchase and sale agreement (“PSA”) is both (a) much more extensive document than the LOI and (b) legally binding.
When you sign a LOI, you are putting your reputation on the line.
When you sign a PSA, you are putting your reputation AND your money on the line.
Even though most PSA’s give you a 15-30+ day due diligence period before your deposit goes non-refundable (i.e. you can’t get it back), you need to be very serious about buying the property if you sign a PSA.
You don’t want to build up a reputation as someone who signs a PSA but “can’t perform” - never actually buys (i.e closes on) a property. Brokers and sellers won’t take you seriously. The real estate community in most markets is surprisingly small.
So what’s in a PSA?
A PSA has all the components of an LOI plus (i) a more detailed description of the LOI terms, (ii) many additional terms and descriptions, and (iii) the PSA is binding.
Important Note: Refundable vs Non-Refundable
As we discuss the PSA agreement and the purchase process, let’s anchor in on the difference between the refundable (aka contingency) and non-refundable period.
Refundable: From the date the PSA is signed (the “effective date”) through the expiration of the due diligence period, the buyer can typically back out of the deal for any or no reason and get their deposit back. No penalty. No foul. They still have to pay the consultants and advisors they may have hired and their reputation may suffer, but they don’t have to buy the property nor forfeit their deposit.
Non-Refundable: Once the due diligence period expires, everything changes. The buyer can still back out of the deal, but doing so will mean they lose their deposit. Additionally, at this stage they are normally 15-30+ days into the process and emotionally invested in the deal. In my 20+ years of investing in real estate, I have seen less than a handful of cases where someone backs out of the deal after the due diligence period expires.
With that important foundation, let’s run through the additional terms and descriptions contained in a PSA that builds off the LOI.
Operating Conditions During the Purchase Process (aka Escrow)
The seller will continue to operate the property during escrow. Leases and contracts may be signed. Invoices will need to be paid. This section addresses how the buyer and seller will work together during escrow.
Contracts & Leases: the buyer will often have rights to approve contracts and leases during the due diligence process. Once the buyer is non-refundable, they may have controlling rights.
Leasing Costs: the buyer typically pays for commissions and tenant improvements from leases executed after the effective date.
Due Diligence
The buyer will want to review everything they can about the property before they put their deposit at risk by going non-refundable.
Materials: list of materials the seller will supply to buyer. Typical materials include: (i) leases and contracts, (ii) historical income statements, (iii) list of vendors and utilities, (iv) warranties, (v) list of ongoing capital improvements, (vi) details on any outstanding insurance claims, property tax issues, municipal correspondence, and/or legal claims, (vii) seller disclosures of issues affecting the property, and (viii) any other items both parties agree upon.
Inspections: the buyer will have the right to inspect the property, including with their consultants, in a non-invasive way. They will need to get explicit approval from the seller to be able to perform invasive testing.
Representations & Warranties
This is a fancy way of saying (a) what is each party saying is true <a “rep”> and (b) what will each party agree to do <a “warranty”>. They generally focus on the seller and include:
Reps: the seller has the authority to sell the property. The seller is not bankrupt nor has any pending litigation. There are no tenants, leases, and contracts other than the ones provided in due diligence. The due diligence materials provided are true and correct.
Warranties: the seller will maintain insurance. The seller will continue to operate the property in a professional manner leading up to closing.
Damage & Destruction, Condemnation
Damage or Destruction: what happens in the event the premise is damaged or destroyed? The buyer may have the right to back out and keep their deposit if more than 5% of the property is destroyed.
Condemnation: what happens in the event the premise is condemned? The buyer may have the right to back out and keep their deposit.
Closing Process
The PSA documents the details of the closing process including:
Closing Conditions - Buyer: waived due diligence contingency; received title policy from title company.
Closing Conditions - Seller: maintained reps and warranties; delivered required closing documents to escrow.
Closing Costs: list of what buyer and seller will each pay. Seller typically pays the broker commission.
Closing Steps: description of how the escrow company will handle the closing logistics.
Exhibits
Although PSA may be only 15+ pages, there could be 20+ pages of exhibits. These can include:
Legal Description of the Property.
List of Due Diligence Materials.
Form of Deed: this is the legally recorded document that confirms the property has been sold.
Form of Bill of Sale: this documents the sale of any personal property related to the physical property. Examples: parts and materials for repairing the property such as flooring or light bulbs.
Form of General Assignment: this documents the transfer of the various contracts such as leases, warranties, and service contracts.
Form of Estoppel: very briefly, an estoppel is a unilateral statement signed by the tenant for the benefit of a buyer and their lender confirming the key terms of a lease. Estoppels are common in larger commercial transactions.
Any other specifics details relevant to the property such as the status of ongoing capital improvements.
At a Glance: LOI vs. PSA
LOI
Legally Binding: no
Length: 1-5 pages
Purpose: handshake agreement before legal documentation
At Risk: reputation
Lawyer needed: no
PSA
Legally Binding: yes
Length: 15-35+ pages
Purpose: legal contract
At Risk: reputation and money
Lawyer needed: if not using standard forms
How to Digest All of This
That was a lot to cover.
Some of you may be overwhelmed with the amount of detail and feel that it can’t be this complicated. Some of you may feel I am only scratching the surface.
You are both correct.
The level of complexity mainly depends on whether you a buying a 1-4 unit residential property or a commercial property (industrial, retail, office, or multifamily).
1-4 Unit Residential
If you buy a 1-4 unit residential property, whether for your personal residence or as an investment, you will likely use a templated agreement that is literally “fill in the blanks”. You won’t even use a letter of intent.
Everything will be done using the PSA offer and counter offer templates.
No lawyers. No negotiating items you are struggling to understand.
Some of you can breathe a sigh of relief.
Commercial Properties: Industrial, Retail, Office, Multifamily
For the rest of you, you will likely need to take the time to develop a basic understanding of what I described in the LOI and PSA documents.
For deals under $10 million, you may still use standard form PSA agreements like those created by AIR CRE. This is referred to as “using an AIR form”.
The benefit of this approach is that the buyer and seller are each agreeing to most of the items that get negotiated. They can focus their efforts on adding exhibits for items that either (i) fall outside the AIR form or (ii) they want to more actively negotiate.
This can be a great approach and one I support for smaller deals.
For those of you buying larger commercial deals and using customized PSAs, here’s my advice:
Find a Good Lawyer: work with a lawyer who understand the issues that will come up AND is business minded - i.e. they want to figure out a reasonable solution to each item that is negotiated as opposed to proving how smart they are by over negotiating every item.
Get Smart: spend the time needed to understand the issues from a business perspective as opposed to just relying on what the lawyer says. Think through what the issue really means. Ask your lawyer to explain issues in simple language and give you examples of real situations where this language would apply. As the buyer, you make the call on the final language. Not the lawyer. It is your money and reputation.
Red Flags to Watch For
While most sellers are honest, watch out for red flags such as:
Seller resistant to reasonable contingencies > make sure you protect yourself.
Significant items missing from due diligence materials > dig in to make sure the seller is not hiding something important.
Seller rushing you through due diligence > take the time you need but understand that you can never make a “risk free” investment.
Trust your gut and don't proceed with the deal if it doesn’t feel right.
The Purchase Process in 5 Steps
The LOI and PSA are integral steps in the overall purchase process:
Find property (last week’s newsletter)
Submit and agree on a LOI (handshake agreement): 3-7 days
Negotiate and sign a PSA (binding contract): 7-14+ days
Complete the due diligence and go non-refundable (next week’s newsletter): 15-30 days
Close: 15-30+ days
Yes it gets more complicated with additional investors and obtaining a loan, but this is the basic process. A fast process takes 30 days. A more typical process takes 45-90 days.
My Two Cents on How to Think About a PSA
I tend to find the heavy negotiation of PSAs to be overkill.
Why?
If there are issues that come up in the purchase process, reasonable buyers and sellers are normally motivated to work it out regardless of what the PSA says.
View the PSA as your purchase process handbook. It should guide you in the process.
But, remember that your most important asset is your word and your reputation.
Over negotiating the PSA as a way to plant trip wires to out maneuver your counterparty (whether buyer or seller) may help you on an individual deal, but will set you up for being known as a bad actor in the long run.
Be as good as your handshake.
Be a good person.
Life is better that way.
Professor Bateman
How To Find Your First Real Estate Deal: A Step-by-Step Guide
From online research to broker relationships—putting in the reps that lead to your first investment
We have covered a lot so far. Today we are going to dig into how to find your first deal.
Before we do this, let’s do a quick recap of what we have covered:
HOW to invest - REITs, LPs, self, with a partner, or as a GP: 5 Ways to Invest in Real Estate (From $60 to All-In)
WHAT to invest in: Asset Classes Explained: Industrial, Office, Retail, Multifamily, and 1-4 Unit Residential
TAX advantages: 5 Tax Advantages That Make Real Estate Investing So Powerful
BUILDING A TEAM: You Don’t Have to Do Everything Yourself: Building Your Real Estate Team
Finding your NICHE: Stop Chasing Every Deal: Why Successful Investors Pick a Niche
Choosing your STRATEGY: The Risk-Return Spectrum: Choosing Your Real Estate Investment Strategy
How to UNLOCK VALUE: Unlocking Value: What to Do After You’ve Improved Your Property
The simple MATH of real estate: Cap Rates: The Simple Math of Real Estate Investing
Moving forward we are going to address the practical realities of:
BUYING real estate investments: picking a market; working with a broker; analyzing deals; purchase and sale agreements; debt and equity; due diligence; and closing.
OPERATING the property: value add initiatives; leasing; property management; construction; reporting; insurance; and property taxes.
SELLING your property: working with a broker; preparing the property for sale; due diligence; purchase and sale agreements; debt and equity considerations; and closing.
Today marks the start of the series of several newsletters that will explain buying real estate investments.
Let’s dig in.
Understanding What You are Looking For
If you don’t know what you are looking for, you will be like a blind squirrel searching for a nut. You may find it eventually, but you will waste a lot of time in the process.
A few weeks ago I discussed the importance of finding your niche and determining your investment strategy. Let’s build off these concepts and our previous examples.
In the niche newsletter I created four examples of different combinations of asset class, geography, and strategy based on an investor’s time availability:
No spare time: Retail - Tacoma, WA - Turnkey.
No spare time: 1-4 Unit Residential - Nashville, TN - Turnkey.
Some time to be more active: Industrial - San Antonio, TX - Light Rehab.
Time on evenings & weekends: 4 Unit Residential - Los Angeles, CA - Value Add.
Regardless of the asset class, geography, and strategy, the methodology is the same.
Getting in Your Reps
The first step is to start looking at deals. The great news is that you can do this after hours and on the weekend from the comfort of your own home.
How?
By using the power of the internet, your time, and (to quote the musical Hamilton) your “top-notch brain”!
There are many websites out there that list properties for sale:
LoopNet.com - best for commercial properties (industrial, retail, office, larger apartments/multifamily).
Redfin.com or Zillow.com - best for 1-4 unit residential.
Realtor.com - MLS-connected; comprehensive for residential.
Note that Redfin, Zillow, and Realtor will also be filled with properties for sales to homebuyers to live in.
Pick one or two and set the filters to the parameters that fit your asset class and geography niche, as well as your price range. You won’t be able to filter by strategy (turnkey, light rehab, value add). To figure this part out, you will need to review the details of the property listings.
Step 1 - Go Down the Rabbit Hole
In your first pass, dedicate 1-2 hours to click around. Think of this like doom scrolling. You are reviewing the information in a general way to get a lay of the land.
Pay attention to how the assets (and the process) make you feel. Is there real interest in this niche? Do you get excited? Does this put you to sleep?
Do you feel like you could come up with the equity (cash) to buy the property - assume you need 35% of the purchase price - example: $300,000 property x 35% = approximately $100,000 of equity.
If it puts you to sleep or is out of your price range, consider exploring another niche.
Don’t give up. Finding your niche is an interactive process that takes time.
Step 2 - Bring Some Structure
Now it is time to be more methodical by bringing structure to the process.
Get a pencil and a piece of paper (or open excel). Create a simple grid that lists the following details as columns for each property. Each property will be a row.
Address
City or submarket
Square feet or number of units*
Asking (purchase) price
Price per square foot or per unit*
Rough calculation of annual net operating income (NOI, which equals revenue minus operating expenses). This should be on the listing or you can make an estimate.
Cap rate: NOI divided by price.
*Use units for multifamily and 1-4 unit residential. Use square feet for retail, industrial, and office.
I did something similar for industrial properties in Escondido, CA on LoopNet last summer.
Example: My Escondido Industrial Property Search (Summer 2025)
What you are looking for is the properties that are a little better than the rest. In this case I was using cap rate (aka return on cost) as my main guide (column header is “Cap / ROC” in the table above.
Alternatively, I could have used price per square foot (“PSF” in the table above).
For each of the properties that had the higher cap rates (#s 6,9,10, and 11), I reviewed the materials on LoopNet in more detail and added some comments.
I didn’t like #10 and 11 because of some of the physical characteristics shown in red in my Comments column.
This left me to focus on #s 6 and 9.
The whole process took me a few hours.
Step 3 - Talk with Brokers
What?!?!
You mean I have to call someone I don’t know?!
Yes. You can do it. It is just another human being on the other end of phone.
To set you up for success, let’s breakdown the role of a broker.
In regards to looking at a property for sale, the broker that is listed on LoopNet or similar websites is hired by the seller to market the property for sale. The broker only gets paid (by the seller) if the property is sold. Said another way, they are spec’ing their time in hopes that they can successfully sell the property at a price that is acceptable to the seller.
Part of the role of a broker is to talk with prospective buyers about the property they are trying to sell.
They are working through the traditional sales funnel.
They have to talk with many potential buyers.
Some of those will turn into actual leads that spend time focusing on the property.
A smaller amount will actually make offers.
And one will (hopefully) be acceptable to the seller and buy the property.
So what does this mean for you?
If you call a broker and come across as being clueless and unorganized, the broker will see right through you and be unlikely to want to give you any time. A broker’s most precious resources are their time and reputation.
Don’t waste their time.
Be respectful.
Brokers are an essential part of the real estate investing process. A good relationship with 1-3 good brokers may turn out to be the most critical part of your personal real estate team. They are the source of the majority of investing opportunities out there.
But what if you are just starting out? What is realistic for you?
Here’s a script that I recommend:
You: Hello [broker’s name]. I am reaching out to learn more about [XYC property] I saw on [LoopNet]. I have spent the last X weeks researching properties like this in this market and this one stood out to me as one I want to learn more about.
Broker: Good to hear from you. Can you tell me about yourself before I walk you through the property? [Translation: are you someone I should spend my time on?]
You: Happy to. I am newer to real estate investing, but am ready to buy my first deal. I picked this market because XXX. I have the equity to buy a deal of this size (or have lined up investors). I have some ideas on putting a loan on the property, but would also welcome your perspective on loan options. I am looking to establish one or two key broker relationships with the goal of buying multiple properties over the next X years. What questions should I be asking about this property and the market?
—
What works about the script above?
You are being candid in the realities of being new.
You are showing that you have put in the time to focus on a niche.
You are making it clear that you have a path to getting the equity.
You are opening the door to a long-term relationship with this broker.
So what’s next?
Step 4 - Patience and Repetition
Now you need to keep doing steps 2 and 3 until you find a deal that works for you.
Expect to take 3-6+ months until you find a deal that works for you that you can get under contract. This includes:
Building market knowledge (4-8 weeks).
Establishing broker relationships (2-6 weeks).
Finding and analyzing the right property (4-12 weeks).
Expect to review 20-100+ properties online and dive deep into 5-20 of these before you find the right deal for you.
New properties become available for sale all the time. Establish a routine where you check for new properties for sale every two days.
By putting in your reps, you will start to better understand your niche and what works best for you. At some point you will see a property that checks all your boxes and is priced at a level that makes sense to you.
By then you will have talked with multiple brokers and seen many deals. Some of these brokers will even start sending you deals proactively, possibly even before they hit the market.
Important note on 1-4 unit residential deals: make sure you work with a broker that specializes in investment properties, not the homebuyer market. Investment brokers will understand how to analyze a property from an investment perspective.
You will have built a level of micro expertise in your market and established some small level of credibility with brokers in that market.
Most people have very little staying power. They try something and quickly give up.
Be the exception.
Pick a niche.
Be respectful of brokers’ time. Leverage their market expertise.
Put in the time and focus to understand the market.
Before you know it, you will have found a deal that looks like it works for you.
So what do you do when this happens?
Call the broker immediately - good deals move fast.
Ask for the offering memorandum or marketing package that provides the details about the property.
Request a tour if you are local to the market (or even a video tour if you are not).
We’ll cover the purchase process in detail next week.
Professor Bateman
Unlocking Value: What to Do After You’ve Improved Your Property
Cash flow, sale, or refinance—which monetization strategy fits your goals?
Let’s fast forward a bit and have some fun.
Imagine you have made your first investment. It has gone well.
You've done everything right—bought smart, improved the property, and now it's cash flowing.
Well done!
Your hard work, patience, and perseverance have paid off. Maybe there was even a little luck along the way.
But here's the question most investors face next: how do you actually get your money out?
There are three main ways to do this:
Enjoy the cash flow.
Sell the property.
Cash out refinance.
Each way has its pros and cons. The decision of what to do depends on the goals you are trying to achieve, which may change over time.
Let’s dig in.
Your Real Estate Investment Example
Let’s create an example to use in explaining and evaluating the three ways to monetize your investment. The math will tie to my previous post: Cap Rates: The Simple Math of Real Estate Investing
Here’s the example:
A little over two years ago, you bought a property that was 100% leased to one tenant with two years left on the lease. The NOI at time of purchase was $10,000.
You bought the property for $170,000 including your closing costs. After securing a $110,000 loan with a 5.5% interest rate, your equity was $60,000.
$170,000 - $110,000 = $60,000
The property was old and in need of some cosmetic repairs. As it was fully leased when you bought it, you waited patiently until the lease expired to completed your light rehab.
You spent $30,000 to do a light rehab (paint, carpet) and paid a commission to a broker to find a new tenant. Because the loan amount is fixed, the $30,000 cost increased your equity (aka cash investment): $60,000 original equity + $30,000 light rehab and commissions = $90,000 total equity.
After the light rehab, you were able to increase the NOI to $15,000.
Here’s a summary table to help you keep track of everything.
Real estate investment example cash flow
So what do these calculations tell us?
Cash Flow Increase
By spending a one-time cost of $30,000 for the light rehab and commissions, you went from $3,950 per year of cash flow to $8,950 per year. $30,000 to get $5,000 more per year? Well worth it.
NOI Increase = Value Increase
You have increased the NOI. NOI is a key metric buyers and lenders use to value a property. To oversimplify a bit, the value of the property has increased.
Why is this oversimplifying?
Because cap rates can go up and down depending on overall market sentiment, independent of your individual property.
For this discussion, let’s assume they stayed fixed.
Monetizing Value
Now let’s get into the fun part. How do you turn our hard work into cash? Said another way, how do you “monetize” the increase in value?
There are three main ways to do this:
Enjoy the cash flow.
Sell the property.
Cash out refinance.
Each way has its pros and cons. The decision of what to do depends on the goals you are trying to achieve, which may change over time.
Monetizing Value: Enjoy the Cash Flow
The first way is the most straightforward and passive: do nothing and enjoy the increased cash flow.
The $8,950 cash flow per year after light rehab on your $90,000 of equity is a 9.9% annual cash-on-cash return. Much of it is shielded from tax by depreciation. See 5 Tax Advantages That Make Real Estate Investing So Powerful.
If you are a cash flow investor like I am, this may be the best fit for you.
Monetizing Value: Sell the Property
Properties are typically sold based on a capitalization rate (cap rate). In this case you bought the property for a 6.1% cap rate: $10,000 NOI divided by $165,000 purchase price = 6.1%.
Let’s assume you can sell the property for the same 6.1% cap rate. $15,000 post light rehab NOI divided by 6.1% = $245,902.
This gives you a profit before commissions, closing costs, and income tax of $45,902. $245,902 - $200,000 total costs. Not a bad return in two years for your equity investment of $90,000.
If you are focused on increasing your total net worth as much as possible, this could be the path for you. You could consider a 1031 exchange to defer the taxes as I discussed in 5 Tax Advantages That Make Real Estate Investing So Powerful.
Monetizing Value: Cash Out Refinance
Refinancing the property could be a way to have the best of both worlds.
The increase in NOI will likely allow you to put a bigger loan on the property. Your original loan of $110,000 was approximately 65% of the purchase price.
Using the same 65% on the new market value we calculated above ($245,902) would give you a new loan of just under $160,000. $245,902 x 65% = $159,836. This new loan amount is almost $50,000 more than your original loan.
Doing this is known as a “cash out refinance”. There is no tax on the $50,000. You could use it to invest in a new property.
Important Caveat: Not all lenders will immediately give you a cash out refinance. Every situation is different so talk with multiple lenders.
Remember than your interest costs will go up and your cash flow will go down. If we assume the same 5.5% interest rate, your annual cash flow drops from $8,950 to $6,209.
Refinance example
You also have higher fixed expenses with the new interest costs. This gives you less cushion if you lose the tenant and/or the economy gets bad.
A cash out refinance is a good option for investors who want the best of both worlds (and are comfortable with higher fixed expenses): ongoing cash flow and additional money to invest in the next deal.
Monetization Options: Sale vs Cash Out Refinance
In this example, the cash out refinance proceeds ($49,836) are more than the sales proceeds before closing costs and commissions ($45,902).
This is not always the case.
Interest rates and cap rates regularly move around depending on market conditions and market sentiment. If you are on the fence of which option is best for you, educate yourself by talking with brokers on market cap rates and lenders (or debt brokers) on loan options.
Monetization Options: Pros and Cons
So let’s put it all together to see what the best fit for you is.
Enjoy the Cash Flow
Action: none; enjoy the additional cash flow.
Pros: passive; no further execution risk.
Cons: minimal current cash compared to a sale or cash out refinance.
Good for: investors focused on cash flow.
Sell The Property
Action: sell the property.
Pros: ability to unlock value and 1031 exchange into a new property to repeat the process of a new strategy on a new property.
Cons: execution risk on the sale; sale commission costs; tax exposure if no 1031 exchange.
Good for: investors focused on creating maximum wealth by buying and adding value to multiple properties over time.
Cash Out Refinance
Action: refinance the property with a larger loan.
Pros: ability to unlock value without paying taxes and continue to benefit from (a reduced) cash flow; the proceeds from the cash out refinance could be used to buy a new property.
Cons: execution risk on the refinance; transaction costs of refinance; risk of having more debt and interest expense.
Good for: investors wanting to balance ongoing cash flow and ability to grow their real estate portfolio by buying new properties.
What Worked for Me
As with my investing strategy, my monetization strategy has changed over time.
Stage I (Years 1-10+): Buy > Add Value > Sell > Repeat
I was all about maximizing the power of the limited funds I had. The goal was to create value, sell a property, and invest it in a new one. This was an effective method to build wealth. I still have a number of investments that fit this strategy.
Stage II (Years 10+): Enjoy the Cash Flow & Cash Out Refinances
Once I had built wealth, or at least could see a path to that future with my existing investments, I started to be more focused on cash flow. I was able to build up a combination of assets under two strategies:
Cash Flow: I have one property that I own debt free. The strategy is focused on consistent cash flow.
Cash Out Refinance: Buy > Add Value > Cash Out Refinance > Repeat. The LP investments I have follow this strategy. I use the cash out refinances to buy more cash flowing assets.
These stages have worked well together. I wouldn’t have been able to focus on cash flow investing without the capital I built up through selling properties.
Finding the Monetization Option That Fits You
Let’s think about what might work for you.
Situation A: Limited Capital, Long Time Horizon
This is likely your situation if you are early in your career. You are rich in time, energy, and health, but poor in money. You have a long time horizon for the power of compounding to go to work.
The buy, add value, sell, and repeat is a path that could allow you to turn your limited funds into something more meaningful.
Situation B: Some Capital, Shorter Time Horizon
Maybe you are exploring real estate investing for the first time later in life. Your time horizon to retirement, or at least leaving a W-2 job, is shorter. You have worked hard and saved a decent amount of capital to invest.
In this case a combination of enjoying the cash flow and cash out refinances may be a better fit for you.
What is Right for You?
I have seen investors follow each of these paths successfully. It all depends on your available capital, time horizon, and goals.
Do you have an investing story that you are willing to share with me? Email me at bateman@creprofessor.org. I read every email and would like to hear from you.
Professor Bateman
The Risk-Return Spectrum: Choosing Your Real Estate Investment Strategy
From low-risk turnkey deals to high-return value-add and development—which fits you?
Here’s a question you may be asking yourself: ‘Should I buy a turnkey rental or fixer-upper?’ The answer depends on understanding risk versus return - and knowing where you sit in this spectrum.
Low Risk/Low Return ←――――――――――――→ High Risk/High Return
Last week we discussed the importance of picking a niche in terms of “how” (REIT, LP, solo, GP) and “what”. I introduced the three components of the “what”:
Asset Class: 1-4 unit residential, apartments, office, industrial, retail.
Geography: where you plan to invest.
Strategy: core/turnkey, light rehab, value add (or fix and flip), house hacking.
In today’s discussion, we are going to dive deeper into strategy.
Strategy will likely be the strongest dial you can control to determine the risk and reward that is right for you.
Risk and reward are generally inversely correlated. The more risk you take on, the higher the potential reward.
The key word here is “potential”.
Just because you have the potential to hit a home run, doesn’t mean you will. It often means you have a high chance of not hitting the home run - especially in your early days as an investor.
Successful investors have a clear understanding of risk vs. reward. The best ones pick a risk/reward niche to focus on so they can develop expertise in understanding and minimizing risk, all while trying to achieve above market returns.
Let’s dig in.
Five Strategies for Real Estate Investing
There are five strategies we will discuss today. Four apply to all asset classes. The last one only applies to 1-4 unit residential.
Low Risk/Low Return ←――――――――――――→ High Risk/High Return
Core/Turnkey → Light Rehab → Value Add → Development
Core/Turnkey: low risk, low return. You buy a property that is well leased and maintained. There is minimal work to do.
Light Rehab: medium risk, medium return. There is some work to do, but it is mainly cosmetic (paint, carpet, clean up). If you do the work, you can increase the rent and value of the property.
Value Add: high risk, high return. There is a lot of work to do. The property might even be vacant. You will be repositioning it and taking on a lot of risk for superior returns. You will either find a tenant once the work is complete or sell it (fix and flip).
Development: highest risk, highest return. You build something from scratch.
House Hacking: this option only applies to 1-4 residential. You will live in one unit (or room) of the property and rent out the other units (or rooms), allowing you to live rent free or at a reduced cost.
Each strategy has its own pros and cons. There is no right answer.
Choosing the right one for you depends on the time you have and your tolerance for risk.
Let’s discuss each one in more detail.
Core/Turnkey: Low Risk, Low Return
These type of deals require minimal work. They are fully leased and the physical building is in good condition. They are closest to stock market index fund investing in effort (low) and function similar to a bond, giving you consistent cash flow. Examples could include:
A single tenant leased building built in the last 10 years and leased for 10+ years. This could be retail, industrial, or even office.
A new four-plex in a strong housing market near a hospital or other major employer. Although the leases are not long, there is a major employer nearby who helps ensure all units will remain leased with little downtime between leases.
Core/Turnkey deals are great for investors that want steady cash flow and don’t have a lot of time.
Light Rehab: Medium Risk, Medium Return
Let’s continue up the risk/return spectrum to Light Rehab. There is some rehab to do, but it is fairly straightforward and mainly cosmetic (paint, carpet, clean up). It is the type of work that you could potentially do yourself on nights and weekends, or hire a handyman to do.
Essentially, you are freshening up the property and once complete, will enjoy some combination of higher rent, shorter time between leases, better credit tenants, or a combination of all three. Examples could include:
A well built four-plex that is 30+ years old in a good market. The paint is peeling and the carpets are stained. Both are straightforward to fix. Buildings that look cleaner and more appealing are leasing for 10%+ more rent than the in place leases at this property.
A single tenant industrial building that only has six months left on the lease. The existing tenant has been there for 10+ years, plans to vacate, and is leaving the space very dirty. Painting the walls, replacing the carpet in the office, and power washing the warehouse floors will make it look much better.
Light Rehab deals are good for investors that want to be a little more hands on in order to achieve better returns than core/turnkey. They are ok with some risk, but are not willing to spend too much additional money nor take on something too complicated.
Value Add: High Risk, High Return
Let’s continue up the risk/return spectrum. By buying a value add deal, you are signing up for a hands on investment. There will be a lot of work to do, including work that is not just cosmetic in nature. You may be redoing bathrooms or replacing roofs or even building out new rooms.
This is much more than a light freshen up. It will likely include hiring a general contractor and obtaining a building permit. All of this means more time and money.
In exchange, you will enjoy a meaningful increase (ex. 25%+) in the value of the property through a combination of higher rent, shorter time between leases, better credit tenants, or a combination of all three. Examples could include:
A 40+ year old two story home in a zoning location that allows for up to four units. The investor will convert the property into a four plex. This will include adding three small kitchens and a new restroom, plus reconfiguring the property to create four individual private entrances.
A 20+ year old retail property that had been leased to one tenant since it was built. The investor will convert it to a three tenant building by adding demising walls, bathrooms, and storefront entrances.
Value Add deals are good for investors that have a vision for what a property could be. They have time and money to do the work and are determined to maximize the value of their investments.
Development: Highest Risk, Highest Return
Developers are a breed of their own. They are like business entrepreneurs who create something out of nothing. Development is so complicated that I could (and may) dedicate an entire newsletter to it.
For now, let’s just say that it includes (i) buying the land with a vision for what could be built, (ii) creating an initial design and getting municipal approval to build it - the entitlements, (iii) spending time and money on construction drawings, (iv) going back to the municipality for a building permit, (v) hiring a general contractor to build the property, and (vi) leasing it. Examples could include:
Buying vacant land and building a small industrial building.
Tearing down an old house and building a new four-plex.
Development is a high risk process at each step. It is not for the faint of heart or inexperienced. Each step requires specialized knowledge: architecture, engineering, municipal approvals, construction management, and market analysis. Most developers spend years learning their craft before attempting their first project.
House Hacking: 1-4 Unit Residential Only
House hacking is a way to satisfy your own housing needs and be a real estate investor. You buy a property to live in that is bigger than you need and rent out the rest, allowing you to live rent free or at a reduced cost. Here are two examples:
You buy a four-bedroom house with one kitchen and 3-4 bathrooms. You live in the master bedroom with a private bathroom and rent out the other rooms. You all share the living room, kitchen, and laundry room. Maybe you rent the rooms to friends as you will be sharing a lot of space together.
You buy a duplex. You live in one unit and rent out the other. Your tenant lives in their own unit. There is no shared space.
House hacking is a creative way to become a real estate investor. Lenders view 1-4 unit residential as personal home loans, which can be easier to qualify for if you are a first time investor.
However, you have to be comfortable living with or near your tenants. This can get messy, especially if living with friends. Example: your buddy loses his job and can’t pay the rent. Are you willing to kick him out? Just plan ahead for what you are willing and not willing to do.
Understanding Strategy
Now that we have discussed five strategies, let’s break down the characteristics that (a) determine the risk associated with an investment and (b) determine your fit for each strategy.
Risk Associated with an Investment
To oversimplify, there are four main risks associated with a real estate investment:
Occupancy: is the property leased? How soon do the leases expire?
Rent vs Market: are the existing tenants paying market rent? Is there an opportunity to increase the rent? What are the current and anticipated market conditions?
Property Condition: is the property old? Is there deferred maintenance? Are the units leasable as is or do they need to be cleaned up first?
Property Function: is the property functional as configured? Do the number of units needed to be increased or decreased?
Let’s combine these with the first three strategies (excluding development and house hacking):
Core/Turnkey: Low risk, Low return.
Occupied
Rent at or Near Market
Good Property Condition and Function
Light Rehab: Medium Risk, Medium Return.
Vacant or Occupied Short Term
Rent Below Market
Property Condition Can Be Improved
Property Functional As Is
Value Add: High Risk, High Return.
Vacant or Occupied Short Term
Rent Below Market
Property Condition and Property Function Can Be Improved
Your Fit for Each Strategy
Now let’s add in what is required for each relative to how it will impact you as an investor from a time and future dollar commitment standpoint.
Core/Turnkey: Low risk, Low return.
Most passive; minimal time commitment and ongoing capital investment.
Light Rehab: Medium Risk, Medium Return.
Active for focused periods of time; more passive after rehab; requires some investment of dollars and time after purchase.
Value Add: High Risk, High Return.
Very active for focused, extended periods of time; may be more passive after rehab; requires significant investment of dollars and time after purchase.
Development: Highest Risk, Highest Return.
Significantly time consuming for 2-3+ years; requires coordinating the efforts of many consultants and specialists; material capital commitment years before completion.
Very Important Side Note: Strategy is only one element of a real estate investment. The market you invest in will play a HUGE role in the success of the deal. Spend the time to research and understand the market before you make your first investment. Talk with brokers. Read research papers. Understand the major employers and drivers of the local economy.
My Strategy Evolution
Here’s how it evolved for me over the past 23 years of investing.
Stage I - Clueless to Strategy: I made an LP investment in a value add hotel deal. I had no idea there were different types of strategy or that I was taking on more risk than I realized. I was lucky it worked out.
Stage II - Value Add with Employer: I spent most of my career with a GP focused on value add industrial. By joining an established firm with leaders who understood value add investing, I was able to get paid to learn. When I made personal investments, it was mainly alongside seasoned investors who had “been there, done that”.
Stage III - Value Add as LP: In 2015, I started making LP investments with a multifamily GP focused on value add deals. I even spent two years working for the GP and learned the operational side of the multifamily business. Their leadership team had years of value add investing experience. They were able to minimize risk through their extensive track record.
Finding the Strategy That Fits You
So which is right for you?
If you are new to real estate investing, you don’t know what you don’t know.
Something that may look risk-free to you could be riskier than you think. Something that looks risky to you, could appear much less risky to a seasoned investor.
Unless you can work for an experienced GP and invest alongside them, I recommend starting simple with a core/turnkey or light rehab.
Get a few deals under your belt.
Make some mistakes and learn from them before you buy a value add deal.
Here’s a quick self-assessment guide. Ask yourself:
Time: Do I have time on evenings/weekends for 3-6 months?
If not, then consider a Core/Turnkey deal.
Capital: Can I set aside cash reserves for cost overruns and unexpected issues?
If not, then consider a Core/Turnkey or Light Rehab deal.
Experience: Have I completed 2+ deals through stabilization and/or sale?
If not, then consider starting with a Core/Turnkey or Light Rehab deal.
Tolerance: Can I sleep at night with a property that is filled with uncertainty?
If not, avoid Value Add and Development.
Be honest with yourself. Miscalculating risk and how you will handle it can turn your side hustle into a 20-40 hour per week commitment.
Investing takes time and patience.
You can always become a value add investor later down the road. Just recognize that you need to put in your reps with simpler deals first.
Learn the fundamentals of operating real estate: market analysis, the acquisition process, securing a loan, executing a business plan, property management, tenant relations, and property accounting.
Doing this on a simple, low-risk deal really has its benefit.
There are no shortcuts.
You have to put in the work.
Professor Bateman
Stop Chasing Every Deal: Why Successful Investors Pick a Niche
How to choose your asset class, geography, and strategy—and why focus beats FOMO
Here's an uncomfortable truth: most beginning real estate investors fail because they chase every shiny opportunity instead of focusing on one niche.
Yes, there will be times to veer from your niche temporarily or even pivot entirely, but keeping focus will yield the best results in the long run.
Successful investing in real estate requires building expertise. Expertise is MUCH easier to build if you focus on a specific niche.
Why is this true?
Why not just look at a whole variety of opportunities and pick the ones with the best risk adjusted returns for you?
The answer: developing expertise takes focused repetition. Focused repetition is only possible if you pick a niche.
Let me explain.
What is a Niche?
In reference to real estate investing, let’s define a “niche” as a combination of (a) how you are going to invest and (b) what you are going to invest in.
The “how” was discussed in detail in 5 Ways to Invest in Real Estate (From $60 to All-In). Here is a quick recap of the ways, from least time consuming to most time consuming:
Owning shares of a REIT.
Investing as a limited partner (LP).
Buying a property by yourself.
Buying a property with someone as equal partners.
Buying a property as the general partner and raising money from LPs.
The “what” is new to our discussion. It is made up of three components.
Asset Class: 1-4 unit residential, apartments, office, industrial, retail.
Geography: where you plan to invest.
Strategy: core/turnkey, light rehab, value add (or fix and flip), house hacking.
When you combine these combinations, there are literally 100’s of niches to choose from.
It may seem overwhelming.
Help!!!!
Don’t worry.
As with any big issue, the key is to break it down into parts.
For this discussion, let’s assume the “how” of your niche will be to buy the property by yourself. This will allow us to focus on the “what”. Even if you decide to invest with a partner (or raise money) or invest as an LP, the same principles will apply in thinking about the “what”.
Asset Class
Choosing an asset class is probably the most foundational decision you need to make. I discussed asset classes in detail in Asset Classes Explained: Industrial, Office, Retail, Multifamily, and 1-4 Unit Residential. Here’s a short recap:
Industrial: Simple to operate, low ongoing capital needs, good cash flow.
Office: Complicated to operate, high ongoing capital needs, challenging cash flow.
Retail: Reasonable to operate, moderate ongoing capital needs, good cash flow.
Multifamily/Apartments: Intensive to operate, varied ongoing capital needs, good cash flow.
1-4 Unit Residential: Easier than apartments to operate, varied ongoing capital needs, good but lumpy cash flow due to the limited number of tenants.
If you are just starting out and have more limited funds, the most accessible asset classes will be:
1-4 unit residential.
A small industrial property.
A small single-tenant retail property.
The reason to pick one asset class is because each type has its own nuances and characteristics. If you jump from type to type, you will never develop any expertise. Without expertise you will miss opportunities and misjudge risk.
Geography
Geography is just as it sounds: where are you going to invest? Think of it in terms of:
Region: example coastal markets or the sunbelt states or the midwest.
Markets: a specific area within a region. Example: Charlotte, NC.
Submarket: this gets even more specific. What micro areas do you like in your market?
You don’t have to start with a submarket specifically. For example, maybe you have $30,000 to invest. You are limited to lower cost markets and can’t afford coastal areas.
You might pick the midwest U.S. as your region and then focus on Detroit over time. As you learn more about Detroit, you could then pick the submarkets you like.
Remember, you don’t have to limit yourself to the market you live in. You can find a good broker and property manager in another market who will do all the work for you while you direct the overall strategy. See You Don’t Have to Do Everything Yourself: Building Your Real Estate Team.
It is OK to have multiple geographies to focus on. It just means more areas to keep up with. I recommend starting with one. Or doing some research on two to three with the goal of ultimately focusing on one.
Strategy
Strategy is the approach you are going to take to operating your property. We will explore this in detail next week. For now let’s start with the following options:
Core/Turnkey: low risk, low return. You buy a property that is well leased and maintained. There is minimal work to do.
Light Rehab: medium risk, medium return. There is some work to do, but it is mainly cosmetic (paint, carpet, clean up). If you do the work, you can increase the rent and value of the property.
Value Add: high risk, high return. There is a lot of work to do. The property might even be vacant. You will be repositioning it and taking on a lot of risk for superior returns. You will either find a tenant once the work is complete or sell it (fix and flip).
House Hacking: this option only applies to 1-4 residential. You will live in one unit (or room) of the property and rent out the other units (or rooms), allowing you to live rent free or at a reduced cost.
Each strategy has its own pros and cons. There is no right answer.
You can see that choosing the right one for you depends on the time you have and your tolerance for risk.
Now let's see how this works in practice. Here are four real-world niche examples that combine these elements differently.
Creating Your Niche: Putting It All Together
Option 1: Good for a W-2 employee with no spare time who wants passive income.
Asset Class: Retail
Geography: Pacific Northwest
Strategy: Turnkey
You decide to buy single tenant leased fast food buildings that are leased long-term (ex. 10+ years). The tenants are responsible for maintaining the buildings so there is very little work for you to do. You have always liked the Pacific Northwest because you grew up there and saw businesses like Amazon, Costco, and Microsoft drive the economy.
Option 2: Good for a W-2 employee with limited time who wants passive income.
Asset Class: 1-4 Unit Residential
Geography: Southeast U.S.
Strategy: Turnkey
You don’t have a ton of free time, so you want to buy turnkey assets that don’t need a lot of work. You live in a more expensive coastal market, but can’t afford to buy there so you find a good broker and property manager who will find and manage your future out-of-state properties that will be in a more affordable market in the southeast. You are starting with a one or two unit residential property because that is all you can afford. Over time, you hope to assemble a collection of duplexes and four-plexes.
Option 3: Good for someone with time to be more active in managing their investment.
Asset Class: Industrial
Geography: San Antonio, TX
Strategy: Light Rehab
You like the simplicity of industrial. You are targeting an older, well located building that needs to be repositioned with some paint and new signage. You like San Antonio because it is near the fast growing market of Austin.
Option 4: Good for someone ready to give their evenings and weekends to fixing up the property.
Asset Class: 4 Unit Residential
Geography: Los Angeles, CA
Strategy: Value Add
You have lived in LA all your life and have seen that there is never enough housing. You have researched the rent control laws of California and understand how to navigate them. You scrape together all the money you have to buy a 50+ year old four-plex in West Los Angeles that needs a major rehab. You plan to hold this property forever and pass it on to your children.
Why Having a Niche Matters
As you can see, these four options are very different strategies.
Finding a property to invest in takes work. You will likely have to look at 10-100+ potential properties before you find one to buy.
It is through this repetition that you start to (a) learn more about your niche and (b) see the one or two properties that are a better deal than the others.
Without this level of focus and repetition, you are like an athlete playing many different sports. You may be adequate at each, but you will never develop expertise.
The most successful investors focus and become experts in their niche. If they have multiple niches it is because they mastered the first and expanded into additional niches.
How to Choose Your Niche: A Simple Framework
Ask yourself three questions:
Money: How much capital do I have to invest? (This limits your asset class and geography options)
Time: How much ongoing time can I dedicate? (This determines your strategy)
Interest: What excites me? (You are more likely to stick with what you find interesting)
Closing Thoughts
There are at least two ways to look at the concept of having a niche.
Feeling Constrained
Feeling a Sense of Freedom
Some will feel constrained. They are the type who have FOMO, feeling there are always better opportunities that they are missing out on. They hear of someone making a successful investment outside of their niche. They decide to pivot. 18 months and five pivots later, they have either failed to make an investment or worse, made an impulsive investment decision that may or may not work out.
Distraction is the enemy of progress.
I encourage you to view it from the other perspective, as freedom. By focusing on a niche you will have freedom.
Freedom to develop expertise.
Freedom to focus.
Freedom to ignore temptations outside of your niche.
Once you build expertise and momentum in your niche, you can expand and add to it.
I didn’t start with expertise in multiple asset classes, markets, and strategies. I developed and grew expertise over my 20+ year career in real estate and being an investor.
But ask me about a market I don’t have any experience in (ex. Miami or New Jersey) and I will acknowledge I don’t know much.
This is fine. Humility is a good thing.
What you don’t want to do is be an investor who makes bets without doing the research or having focus. You won’t be an expert on your first deal, but you will build momentum over time if you stick to a niche.
My Niche Evolution
Here’s how it evolved for me over the past 23 years of investing.
Stage I - No Niche: I made an LP investment in a hotel in Los Angeles without any investment focus. I made this investment because the GP was (and still is) my friend. Luckily, it worked out.
Stage II - Western U.S., Value Add, Industrial: For the 20 years I was at Westcore, we primarily focused on this niche. Yes we did some retail and office deals, but we were primarily focused on industrial. After 20 years we actively expanded our geography to Texas and further east while maintaining a focus on value add industrial.
Stage III - Western U.S., Value Add, Multifamily as an LP: In 2015, I started making LP investments with a multifamily GP. I actively pursued this focus to build up passive income and diversify outside of industrial. I even spent two years working for the GP and learned the operational side of the multifamily business.
In stage I, I was clueless. I was lucky to invest with a GP who was very capable and honest.
My time at Westcore (stage II) allowed me to develop real expertise in a niche.
It was only after 10+ years at Westcore that I added an additional niche as a multifamily LP investor (stage III). The expansion came after mastering the previous niche - not before.
Today, my personal investment portfolio is still industrial and multifamily with strategies I understand and in markets I know well. These are my niches. What happens when I see an office deal? I am a quick no.
Focus doesn’t mean you never change. It means you build expertise before expanding your focus.
Do you have a story you want to share of sticking to a niche or veering outside of it? Email me at bateman@creprofessor.org. I read every email and would enjoy hearing your story.
Professor BatemanHere's an uncomfortable truth: most beginning real estate investors fail because they chase every shiny opportunity instead of focusing on one niche.
Yes, there will be times to veer from your niche temporarily or even pivot entirely, but keeping focus will yield the best results in the long run.
Successful investing in real estate requires building expertise. Expertise is MUCH easier to build if you focus on a specific niche.
Why is this true?
Why not just look at a whole variety of opportunities and pick the ones with the best risk adjusted returns for you?
The answer: developing expertise takes focused repetition. Focused repetition is only possible if you pick a niche.
Let me explain.
What is a Niche?
In reference to real estate investing, let’s define a “niche” as a combination of (a) how you are going to invest and (b) what you are going to invest in.
The “how” was discussed in detail in 5 Ways to Invest in Real Estate (From $60 to All-In). Here is a quick recap of the ways, from least time consuming to most time consuming:
Owning shares of a REIT.
Investing as a limited partner (LP).
Buying a property by yourself.
Buying a property with someone as equal partners.
Buying a property as the general partner and raising money from LPs.
The “what” is new to our discussion. It is made up of three components.
Asset Class: 1-4 unit residential, apartments, office, industrial, retail.
Geography: where you plan to invest.
Strategy: core/turnkey, light rehab, value add (or fix and flip), house hacking.
When you combine these combinations, there are literally 100’s of niches to choose from.
It may seem overwhelming.
Help!!!!
Don’t worry.
As with any big issue, the key is to break it down into parts.
For this discussion, let’s assume the “how” of your niche will be to buy the property by yourself. This will allow us to focus on the “what”. Even if you decide to invest with a partner (or raise money) or invest as an LP, the same principles will apply in thinking about the “what”.
Asset Class
Choosing an asset class is probably the most foundational decision you need to make. I discussed asset classes in detail in Asset Classes Explained: Industrial, Office, Retail, Multifamily, and 1-4 Unit Residential. Here’s a short recap:
Industrial: Simple to operate, low ongoing capital needs, good cash flow.
Office: Complicated to operate, high ongoing capital needs, challenging cash flow.
Retail: Reasonable to operate, moderate ongoing capital needs, good cash flow.
Multifamily/Apartments: Intensive to operate, varied ongoing capital needs, good cash flow.
1-4 Unit Residential: Easier than apartments to operate, varied ongoing capital needs, good but lumpy cash flow due to the limited number of tenants.
If you are just starting out and have more limited funds, the most accessible asset classes will be:
1-4 unit residential.
A small industrial property.
A small single-tenant retail property.
The reason to pick one asset class is because each type has its own nuances and characteristics. If you jump from type to type, you will never develop any expertise. Without expertise you will miss opportunities and misjudge risk.
Geography
Geography is just as it sounds: where are you going to invest? Think of it in terms of:
Region: example coastal markets or the sunbelt states or the midwest.
Markets: a specific area within a region. Example: Charlotte, NC.
Submarket: this gets even more specific. What micro areas do you like in your market?
You don’t have to start with a submarket specifically. For example, maybe you have $30,000 to invest. You are limited to lower cost markets and can’t afford coastal areas.
You might pick the midwest U.S. as your region and then focus on Detroit over time. As you learn more about Detroit, you could then pick the submarkets you like.
Remember, you don’t have to limit yourself to the market you live in. You can find a good broker and property manager in another market who will do all the work for you while you direct the overall strategy. See You Don’t Have to Do Everything Yourself: Building Your Real Estate Team.
It is OK to have multiple geographies to focus on. It just means more areas to keep up with. I recommend starting with one. Or doing some research on two to three with the goal of ultimately focusing on one.
Strategy
Strategy is the approach you are going to take to operating your property. We will explore this in detail next week. For now let’s start with the following options:
Core/Turnkey: low risk, low return. You buy a property that is well leased and maintained. There is minimal work to do.
Light Rehab: medium risk, medium return. There is some work to do, but it is mainly cosmetic (paint, carpet, clean up). If you do the work, you can increase the rent and value of the property.
Value Add: high risk, high return. There is a lot of work to do. The property might even be vacant. You will be repositioning it and taking on a lot of risk for superior returns. You will either find a tenant once the work is complete or sell it (fix and flip).
House Hacking: this option only applies to 1-4 residential. You will live in one unit (or room) of the property and rent out the other units (or rooms), allowing you to live rent free or at a reduced cost.
Each strategy has its own pros and cons. There is no right answer.
You can see that choosing the right one for you depends on the time you have and your tolerance for risk.
Now let's see how this works in practice. Here are four real-world niche examples that combine these elements differently.
Creating Your Niche: Putting It All Together
Option 1: Good for a W-2 employee with no spare time who wants passive income.
Asset Class: Retail
Geography: Pacific Northwest
Strategy: Turnkey
You decide to buy single tenant leased fast food buildings that are leased long-term (ex. 10+ years). The tenants are responsible for maintaining the buildings so there is very little work for you to do. You have always liked the Pacific Northwest because you grew up there and saw businesses like Amazon, Costco, and Microsoft drive the economy.
Option 2: Good for a W-2 employee with limited time who wants passive income.
Asset Class: 1-4 Unit Residential
Geography: Southeast U.S.
Strategy: Turnkey
You don’t have a ton of free time, so you want to buy turnkey assets that don’t need a lot of work. You live in a more expensive coastal market, but can’t afford to buy there so you find a good broker and property manager who will find and manage your future out-of-state properties that will be in a more affordable market in the southeast. You are starting with a one or two unit residential property because that is all you can afford. Over time, you hope to assemble a collection of duplexes and four-plexes.
Option 3: Good for someone with time to be more active in managing their investment.
Asset Class: Industrial
Geography: San Antonio, TX
Strategy: Light Rehab
You like the simplicity of industrial. You are targeting an older, well located building that needs to be repositioned with some paint and new signage. You like San Antonio because it is near the fast growing market of Austin.
Option 4: Good for someone ready to give their evenings and weekends to fixing up the property.
Asset Class: 4 Unit Residential
Geography: Los Angeles, CA
Strategy: Value Add
You have lived in LA all your life and have seen that there is never enough housing. You have researched the rent control laws of California and understand how to navigate them. You scrape together all the money you have to buy a 50+ year old four-plex in West Los Angeles that needs a major rehab. You plan to hold this property forever and pass it on to your children.
Why Having a Niche Matters
As you can see, these four options are very different strategies.
Finding a property to invest in takes work. You will likely have to look at 10-100+ potential properties before you find one to buy.
It is through this repetition that you start to (a) learn more about your niche and (b) see the one or two properties that are a better deal than the others.
Without this level of focus and repetition, you are like an athlete playing many different sports. You may be adequate at each, but you will never develop expertise.
The most successful investors focus and become experts in their niche. If they have multiple niches it is because they mastered the first and expanded into additional niches.
How to Choose Your Niche: A Simple Framework
Ask yourself three questions:
Money: How much capital do I have to invest? (This limits your asset class and geography options)
Time: How much ongoing time can I dedicate? (This determines your strategy)
Interest: What excites me? (You are more likely to stick with what you find interesting)
Closing Thoughts
There are at least two ways to look at the concept of having a niche.
Feeling Constrained
Feeling a Sense of Freedom
Some will feel constrained. They are the type who have FOMO, feeling there are always better opportunities that they are missing out on. They hear of someone making a successful investment outside of their niche. They decide to pivot. 18 months and five pivots later, they have either failed to make an investment or worse, made an impulsive investment decision that may or may not work out.
Distraction is the enemy of progress.
I encourage you to view it from the other perspective, as freedom. By focusing on a niche you will have freedom.
Freedom to develop expertise.
Freedom to focus.
Freedom to ignore temptations outside of your niche.
Once you build expertise and momentum in your niche, you can expand and add to it.
I didn’t start with expertise in multiple asset classes, markets, and strategies. I developed and grew expertise over my 20+ year career in real estate and being an investor.
But ask me about a market I don’t have any experience in (ex. Miami or New Jersey) and I will acknowledge I don’t know much.
This is fine. Humility is a good thing.
What you don’t want to do is be an investor who makes bets without doing the research or having focus. You won’t be an expert on your first deal, but you will build momentum over time if you stick to a niche.
My Niche Evolution
Here’s how it evolved for me over the past 23 years of investing.
Stage I - No Niche: I made an LP investment in a hotel in Los Angeles without any investment focus. I made this investment because the GP was (and still is) my friend. Luckily, it worked out.
Stage II - Western U.S., Value Add, Industrial: For the 20 years I was at Westcore, we primarily focused on this niche. Yes we did some retail and office deals, but we were primarily focused on industrial. After 20 years we actively expanded our geography to Texas and further east while maintaining a focus on value add industrial.
Stage III - Western U.S., Value Add, Multifamily as an LP: In 2015, I started making LP investments with a multifamily GP. I actively pursued this focus to build up passive income and diversify outside of industrial. I even spent two years working for the GP and learned the operational side of the multifamily business.
In stage I, I was clueless. I was lucky to invest with a GP who was very capable and honest.
My time at Westcore (stage II) allowed me to develop real expertise in a niche.
It was only after 10+ years at Westcore that I added an additional niche as a multifamily LP investor (stage III). The expansion came after mastering the previous niche - not before.
Today, my personal investment portfolio is still industrial and multifamily with strategies I understand and in markets I know well. These are my niches. What happens when I see an office deal? I am a quick no.
Focus doesn’t mean you never change. It means you build expertise before expanding your focus.
Do you have a story you want to share of sticking to a niche or veering outside of it? Email me at bateman@creprofessor.org. I read every email and would enjoy hearing your story.
Professor Bateman
You Don’t Have to Do Everything Yourself: Building Your Real Estate Team
How to assemble the right specialists so you can focus on what matters
In my previous post 5 Ways to Invest in Real Estate (From $60 to All-In), I discuss the passive and active ways to invest in real estate. A quick overview:
Passive: buying REIT shares or investing as a limited partner (LP) with someone that puts together and manages the investment - the general partner (GP).
Active: buying a property on your own, with a partner, or by raising money from multiple LPs.
Both are good ways to invest and, as with almost everything in life, they each have their trade offs.
Passive Investing
Passive investing requires minimal effort. Someone else does the work. Once you make the investment, you don’t have to do much. Read the quarterly reports. File your tax return. In exchange, you have little control and pay the REIT or GP to run the investment (we will get into the details of fees and promotes another week).
Active Investing
Active investing gives you more control and allows you to collect fees and promote. In exchange, you have to do all the work.
Unless you are part of a company that acts as the GP, this can be an overwhelming amount of work. Just like a business owner, you have to wear many hats and deal with a vast variety of issues.
The Many Demands of Owning a Real Estate Investment
Regardless of the type of investment property you buy, you will be faced with many, many issues as a real estate owner. Calls from tenants with plumbing leaks, tenants not paying rent, insurance policies, loan expirations, vendors and contractors, tax returns…the list is seemingly endless.
This can be daunting as you think of making this your side-hustle.
Don’t worry.
There are ways for you to handle this and keep your sanity.
The key is to assemble the right team.
And for those who want to go all-in and create a company, this will be an essential guide of who you need as your employees and advisors.
Let’s dig in.
An Industry of Specialists
The real estate industry is full of people that specialize in various niches within the industry. I break down the industry in my discussion on CRE 101.
The groups in green have a financial interest in a property. Said another way, they write a check to invest.
The groups in blue provide services to the groups in green for a fee. Sometimes the fee is one time. Sometimes it is on a monthly basis. Sometimes the owner creates a company and hires people in the blue group to be their employees. Example: property management and accounting.
Each group is made up of people that have chosen to specialize in their given niche based on their skills and interests.
Be the Leader. Don’t Do Everything Yourself.
As the owner of a property, it is up to you to decide what you want to do yourself and what you want to pay a specialist to do. Do you want to:
Get calls from tenants or pay a property manager to handle this?
Do the accounting/bookkeeping or hire an accountant?
Lease the vacant space or hire a broker?
Fix the leaky faucet or hire a handyman?
Oversee the construction or hire a general contractor?
Everyone is different. You need to decide what works for you.
For the property I own with a partner, I pay a property manager to interface with the tenants, manage the vendors, and do the property accounting.
But when it came to replacing the roof a few years ago, I decided to work directly with the roof company as it would only be done every 10 years and it is so critical to the performance of the building.
So who does what and how do they get paid?
Let’s break it down.
Here are the key roles you need to understand, roughly in the order you'll need them:
Mentor
Role: A mentor is someone who (a) has already achieved what you want to achieve and (b) is interested in helping you. They are your vision of yourself in 5-10 years. Your mentor was helped by others in their journey. They want to pay it forward. They will be your guide, especially in challenging situations.
Compensation: None. You shouldn’t need to pay a mentor. This will only work if you demonstrate you are someone worth the mentor spending time on.
How to Find One: Ask around. Contact someone on LinkedIn. Meet someone at an industry event. Be specific about what you want to learn and respect their time. Come prepared with questions and updates on your progress.
Business Partner
Role: They are your investing partner. You do the deal together. You keep each other accountable and share the ups and downs.
Compensation: None. You each invest in the property as partners.
How to Find One: Only do a deal with someone you know and trust. It is like a marriage. See Option 4 in 5 Ways to Invest in Real Estate (From $60 to All-In).
Acquisition Broker / Realtor / Real Estate Agent
Role: They find the property for you. The good ones help you navigate the acquisition process, from the purchase contract to due diligence to escrow and title to the loan and to closing. They have been there, done that. They are licensed by the state they reside in. Note that most of the time they are selling the property on behalf of the owner. Make sure you ask who they are representing. They will either be representing the seller or both of you. Either is fine. Just know that if they are only representing the seller, they may be giving you an (overly) optimistic vision of the market conditions. Make sure you ask the opinion of other brokers not part of this transaction.
Compensation: Commission. They earn 1-6% of the purchase price, depending on the size of the deal and asset class. Example: $3M x 6% = $180,000. The commission is paid at closing and typically paid by the seller. You pay nothing as the buyer unless this is pre-agreed upon by you and the broker.
How to Find One: Check loopnet.com and other websites to see properties for sale. They will list the broker. Contact the broker and tell them what you are looking for. There are national brokerage companies that specialize in industrial, retail, office, and larger apartment buildings (CBRE, JLL, Newmark, Marcus & Millichap, Cushman & Wakefield, Voit, and Lee & Associates). Brokers that specialize in 1-4 unit residential tend to be more locally focused. If the latter, you want to find one that specializes in investment properties, not traditional home sales.
Leasing Broker
Role: Same as an acquisition broker, except they specialize in leasing. This is typically only applicable to industrial, retail, and office. Property management companies tend to do the leasing for apartments and 1-4 unit residential.
Compensation: Commission.
How to Find One: Through the acquisition broker.
Property Manager and Property Accountant
Role: Manages the day-to-day of a property, from interfacing with tenants to managing vendors and maintenance needs to overseeing smaller construction jobs. This role is critical to running a property as well as being the most time consuming on an ongoing basis. They also provide accounting to track the monthly financial performance of a property.
Compensation: A percentage of monthly revenue with a minimum or it could be a flat fee. Example 3-5% of monthly revenue with a $1,000 per month minimum. There could also be additional charges for overseeing construction and renewing tenants.
How to Find One: Through the acquisition broker.
Lender / Loan Broker
Role: The lender provides the debt to help you buy the property. A loan broker helps you find the right lender for you by marketing the property to many different lenders.
Compensation: The lender may charge you not only a fee for the loan at closing (example 1% of the loan amount), but will also pass through the amounts they pay to their attorneys and due diligence consultants. The loan broker is paid just like an acquisition broker (example 1% of the loan amount).
How to Find One: Through the acquisition broker.
Insurance Broker / Agent
Role: Connects you with the right insurance carrier for you to get insurance to protect you against costs related to property damage (property insurance) and being sued (liability insurance).
Compensation: Commission that is imbedded into the cost you pay the insurance carrier.
How to Find One: Through the acquisition broker.
Handyman or Contractor
Role: Handles repairs and construction, ranging from fixing a leaking faucet to painting a vacant unit to replacing a roof.
Compensation: Fixed or percentage fee.
How to Find One: Through the property manager.
Escrow & Title
Role: An escrow agent is the “referee” between the buyer and the seller. They make sure each party follows what is required under the purchase and sale agreement as well as manage the exchange of money. Title makes sure that what everyone thinks is being bought and sold is actually being bought and sold. They also provide title insurance to protect against future issues.
Compensation: One time fees.
How to Find One: Through the acquisition broker.
Attorney
Role: Advises you on legal issues. On larger deals (ex. $5M+), attorneys are used to negotiate purchase and sale agreements, loan agreements, and partnerships agreements involving GPs and LPs. They are also used on larger leases. Some owners won’t do a deal without advice from an attorney. Others rely on standard form documents without using an attorney (Example: AIA Contracts).
Compensation: Paid based on an hourly rate.
How to Find One: Through the acquisition broker or property manager.
Tax Accountant
Role: Prepares your tax return and advises on tax strategy. Remember, the property manager only does monthly property accounting that tells you about the monthly performance of your property (income statement, balance sheet, and cash flow). This is different from a tax return you file with the IRS.
Compensation: Paid based on an hourly rate.
How to Find One: Through the acquisition broker or property manager.
Summary
That was a lot to cover. Let’s try to make it more digestible by providing two examples of how you could approach this.
Option 1: Keep it Simple - Outsource Everything
Find a broker that works for a company that also does property management, accounting, and construction management. Even brokers that work for companies without these services know of other companies that can provide them.
A good broker will help you find a property to invest in and bring together the team to both help you buy it and run it once you own the property.
Once you own it, be clear on what you want to approve and what you are delegating to the property management team. Example: the property manager has discretion to proceed with all maintenance issues < $250 without owner’s approval. Increase or decrease your delegation threshold over time. Dive into specific issues if needed. And be willing to change teams if the existing property manager is not working for you.
Option 2: Active Control
Do any or all of the above functions yourself. You will still likely want to use a broker, but everything else you can do yourself.
You will save money but you will pay for it with your time and energy. You will experience first hand what it is like to get an emergency call from a tenant in the middle of the night or while you are on vacation.
It is not for everyone, but it does have the advantage of teaching you what it is like to really run a property.
You Can Change Your Approach Over Time
Remember that none of this needs to be permanent. You could start with the active approach and then switch to the outsource approach.
This is what I did with my industrial property.
Active: I did the property management and accounting myself for a year and then decided this was not for me.
Hybrid: I then hired a group to do the property management only while I continued with the property accounting.
Outsource: Finally, I decided they did not manage the property in the way I wanted it managed, so I hired a new property manager and increased the scope so that they did the property accounting as well. They have been excellent. I happily pay them their monthly fee.
There is no universal right answer.
Be a student of yourself and observe what works for you.
Professor Bateman
Asset Classes Explained: Industrial, Office, Retail, Multifamily, and 1-4 Unit Residential
Which real estate type matches your investment goals, time, and capital?
It’s funny. The term “commercial” is my least favorite way to describe a particular individual property, yet it is the most accurate to describe the industry as a whole.
In my experience, “commercial” real estate is any property that is operated as an investment; where the business plan is to make money.
The home you live in is not commercial real estate.
The house you rent out for income is commercial real estate.
There are many types of commercial real estate known as “asset classes”.
Understanding how they differ is critical to becoming a successful real estate investor. In my last newsletter (5 Ways to Invest in Real Estate), I discussed the “how”. Now we are describing the “what” you can invest in.
I’ve invested in six of these over the past 20+ years and talked with investors who have focused on the others.
By the end of this newsletter, you’ll know which asset class aligns best with your goals, risk tolerance, and available time.
Let’s dig in.
The Major Asset Classes
Industrial
Office
Retail
Multifamily aka Apartments
1-4 Unit Residential: single-family home rentals, duplexes, triplexes, fourplexes.
Other: Medical Office, Shopping Malls, Biotech, Data Centers, Hotels, Self-Storage, Industrial Outdoor Storage (IOS)
Each of these has different characteristics in terms of:
Physical Characteristics: What they look like physically and how they function.
Tenants: Which tenants they attract and what those tenants are looking for.
Operational Complexity: The demands on owner to operate them.
Capital Needs: The ongoing capital they require to operate.
Lease Structure: Whether the tenant pays anything in addition to rent.
Investment Profile: Cash flow and investment characteristics.
Summary: key takeaways.
We are going to cover a lot of information here. See below for a list of the main asset classes with a “cheat sheet” of their characteristics added.
Industrial: Simple to operate, low capital needs, good cash flow.
Office: Complicated to operate, high capital needs, challenging cash flow.
Retail: Reasonable to operate, modest capital needs, good cash flow.
Multifamily: Intensive to operate, varied capital needs, good cash flow.
1-4 Unit Residential: Easier than apartments to operate, varied capital needs, good but lumpy cash flow due to the limited number of tenants.
The goal is to find the right fit for you as an investor.
Quick Note: I had to err on the side of oversimplifying to summarize all of this information. Those of you who have spent years focused on one asset class may find I missed tons of the nuances of that asset.
I would probably agree with you.
Think of this as the starter to see where you want to dig in.
Industrial
Photo by Point3D Commercial Imaging Ltd. on Unsplash
Physical Characteristics
Industrial buildings are generally single story warehouse buildings that have 5-50% of the interior of each individual suite built out as office. Buildings and suite sizes can range from 5,000 square feet (SF) to 500,000+ SF. Sometimes one tenant occupies the entire building. Sometimes it is broken up into smaller suites. The ceiling heights can range from 12’ to 40’. They normally have large warehouse doors for backing large trucks into to load and unload products.
Tenants
Tenants that lease industrial buildings are typically storing products, manufacturing, conducting e-commerce, or running a small business that requires storage of parts (ex. plumbing, HVAC).
Operational Complexity
Industrial buildings are relatively easy to operate, particularly the larger buildings. The larger the tenant (by SF), the more self-sufficient they tend to be. Most leases require the tenants to handle everything inside their suite (ex. light bulbs and HVAC).
Capital Needs
Industrial buildings don’t require much capital to operate. The tenant improvements (costs to fix up the suite for the next tenant) tend to be relatively low due to the low percentage of office. The most expensive thing to replace on an industrial building is a roof.
Lease Structure
Most industrial leases are 3-10 years in length and triple-net (NNN). NNN means that in addition to the tenant paying base rent, it also pays its share (defined by % of total SF) of the expenses to operate the building such as maintenance contracts, insurance, and property tax. We will get into NNN more in another newsletter.
Investment Profile
The combination of the duration of the leases, the NNN lease structure, and the low capital needs make industrial a good asset for cash flow and an attractive one for investors.
Summary
Simple to operate, low capital needs, good cash flow. I am a big fan of industrial.
Office
Photo by Rahul Bhogal on Unsplash
Physical Characteristics
Office buildings are generally multi-story buildings with the interior built out for knowledge workers. You have probably been in one. They tend to be broken up into smaller suites ranging from 1,500 SF to 5,000 SF, although some suites can be much bigger.
Tenants
Tenants that lease office buildings are made up of knowledge workers who sit at desks on computers, meet in conference rooms, and congregate around a water cooler to chat. Think of the show “Suits”, the drama that takes place in the office of a law firm.
Operational Complexity
Office is demanding to operate. Not only do tenants expect the owner to change lightbulbs and fix the HVAC in their suite, but there are also major building systems to be maintained, repaired and replaced: elevators, glass exteriors, centralized HVAC systems, and other systems.
Capital Needs
Office buildings are capital pigs: they constantly need money. To lease up an office building for the first time, the owner needs to invest $100+ per square foot (psf) in tenant improvements (TIs) to do 5-10 year leases. At the end of these leases, the next tenant likely wants a different build out, requiring $25-50 psf in new TIs.
Then there are the building systems, which last for about 20 years if well maintained. Replacing an elevator or HVAC system can cost millions in an office high-rise.
Can you tell I am not really a fan of office? I was the asset manager on a suburban office portfolio for years and was constantly amazed by how much we had to spend to get a tenant in our buildings (even on renewals). Proceed with caution.
Lease Structure
This varies from market to market. Some are NNN like industrial buildings. Some are what’s known as a “base year” structure where the tenant only pays their share of increases in operating expenses. Again, don’t worry about this for now.
Investment Profile
I like to think of office as a trading asset. Once the tenants are in place and the rent roll is stable, it can be sold as a good value. But the high ongoing capital needs make it a challenging asset for cash flow.
Summary
Complicated to operate, high capital needs, challenging cash flow. I am unlikely to ever invest in office again.
Retail
Physical Characteristics
Ever been to a grocery store, restaurant, or a coffee shop? Then you have experienced retail. It could be a grocery anchored shopping center like the one in the picture above, or it could be an indoor mall. Suite sizes range from 1,000 SF to 50,000+ SF. It is where you go to buy goods and services.
Tenants
Tenants that lease retail buildings sell goods and services. Examples include: grocery and drug stores, fitness centers, restaurants, clothing stores and general retailers.
Operational Complexity
Retail can be demanding to operate, but for different reasons than office. It is similar to industrial in that most leases require the tenants to handle everything inside their suite (ex. light bulbs and HVAC).
The more challenging part comes with many of the tenants being smaller with limited credit. Owners are constantly managing through tenants struggling to pay rent. There is also an art to creating the right tenant mix that is synergistic and helps increase each tenant’s sales. The right anchor can make or break the whole retail center.
Capital Needs
If we think of a grocery anchored shopping center, capital needs are fairly reasonable. More than industrial, but less than office. Tenants generally need a rectangular box to outfit with their furniture, fixture, and equipment (FF&E). Capital requirements would be much more for a mall that has elevators, escalators, and even HVAC.
Lease Structure
Most are NNN, similar to industrial.
Investment Profile
Retail can be a good cash flowing asset. The performance is highly contingent on the anchor tenant(s). They are the main draw to bring in shoppers. If the anchor vacates, the smaller tenants will struggle.
Summary
Reasonable to operate, modest capital needs, good cash flow.
Multifamily aka Apartments
Physical Characteristics
As you read this newsletter, you may be sitting in your apartment. They are where so many of us live. These are typically built out with a kitchen, bathroom, living room, and one or more bedrooms. They have shared walls and often include common area amenities such as pools, gyms, and dog parks. They are in suburban locations like the picture above, or can be built as high-rises in urban areas.
Tenants
You and me.
Operational Complexity
Multifamily is probably the most complicated asset to operate. Tenants live in them 24/7, not just during business hours. Leases are 6-12 months long, so tenants are constantly moving in and out. Kitchen fires and other events happen all the time.
Be kind to your apartment property manager. It is a very tough job.
Capital Needs
They can be minimal or extensive, depending on how the owner chooses to operate. The floor plans and interior build outs don’t change from tenant to tenant as they do in office. Owners may choose to paint and carpet or refresh a kitchen or bath, but they rarely reconfigure a floor plan.
However, the volume and coming and going of tenants beats up the common areas, which can require constant maintenance.
Lease Structure
To oversimplify, multifamily leases are “gross” in structure. Tenants pay the rent and none of the operating expenses. But as those of you who have lived in apartments know, there are often additional charges such as internet, trash, and utilities.
Investment Profile
The multi-tenant nature of multifamily can be magic for steady cash flow. Most owners of 100+ unit multifamily have a target occupancy (ex. 95%) and adjust the rent each day to hit that target.
Summary
Intensive to operate, varied capital needs, good cash flow. I am a big fan of apartments as an LP investor. I think it is an excellent option for cash flow.
1-4 Unit Residential: Single-family Home Rentals, Duplexes, Triplexes, Fourplexes
Photo by Ferdinand Asakome on Unsplash
Physical Characteristics
Duplexes, Triplexes, and Fourplexes are 2, 3, and 4 unit buildings similar to apartments without the common areas amenities. Single-family home rentals are houses that are rented out to a tenant by the homeowner.
Tenants
You and me.
Operational Complexity
Same as apartments, without the common area amenities.
Capital Needs
Same as apartments, without the common area amenities.
Lease Structure
Same as apartments.
Investment Profile
Same as apartments, without the ability to set a target occupancy because of the limited number of tenants.
Summary
Easier than apartments to operate, varied capital needs, good but lumpy cash flow due to the limited number of tenants.
This could be your on-ramp to real estate investing. Here’s why I break it out as its own asset class.
It is much more accessible to individual investors with limited funds. One can buy a single-family home to rent for less than $100,000 in some markets.
If a building is four units or less, lenders view it as a personal loan. They will evaluate your personal credit as opposed to calculating the cash flow on the property. This can be helpful if you are just starting out.
If you want to start investing in properties on your own in an active way (as opposed to as an LP), this will likely be the most realistic path for you.
Other: Medical Office, Shopping Malls, Biotech, Data Centers, Hotels, Self-Storage, Industrial Outdoor Storage (IOS)
As the newsletter is already fairly long, I will give a brief description of these “specialty” assets.
Medical Office: similar to office, but for medical professionals (ex. dentist). TIs are even higher.
Shopping Malls: complicated to operate, high capital needs, challenging cash flow.
Biotech: similar to office, but for the biotech industry. TIs are veryhigh due to the lab build outs.
Data Centers: think of a warehouse full of computer servers. High power and cooling needs. Very expensive.
Hotels: imagine an apartment where the tenants only stay for 1-3 nights at a time and the owner provides cleaning and room service. This is a hotel. It is more like running an operating business than a real estate investment. I have two LP investments in hotels, but I recognize that operating one as a GP would require a tremendous amount of time and focus.
Self-Storage: very small, open industrial suites for storage leased 1-12 months at a time.
Industrial Outdoor Storage (IOS): land leased to tenants to store products.
Summary
Wow! That was a lot to cover.
Is your head spinning?
Don’t worry. There will be no tests.
All you need to do is pick the one or two that you want to explore:
Industrial: Simple to operate, low capital needs, good cash flow.
Office: Complicated to operate, high capital needs, challenging cash flow.
Retail: Reasonable to operate, modest capital needs, good cash flow.
Multifamily: Intensive to operate, varied capital needs, good cash flow.
1-4 Unit Residential: Easier than apartments to operate, varied capital needs, good but lumpy cash flow due to the limited number of tenants.
Intimidated by the operational intensity of any of these? No problem.
Invest in a REIT or as an LP.
If you are just getting started, I recommend you pick a niche that works for you. It would be a combination of:
Asset class.
Geography.
Investment method (REIT, LP, self, partnership, or GP as discussed last week).
Successful real investing requires focus.
Distraction is the enemy of progress.
Use the guide to narrow your focus.
Pick one asset class. Learn everything you can about it. Make your first investment and you will learn so much more.
Your needs will evolve over time. I started with a hotel, then focused on industrial, office and retail, and eventually made my way to multifamily.
Now most of my investments are in industrial and multifamily.
Success requires focus. Diversification can come later.
Email me at bateman@creprofessor.org to tell me which asset class resonates with you and why. I read every response.
Good luck!
Professor Bateman
Cap Rates: The Simple Math of Real Estate Investing
Cap Rate - this is probably the first and most fundamental concept to understand as a real estate investor. You may have heard someone say something like, “I bought the property for an 8% cap rate and sold it for a 5% cap rate” and found yourself nodding but on the inside you had no clue what this meant.
Don’t worry! Like most of real estate, it sounds complicated but it’s actually straightforward once you understand the jargon. (Side note, this is true for many things in life.)
Cap rates are the simple math that drive so much of real estate analysis. And fortunately you don’t need to be a “math” person to understand it. You learned all you need in Algebra I. It can literally be done on the back of a napkin.
Now that I have hopefully eased the concerns of all the math haters, let’s dig in.
Cap Rate is a commercial real estate term. It is short for “capitalization rate”. It is often used interchangeably with “Return on Costs”. Both refer to the investor’s annual return (example 5% per year) on their investment. It changes, and hopefully grows, over time.
Cap rates are also the key method through which real estate investments are valued.
Cap Rate = Net Operating Income Divided by Cost
Mathematically, it is the “net operating income” (NOI) divided by “cost”. Note that NOI changes over time; even cost can grow over time as you invest in renovations. NOI is:
NOI = Revenue - Operating Expenses.
It loosely reflects the cash flow from a property without debt. Note that operating expenses do not include interest you pay your lender or capital expenses (renovations). Don’t worry about this for now.
Cost is what you pay to purchase the real estate, also referred to as your purchase price. But…your costs can grow over time as you renovate the property and pay leasing commissions to put new tenants in place (or renew existing tenants).
Lower Cap Rate = Higher Cost
Let’s look at the math and see how price changes with cap rates using a consistent NOI.
10% Cap Rate = $10,000 NOI / $100,000 Price
9% Cap Rate = $10,000 NOI / $111,111 Price
8% Cap Rate = $10,000 NOI / $125,000 Price
7% Cap Rate = $10,000 NOI / $142,857 Price
6% Cap Rate = $10,000 NOI / $166,667 Price
5% Cap Rate = $10,000 NOI / $200,000 Price
Wow! The difference between the price buying at an 8% cap rate and a 5% cap rate is huge: $125,000 vs $200,000. That’s a 60% price increase for the same NOI.
Key takeaways: (1) lower cap rate = higher cost and (2) this is not linear; price goes up a lot with increasingly lower cap rates. This is great if you are selling and bad if you are buying.
If you can sell at a 5% cap rate instead of a 7% cap rate, you are selling at $200,000 instead of $142,857. This is a 40% increase.
NOI and Costs Can Change Over Time
Let’s go through an example to show the importance of how NOI and costs can change over time as you own a property.
In-Place NOI
You are buying a property 100% leased to one tenant with two years left on the lease. The NOI at time of purchase is $10,000. This is referred to as your “In-Place NOI”.
Market NOI
You believe you can increase the rent when the tenant’s lease expires in two years and increase the NOI to $15,000. This is referred to as your “Market NOI”.
Now let’s transition to your costs.
Purchase Price
You are paying the seller $165,000. This is the purchase price.
Total Acquisition Costs
But…you have to pay various additional costs to buy the property such as legal and inspection fees. Your total costs to buy the property are $170,000. This is your “Total Acquisition Costs”.
Total Costs at Stabilization
And…to hit the rent target you want when the lease expires in two years, you are going to have to renovate the property and pay a broker leasing commission. Let’s assume all of this can be done for $30,000.
Your costs are now $165,000 + $5,000 + $30,000 = $200,000.
Purchase price + closing costs + renovation/commission costs. This is referred to as your “Total Cost at Stabilization”.
Your Math Building Blocks
We’ve covered a lot. Let’s summarize and see what this tells us.
$ 10,000 - In-Place NOI based on the existing lease.
$ 15,000 - Market NOI based on what you think it could lease for in two years.
$165,000 - Purchase Price that you pay the seller.
$170,000 - Total Acquisition Costs including your closing costs.
$200,000 - Total Cost at Stabilization including your renovation and commission costs.
Now we can do some cool and simple things to calculate the cap rates to tell us more about the investments.
Cap Rate Calculations
Going-In Cap Rate (Seller’s View): $10,000 / $165,000 = 6.1%
Going-In Cap Rate (Buyer’s Reality): $10,000 / $170,000 = 5.9%
Stabilized Cap Rate (Buyer’s Goal): $15,000 / $200,000 = 7.5%
The $30,000+ Error
The one that gets the most muddled up in discussions is the last one. People often use the calculation of Market NOI divided by Total Acquisition Costs:
$15,000 / $170,000 = 8.8%.
They forget that they will need to spend an additional $30,000 to achieve that increased rent and NOI. Be careful.
Finding Meaning in the Math
So what does all this tell us?
In this example the buyer’s going in cap rate is 5.9% but will grow to 7.5% once the rent is increased in two years. This shows you how the going in cap rate may not tell the whole story of what the property could be worth, particularly at times when market rents have grown significantly.
From the outside, someone may question you buying in at a 5.9% cap. They might not know that you see a path to get to a 7.5% cap rate, which makes the investment much more attractive.
Key Takeaways
You will hear cap rates talked about regularly. Now you know how simple the math is. Don’t be shy about asking someone to clarify what they are referring to with their calculations.
NOI: in place or market?
Cost: purchase price or all in acquisition costs or total costs at stabilization?
Don’t be surprised if they don’t really know or have even made a math error. Be humble and supportive. We are all still learning.
Professor Bateman
5 Tax Advantages That Make Real Estate Investing So Powerful
How to legally reduce your taxes while building wealth (including one strategy that lets you defer taxes indefinitely)
How to legally reduce your taxes while building wealth (including one strategy that lets you defer taxes indefinitely)
One of the things that makes real estate investing so special is the way it is treated from an income tax perspective. This is true both during your ownership of a property and at the time of a sale.
There are at least five tax advantages of real estate investing:
Depreciation: reduces your taxable income while you own it.
Refinancing: refinancing a property is not a taxable event.
Capital Gains: as long as you own the property for at least one year, the gain from a sale is treated as long-term capital gains.
1031 Exchange: if you sell a property and buy another one of “like-kind” within 180 days, you are able to defer your tax until you sell the second property.
Step-Up in Basis: when you die, your heirs get a new tax basis at the market value of the property.
All of these can be combined to allow you to keep more of your money.
You don’t need to be an accountant or a math major to take advantage of these. You just need to know they exist and work with a qualified tax accountant to put the tax laws to work.
Let’s dig in.
A quick public service announcement before we get into the details.
In these newsletters, I am guiding you through the world of real estate investing. In some areas, I will be able to give you enough detail to be very knowledgeable.
In others, I will give you the high level overview but will not be able to give you nearly enough details to be self-sufficient without an expert.
Tax is one of these areas.
People spend their whole career learning all the details of tax accounting and the changing laws. There is no way to cover this level of detail in a newsletter.
So take this information for what it is: an initial guide to help you identify opportunities and ask the right questions of the experts.
Here we go…
The Basics of (Federal) Income Taxes
In order to understand the tax advantages of real estate investing, we need to cover some basics of federal income tax.
Do you really know how income taxes work in the United States? Maybe you understand the concept, but not the details.
Here are the basics.
The money you earn (income) is treated in four main ways:
Ordinary Income: your salary/bonus.
Passive Income: real estate income, royalties, passive businesses.
Dividends: from stocks.
Capital Gains: from selling stock, real estate, a business, etc.
It can get more complicated than this, but these four are the basics that will affect most people including real estate investors.
Ordinary income is the least tax efficient, which is taxed up to 37% at the highest tax bracket.
For many taxpayers, the long-term capital gains rate is 15%, but it can be 0% for lower incomes.
Big difference.
Note that dividends from stocks are unique. Some are taxed as ordinary income. Some are taxed as capital gains.
Now most of us won’t pay 37% tax on our ordinary income. Federal income tax works on a sliding scale. As of 2025, it starts as low as 10% and scales up to 37%.
Example: if you are single and earn $100,000, your taxes will be:
10% on the first $11,925 = $1,192.50
+ 12% on the amount between $11,926 and $48,475 = $36,550 x 12% = $4,386.00
+ 22% on the amount between $48,476 and $100,000 = $51,525 x 22% = $11,335.50
= Total tax of $16,914 or 16.9% effective tax rate.
Once you have higher income, taxes get much higher. For example, a married couple making $500,000 would pay 22.8%. If they earn $1M, they would pay $29.4%.
You can find the data to do the math on your income here: https://turbotax.intuit.com/tax-tools/calculators/tax-bracket/
But what about passive income from real estate investing?
Passive income generally follows the same tax brackets as ordinary income but has the ability to be reduced by passive losses (example: depreciation). We will get more into this in the next section.
Remember that all of this is only the federal tax, not state tax.
What about state taxes? They are different in each state. Some are zero (Texas, Florida). Some are on a sliding scale (California). You will have to research that on your own.
Now we have the basics of how taxes work, let’s explore the five magical aspects of taxes as they relate to real estate investing.
Depreciation
Key Benefit: reduces taxes on cash flow from real estate investments. You pay less (or no) tax on the cash flow you get while owning the property.
The concept behind this is that you have to pay money to buy the property, but the property will depreciate (i.e. get run down) over time. From a maintenance perspective, it would be better to own a brand new building than one that is 30 years old.
So here is how it works.
You buy a property for $3,900,000. After discussing with your tax accountant, you allocate $1,150,000 of the cost to the land and $2,750,000 to the building. You only depreciate the building, not the land.
If it is an apartment or a 1-4 unit residential investment, you can depreciate it over 27.5 years per the tax rules. Office, industrial, and retail are depreciated over 39 years.
Continuing our example: $2,750,000 allocated to the building divided by 27.5 = $100,000 per year.
This $100,000 is a non-cash expense that you deduct from your income each year.
Let’s say you are earning 7% per year on the $3,900,000 investment = $273,000 per year. You reduce it by the $100,000 of depreciation to $173,000 of taxable income.
$273,000 cash flow - $100,000 depreciation = $173,000 taxable income.
You don’t have to pay tax on $100,000 of the income which would have been taxed at the 24% or even 32% tax bracket. Pretty cool!
It gets even more powerful if you have a loan on the property.
For example, you borrow 50% of the cost of the property. 50% x $3.9M = $1.95M. For simple math, assume your interest rate is also 7% so you have “neutral” leverage.
Don’t worry if you don’t understand the debt part. We will get to it in a later session.
Instead of earning $273,000 per year, you only earn half of this as the other half goes to pay debt service.
50% x $273,000 = $136,500.
Reduce the $136,500 by $100,000 in depreciation leaves you with only $36,500 of taxable income.
$136,500 cash flow - $100,000 depreciation = $36,500 taxable income.
Amazing!
It is almost tax free.
If can get even more powerful if you do a “cost segregation study”, which allows you to depreciate some parts of the buildings like plumbing, flooring, and interior walls faster. We won’t go into the details here. All of this is based on the Modified Accelerated Cost Recovery System in the U.S. tax code.
Can I use depreciation to reduce the taxes related to my salary/bonus (ordinary income)?
No.
You cannot use depreciation (passive losses) from real estate to offset your salary/bonus (ordinary income) unless you meet certain qualifications as a real estate investor. Most people will not meet these qualifications. Consult with your tax accountant to understand if you qualify. Passive losses can only offset passive income.
Key Takeaway: depreciation is a non-cash expense that will reduce your taxable income and taxes from real estate investing each year while you own an investment property.
Most of the income I get from my LP investments discussed in past newsletters is shielded by depreciation, allowing me to keep all of the cash flow I get while paying little to no tax on it. See 5 Ways to Invest in Real Estate (From $60 to All-In).
Refinancing
Key Benefit: proceeds (i.e. cash) you receive from a refinance are not considered a taxable event.
We will keep this one short and sweet.
You increase the value of a property and put more debt on it. Example: you increase the debt from $1,000,000 to $1,500,000.
You payoff the original loan and have a “cash out” refinance of $500,000.
$1,500,000 new loan less $1,000,000 original loan = $500,000 of excess cash you keep.
The IRS does not view this as a taxable event. Wow!
You will still need to pay off more debt eventually, but it is nice to have the cash now to reinvest.
I have had many “cash out” refinances in my investing history.
Key Takeaway: refinances are a tax efficient way to pull cash out of a property that has increased in value.
Capital Gains
Key Benefit: if you own an investment property for at least one year, you pay a lower tax rate on profits from the sale of that property as compared to ordinary income.
This is true for not only real estate investments, but almost all investments. Other examples are:
Sale of a business you created or bought.
Sale of stock.
There are two terms to learn here:
Long-term capital gains relate to investments held for at least one year.
Short-term capital gains relate to investments held for less than one year.
Long-term capital gains have a sliding scale just like ordinary income but it ranges from 0% to 20% depending on income. Higher earners may pay an additional 3.8% (Net Investment Income Tax), making the maximum 23.8%. To geek out on the details, you can go to the IRS page here: https://www.irs.gov/taxtopics/tc409
For the rest of you, just remember that long-term capital gains are what you want when you sell a property as they are almost always lower than short-term capital gains which are taxed the same as ordinary income discussed above, which ranges from 0% to 37%.
One more thing…
The negative side of depreciation comes into play here. Remember the $3.9M property example from the depreciation section. Let’s assume we held the property for three years and enjoyed the benefit of $100,000 per year of depreciation for a total of $300,000.
Our tax basis at time of sale is $300,000 less than when we originally bought the property.
$3,900,000 minus $300,000 = $3,600,000.
If we sell the property for $4,900,000 we will have $1,300,000 of gain.
$4,900,000 minus $3,600,000 = $1,300,000.
This is $300,000 more of gain than if depreciation did not exist.
But, we are paying a lower tax rate on this $300,000 as compared to the savings we got by not paying ordinary income on that same $300,000. It is more complicated than this, but it typically works to a taxpayer’s advantage.
Key Takeaway: if you are going to sell your investment property, try to hold it for at least one year to make your capital gains long-term, which are taxed at a lower rate than if you held it for less than one year.
Is there even a way to avoid long-term capital gains? Not exactly, but they can be deferred.
1031 Exchange
Key Benefit: if you sell your investment property and buy another one of “like-kind” within 180 days, you defer the taxes from the sale until you sell the second property.
This is pretty cool. As far as I know, this is unique to real estate investing.
Let’s continue with our example.
You bought a property for $3,900,000 and sold it after three years for $4,900,000. You find a new property to buy for $4,900,000 and “1031 exchange” into that new property.
This is not a taxable event because it is not considered a sale for tax purposes.
No sale.
No long-term capital gains.
No tax.
You can do this over and over again from property to property.
Just be careful to follow the rules and meet the qualifications:
It must be of “like-kind”. In simple terms, it must be another investment property.
You must use a “qualified intermediary”. Think of this as a 3rd party you pay to make sure you follow the tax rules.
The new (replacement) property or properties must be of the same or greater value as compared to the one you are selling.
You must identify the new property within 45 days of selling your property. You can identify up to three properties.
You must buy the new property within 180 days of the sale of the old property.
This can be a complicated and expensive process as you will be paying the qualified intermediary, but the tax deferral benefits can be significant.
Additionally, if you don’t do a 1031 exchange when you sell the second property, then your capital gains will be even higher than if you had just bought the second property with “fresh” cash because your tax basis will be equal to the tax basis from the first property.
Said another way, the old tax basis from the property you sold carries forward to the new property you bought.
Key Takeaway: if you buy a new property within 180 days, you can defer the capital gains tax from a property you are selling.
But what if you never want to pay long-term capital gains? There is an option, but it has its downsides.
Step-Up in Basis
Key Benefit: when the owner of a property dies, the heirs (or surviving spouse) get a step-up (increase) in tax basis to the market value of the property at time of death.
I told you that you weren’t going to like it.
You or a loved one are dead.
Here’s how it works:
The property owner dies.
The property is valued at market as of the date of the owner’s death.
The tax basis of the heirs (or surviving spouse) is the market value.
This is true for not just real estate, but anything owned by the person who dies including stocks, a home, a business, etc.
Note that this is different from estate (inheritance) tax. Estate tax is a 40% tax that the estate (not the heirs) pays on inheritance over an amount set by the IRS. As of 2025, it is just under $14M per person ($28M for married couples). This reduces the amount the heirs ultimately receive.
Example: if you and a sibling inherit $20M of assets from an unmarried parent, the math would be:
$20M less $14M IRS allowance = $6M x 40% = $2.4M in estate tax.
$20M less $2.4M in estate tax = $17.6M in after tax inheritance.
Remember that 1031 exchange we did? The tax basis would be increased to the market value at time of death. This is the way to ultimately avoid the capital gains tax from the sale of a real estate investment.
Just remember it comes with a meaningful cost: you or a loved one need to die.
Key Takeaway: when someone dies, all assets they pass on to their heirs or surviving spouse (including real estate investments) gets a “step-up” in tax basis to the market value at time of death.
Summary
We have covered a lot.
Let’s recap the summary we started with:
Depreciation: reduces your taxable income while you own it.
Refinancing: refinancing a property is not a taxable event.
Capital Gains: as long as you own the property for at least one year, the gain from a sale is treated as long-term capital gains.
1031 Exchange: if you sell a property and buy another one of “like-kind” within 180 days, you are able to defer your tax until you sell the second property.
Step-Up in Basis: when you die, your heirs get a new tax basis at the market value of the property.
You don’t need to be an expert in any of this. You just need to remember that they exist and work with a tax accountant who understands real estate investments.
Side note: as a real estate investor, you want to assemble the right team. Turbo Tax or the tax accountant you are currently using as a salaried employee and stock investor may not be the right fit for you as a real estate investor. Ask around and take the time to find the right accountant.
Most important: remember that real estate investing has many tax advantages that will benefit you both during your ownership of a property (depreciation reduces taxable income) and when you sell a property.
Are there more tax advantages I am missing? Email me at bateman@creprofessor.org to let me know. As a life-long learner, I am always looking to grow.
Professor Bateman
Special thanks to my anonymous friend and real estate tax specialist who helped me fact check this and add clarity where needed. You know who you are. I appreciate you!
5 Ways to Invest in Real Estate (From $60 to All-In)
Which investor are you: Hands Off Harry, Rockstar Reggie, or All-In Alex? Here's how to choose your path.
Which investor are you: Hands Off Harry, Rockstar Reggie, or All-In Alex? Here's how to choose your path.
By now you may be getting excited about making your first real estate investment.
Good news!
If you are reading between Monday and Friday 9:30 a.m. to 4:00 p.m. Eastern time, then you can invest right now.
How?
The most passive and liquid way to invest in real estate is by buying shares of a real estate investment trust (REIT). By buying shares of a REIT you will own a small piece of a company that owns and operates real estate.
REITs are just one of the many ways to invest in real estate.
Let’s dig in to the many options.
Ways to Invest in Real Estate: From Passive to Active
Owning shares of a REIT.
Investing as a limited partner (LP).
Buying a property by yourself.
Buying a property with someone as equal partners.
Buying a property as the general partner and raising money from LPs.
Option 1: Owning Shares of a REIT
REITs are public companies that exclusively focus on real estate. They are required to distribute 90% of their taxable income to shareholders (i.e. you) as dividends.
An example of a REIT headquartered here in San Diego, CA is Realty Income Corporation (NYSE: O). As of this writing, their stock price is trading around $61 per share and they have a 5.28% annual dividend ($3.24 per share) that is paid monthly.
A benefit of REITs is that they are public stock, so you can sell them at any time. If you are investing in an S&P 500 index fund, then you have exposure to around 30 REITs.
Who knew you were already a real estate investor!
Option 2: Investing as a Limited Partner (LP)
Investing as a LP is another passive way to invest in real estate. The general partner (GP) does 100% of the work and makes all decisions*. In exchange for doing all the work, the GP earns fees and often collects an oversized share of the profit if the deal does well (this is known as “promote”).
So what is the tradeoff of being a LP? Control and liquidity.
You don’t have any control over decisions.
You can’t access the money until the property is sold.
The fees and promote paid to the GP reduce your returns.
But on the positive side:
It is totally passive. A pipe bursts at a property at 3am? The GP has the deal with it.
I have made 20+ of my investments as an LP. In my experience it is a great way to invest in real estate while keeping focused on your day job.
So how do you find these opportunities?
In my case, I met people through working in the industry. When I heard of people or companies buying the types of properties I was interested in, I asked if I could invest. Some said no. Some said yes. Over time I built up a portfolio of LP investments.
There are also crowdfunding groups out there that connect GPs and LPs. A couple examples are Realty Mogul and Crowd Street.
One of the challenges that you will need to work through is that most of these groups require you to be an “accredited investor” as defined by the SEC. Generally, you need to have a net worth over $1 million (excluding your primary residence) OR have earned $200,000 (or $300,000 jointly) in each of the two most recent years. Not everyone can meet these criteria.
If this is your situation, don’t be discouraged.
Options 1, 3, and 4 don’t have these restrictions.
Many successful real estate investors started by focusing on increasing their earnings through their day job or with a single property investment (option 3) and built their way up to becoming an accredited investor over time.
Option 3: Buying a Property by Yourself
There are no SEC requirements for buying a property by yourself. It is effectively like becoming a parent: not everyone is qualified, but anyone can do it.
This is more work than investing as an LP, but you can figure out ways to make it relatively passive so that you can focus on your day job.
The Remote Investor Approach
In this scenario, you find a company that is both a broker and property manager. They show you lots of properties to buy. You select one and they help you with the due diligence, closing, loan, inspections, etc. Once you close on the property (i.e. you own it), they handle all the day-to-day and reporting. All you do is tell them what decisions you want to make.
You could take this approach in the local market you live in or even out of state.
I know someone who bought a number of rental homes in another state this way and didn’t see the properties for the first two years of ownership.
This is not for everyone.
I don’t think I could handle not seeing the properties before I bought them, but for others this is fine. If you go this route make sure you find a group you can trust.
There are many examples of people who bought homes in the Midwest US for $100,000 ($30,000 of equity/cash) interviewed on the Bigger Pockets podcast.
Keep in mind that this is only a “passive” version based on the amount of your time it takes. For some this would be an “active” version because of the stress it could cause.
The Hands-On Local Approach
In this scenario, you buy a property in the same town you live in. You can see it, touch it, get to it within an hour if needed.
You minimize the support you get from 3rd parties (brokers, property mangers, accountants, etc) because you don’t want to pay any fees so you can maximize your cash flow and profit. You don’t trust anyone to pay attention to the real estate like you will.
So far so good.
And then something goes wrong at the property. Eventually something will ALWAYS go wrong.
Here’s an example: You own a duplex. A pipe bursts and floods the property. The tenant calls you at 3am or when you about to deliver a presentation at work. Even if you have a group of great vendors, you still have to figure out how to deal with it.
I experienced dealing with a roof leak at a property I own while on vacation with my family over the winter break. It sucked. As soon as I returned from vacation, I hired a property manager to get me out of the “front line” of managing the property. I happily pay them each month for this peace of mind.
So which is the best option?
There is no right answer. It is all tradeoffs. You need to understand what is important to you.
There is nothing wrong with deciding that investing in REITs and as an LP (options 1 & 2) is best for you right now. You can always change options over time.
Option 4: Buying a Property with Someone as Equal Partners.
Let’s continue up the scale of becoming a more active investor.
In this case, you and a friend decide to buy a property 50/50. Ideally you have complimentary skill sets and pre-agree to how you will divide up the work.
You only have to come up with 50% of the equity/cash and you have a partner to brainstorm with.
Partnerships can be excellent.
They can also be very challenging.
They are like a marriage. You are together for the life of the investment. Remember: real estate cannot be converted to cash instantly. It takes time to market and sell a property. See lessons 14 & 15 from my previous newsletter.
My advice: only partner with someone you really trust. This should be someone you would trust with your bank account. And always, ALWAYS have a written partnership agreement that clearly documents decision making, including the right to sell the property.
When you have an equal partner, you both need to agree on what to do. Decisions that will come up:
The roof is leaking. Do you patch it or replace it?
A tenant pays late each month, but always pays by the end of the month. Do you renew them at the end of their lease or vacate the property and try to find a better tenant?
The property has increased in value by 50% since you bought it. Do you sell it? Refinance? Do nothing and enjoy the higher cash flow?
There are many, many issues that will come up. When you have a partner it is not just your decision. You and your partner need to agree.
Things may start out well, but you and your partner may have very different circumstances a few years into owning the investment. Examples:
Your partner gets married and wants to sell the property so she has cash to buy a house. You are still single and like the flexibility that the cash flow from the property provides.
You want to invest the cash flow into the property to make it the best in the neighborhood. Your partner wants to squeeze every penny from the property, making you feel like a slumlord.
Bottom line: decision making will be more complicated by having a partner than if you own the property by yourself.
BUT the right partnership can give you an ally and sounding board as you begin your real estate investing journey.
Option 5: Buying a Property as the General Partner and Raising Money from LPs.
This is the opposite of option 2: investing as a limited partner (LP) where someone else does all the work. In this case you are the general partner (GP). You do all the work.
You find the deal and operate it. You find LPs to invest in the deal. You collect fees and earn an oversized share of the profit if the deal does well (the promote).
Fees and promote? Sounds pretty good.
So what’s the catch?
It is a TON of work.
Here’s some examples of what you will need to take on if you are the GP:
You do all the work.
You typically enter into a purchase agreement to buy a property before you have raised all the equity/cash required. Although you still have the right to back out before your due diligence period expires (typically 30 day), you are still putting your reputation on the line. You don’t want to earn a reputation of someone who always backs out of deals.
You will need to “dial for dollars” to find the LPs. This will occur simultaneously with performing the due diligence AND finding a loan. You will feel stretched in many directions.
You will need to keep the investors up to date on the deal. Even when you do this in a structured way, it can consume your time in unintended ways. Example: you are out for a walk and coffee with your spouse on a Saturday morning. You run into an investor who wants an update on why the deal is not performing as planned. So much for your peaceful morning...
There are many more things you will do as a GP. It can take up a ton of time and is tough to do if you have a traditional W2 job.
Putting together deals as a GP is not for the faint of heart. You need to be all in and stick with it for the long haul.
So Which is the Right Option for You?
It all depends on your goals and needs. Here are some examples I created to help you think about it.
The Passive Approach (Options 1 & 2)
“Perfectly Passive Penny” - Penny invests in real estate exclusively by buying shares in REITs. She holds these shares for the long term.
“Hands Off Harry” - he invests exclusively as a LP with people he trusts. He stays focused on earning money in his day job, while regularly investing in both real estate and the stock market. His tax returns are made more complicated by his LP investments, but he feels this is an acceptable trade-off. See lesson 16 from my previous newsletter.
The Side Hustle (Options 2, 3, & 4)
“Freakout Frank” - just like Harry, he invests as a LP. Unlike Harry, he constantly calls the GP for updates and ask confrontational questions. He invests as a LP, but acts like a GP. Note: if you go the GP route, avoid taking money from a Frank.
“Active Alice” - she buys a duplex and lives in one half. She does all the home improvements at nights and on the weekend. Eventually she will sell her duplex and buy a four-plex.
“Patient Peter” - he uses money he has saved from the last two years of bonuses in his day job to buy a rental property out of state. It doesn’t take up much of his time because he hires a team to manage it. As the property increases in value, he refinances it and uses the refinance proceeds to buy another property. Over time, he assembles a portfolio of properties that provide him passive income equal to his salary.
All In
“Rockstar Reggie” - Reggie works for a real estate company. He is humble, driven, and constantly looks for ways to add value to the company and the properties. His work has been recognized, and he is now able to invest alongside the owners as a GP and participate in a small portion of the promote.
“All in Alex” - Alex creates her own real estate company and raises money from LP investors. She has saved up money to live frugally for two years while she gets her real estate company off the ground.
So Who are You?
You don’t need to pick just one.
I started as a Harry, soon became a Reggie, and then took money I made as a Reggie to become more of a Harry. Passive to active to passive.
Be a student of yourself. Don’t try to get rich quick. Successful real estate investing is best done as a long game. See lesson 3 from my previous newsletter.
Remember, patience is a superpower.
Combine that with self reflection, clarity of thinking, focus, and hard work…then you have a magical combination.
Good luck on your journey to becoming a real estate investor!
Professor Bateman